
You’re Retired With $2 Million. Why Are You Still Afraid to Spend It?
Many retirees with $2 million or more still hesitate to spend after decades of saving. Learn how Social Security, taxes, healthcare, longevity, market risk, and legacy goals can help determine how much you can comfortably spend in retirement.
Many retirees with $2 million or more still hesitate to spend because they spent decades learning how to save. The solution is not simply spending more. It is determining how much your retirement plan can support after accounting for Social Security, taxes, market declines, longevity, healthcare, and legacy goals. Greenbush Financial Group helps retirees turn those variables into a practical “permission to spend” number.
Why Is Spending So Difficult After You Retire?
For 30 or 40 years, successful retirement savers are rewarded for accumulating money.
You contribute to the 401(k), invest extra cash, and avoid unnecessary withdrawals. Then you retire and suddenly you are supposed to reverse that behavior.
Even when you have $2 million saved, withdrawing $50,000 can feel like you are moving backward.
That feeling is understandable, but your investment balance alone does not determine whether you can afford to spend more.
A better question is:
What does your $2 million actually need to accomplish?
It may need to fund your lifestyle, taxes, healthcare, travel, future home repairs, a surviving spouse, and perhaps an inheritance for your children.
Once those goals are defined, you can determine how much of the portfolio is actually needed and how much represents a safety margin.
Start With Your Retirement Income Gap
The simplest starting point is to compare what comes in with what goes out.
Add up your expected annual spending and taxes, then subtract reliable income such as Social Security and pensions.
The remaining amount needs to come from your investments.
Example: Retired With $2 Million
Assume a retired couple has:
$2 million invested
$70,000 of annual Social Security
$120,000 of annual lifestyle spending
$15,000 of estimated taxes
Their total annual cash need is approximately $135,000.
After Social Security, they need about $65,000 per year from their portfolio.
That represents an initial withdrawal of approximately 3.25% of their $2 million portfolio.
That percentage does not automatically mean the spending is safe. But now we have a number that can be tested.
How Do You Create a “Permission to Spend” Number?
Your permission-to-spend number is the amount your retirement plan can reasonably support after accounting for the major risks you may face.
A simple starting calculation is:
Lifestyle spending + taxes + major planned expenses − Social Security and pension income = required portfolio withdrawals
Then stress-test that number.
Ask:
What if the market falls early in retirement?
What if one or both spouses live into their 90s?
Have healthcare and potential long-term care costs been considered?
What happens financially when the first spouse dies?
Are large home repairs or vehicle purchases included?
How much do you actually want to leave to your children?
If your desired spending continues to work under reasonable stress tests, you have stronger evidence that you can afford it.
What If the Market Drops?
One of the biggest risks is a major market decline early in retirement.
Suppose the couple's $2 million portfolio falls 20%, temporarily reducing it to approximately $1.6 million before accounting for withdrawals.
Their $65,000 withdrawal is no longer 3.25% of the portfolio. It is now approximately 4.1%.
That does not mean they immediately need to cancel every vacation.
It means their plan should have flexibility.
That could include maintaining a cash reserve, holding a diversified investment allocation, and identifying discretionary expenses that could temporarily be reduced during a prolonged market decline.
The important question is not whether the market will decline. It eventually will.
The question is whether your retirement plan can absorb it without requiring major permanent changes.
What If You Live Into Your 90s?
Longevity is another reason retirees hesitate to spend.
Instead of allowing “What if I live to 100?” to become a reason to never use your money, model longer life expectancies directly.
A retirement projection can test what happens if one or both spouses live to 90, 95, or beyond.
It should also account for what happens after the first spouse dies. Social Security income may decline, tax filing status may change, and the surviving spouse may still have many of the same household expenses.
If your spending works even with conservative longevity assumptions, that provides much more useful information than simply assuming you need to preserve every dollar.
Healthcare Should Be a Number, Not an Unlimited Unknown
Healthcare and long-term care are legitimate retirement risks.
But “I might need the money for healthcare someday” can become a reason to never spend anything.
Instead, quantify the risk as much as possible.
Consider:
Medicare premiums and supplemental coverage
Normal out-of-pocket healthcare costs
Existing long-term care insurance
HSA balances
Potential long-term care expenses
How much of those costs you intend to self-fund
You cannot know exactly what healthcare will cost decades from now. You can, however, build a reasonable reserve into the plan.
That allows healthcare to become a planning assumption rather than an undefined reason to avoid spending.
How Much of Your $2 Million Is Actually Surplus?
This is often the most important question.
Suppose your retirement analysis indicates that $1.5 million is reasonably needed to support your lifestyle and future risks under conservative assumptions.
That leaves approximately $500,000 of additional cushion.
It does not mean you should immediately spend $500,000.
It means those dollars may have a different purpose.
They could potentially fund:
More travel
Gifts to children or grandchildren
Home improvements
Charitable giving
Additional financial security
A larger inheritance
There is a major psychological difference between thinking, “I cannot touch my $2 million,” and understanding, “My plan requires approximately this much, and the rest is my safety margin.”
Do You Actually Want to Leave the Money to Your Children?
Many retirees say leaving money to their children is important.
The next question should be: How much?
There is a difference between intentionally planning to leave $500,000 and leaving $2 million because you were afraid to spend throughout retirement.
Neither outcome is necessarily wrong.
But your legacy should ideally be a goal, not an accident.
If your retirement projection shows a substantial estate remaining even under conservative assumptions, you may have a choice: leave more later, give some away during your lifetime, spend more on experiences today, or simply maintain a larger safety margin.
Don't Forget About Taxes
Where your $2 million is held matters.
A retiree with $2 million in traditional IRAs has a different spending and tax situation than someone with assets spread among traditional IRAs, Roth IRAs, taxable brokerage accounts, and cash.
Traditional IRA withdrawals can increase taxable income and potentially affect Medicare IRMAA premiums. Future required minimum distributions can also increase taxable income later in retirement.
This is why spending decisions should be coordinated with:
Roth conversions
Social Security
Capital gains
Required minimum distributions
Medicare
The surviving spouse's future tax situation
Sometimes spending or converting tax-deferred money earlier can be part of a longer-term tax strategy.
When Can You Reasonably Give Yourself Permission to Spend More?
You may have room to spend more when:
Social Security and pensions cover a meaningful portion of core expenses
Portfolio withdrawals remain reasonable under conservative assumptions
The plan can withstand a significant market decline
Longevity into the 90s has been tested
Healthcare and long-term care risks have been considered
Major future expenses are included
Survivor income and taxes have been modeled
Your desired legacy is already incorporated
You still maintain a meaningful safety margin
You may need to remain more cautious if your plan depends on strong investment returns, requires consistently large withdrawals, has little flexibility during bad markets, or does not account for major future expenses.
Common Mistakes Retirees Make
Some of the most common mistakes include:
Treating principal as money that can never be spent
Using a generic withdrawal percentage without looking at the household plan
Keeping an excessive healthcare reserve with no specific calculation behind it
Ignoring the surviving spouse's financial situation
Forgetting about taxes and future RMDs
Leaving a large inheritance by default instead of by choice
Waiting until health declines to begin using money for important experiences
Final Thoughts
If you have $2 million and are still afraid to spend, the answer is not simply to spend more.
The answer is to determine what your money needs to accomplish and test whether your desired lifestyle fits within those boundaries.
At Greenbush Financial Group, we look at retirement spending in the context of income, investments, taxes, market risk, longevity, healthcare, survivor needs, and legacy goals.
Here is what gives you reasonable permission to spend more: your desired spending continues to work under conservative assumptions and leaves an adequate safety margin.
Here is what tells you to remain cautious: your plan depends on strong markets, high withdrawals, or leaves little room for unexpected expenses.
Retirement savings are meant to provide financial security. But once that security has been established, some of those dollars may also be available to help you enjoy the retirement you spent decades saving for.
Rob Mangold
About Rob……...
Hi, I’m Rob Mangold. I’m the Chief Operating Officer at Greenbush Financial Group and a contributor to the Money Smart Board blog. We created the blog to provide strategies that will help our readers personally, professionally, and financially. Our blog is meant to be a resource. If there are questions that you need answered, please feel free to join in on the discussion or contact me directly.
Frequently Asked Questions
-
Is $2 million enough to retire?It can be. Whether $2 million is enough depends on your spending, Social Security and pension income, taxes, retirement age, healthcare costs, investments, longevity, and legacy goals.
-
How much can I spend each year with $2 million?Start by subtracting reliable income from your annual spending and taxes. The remaining portfolio withdrawal should then be tested against market declines, inflation, longevity, healthcare costs, and other financial goals.
-
Is a 4% withdrawal rate safe with $2 million?A 4% initial withdrawal equals $80,000 from a $2 million portfolio. Whether that is appropriate depends on your retirement timeline, investments, inflation, other income, taxes, and ability to adjust spending.
-
Should I be afraid to spend principal in retirement?Not necessarily. Retirement assets were generally accumulated to help fund retirement. The important question is whether withdrawals are sustainable within your overall financial plan.
-
How much should I leave my children?There is no standard amount. Establishing a specific legacy goal can help determine whether additional assets should be preserved, gifted during your lifetime, or available for your own retirement spending.

The First 3 Years of Retirement: 7 Financial Decisions That Matter More Than You Think
The first three years of retirement can create valuable planning opportunities. Learn how withdrawals, Roth conversions, Social Security, Medicare, RMDs, and investment decisions can work together to shape your long-term retirement plan.
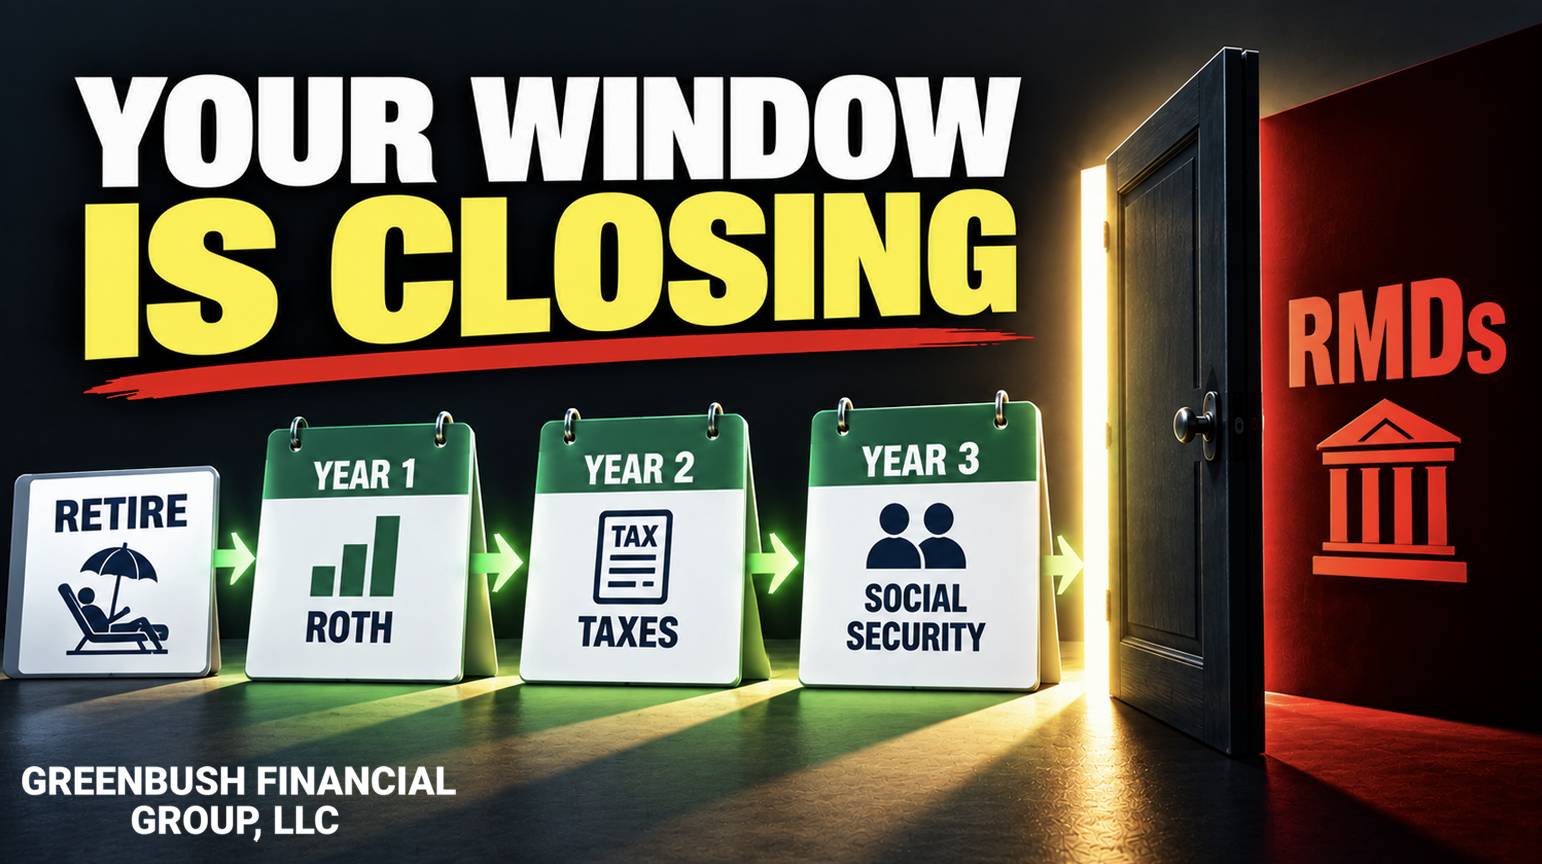
The first three years of retirement can offer valuable planning opportunities, particularly when your paycheck has stopped but Social Security and required minimum distributions have not started. Decisions about withdrawals, Roth conversions, investments, and Medicare often affect one another. Greenbush Financial Group recommends looking at these early retirement decisions as one coordinated plan rather than a series of separate choices.
Why the First Three Years Matter
When your paycheck stops, you suddenly have to decide where your income will come from.
Should you spend cash? Sell investments? Take money from your IRA? Start Social Security?
These decisions are connected.
An extra $50,000 IRA withdrawal, for example, can increase taxable income, reduce your Roth-conversion opportunity, affect capital-gains taxes, potentially increase future Medicare premiums, and reduce future RMDs.
The first few years of retirement may also be some of your lowest-income tax years. If you do nothing, some of those opportunities can disappear.
Consider Mark and Susan.
They are both 64 and retiring with $1.8 million:
$1.2 million in traditional 401(k)s and IRAs
$200,000 in Roth IRAs
$300,000 in a brokerage account
$100,000 in cash
They expect to spend about $90,000 per year after tax and have not started Social Security.
Their situation illustrates seven decisions that can shape the next several decades.
1. Decide Where Your Retirement Paycheck Comes From
There is no universal rule that says you should spend taxable accounts first and Roth accounts last.
Instead, ask:
Which combination of accounts gives us the income we need without creating unnecessary taxes?
Mark and Susan might fund part of their first year's spending from cash, dividends, and their brokerage account rather than automatically taking $90,000 from an IRA.
That could keep their taxable income lower and leave room for another strategy, such as a Roth conversion.
Retirees should also consider directing dividends and interest to cash instead of automatically reinvesting them.
A reasonable cash reserve depends on the household, but maintaining roughly 12 to 24 months of expected portfolio withdrawals in cash and short-term investments can provide flexibility during a market decline.
Key Insight: Your withdrawal strategy should be based on taxes, markets, and future income, not simply which account has the easiest transfer button.
2. Take Advantage of the Retirement Tax Window
For many retirees, there is a gap between their final paycheck and the beginning of Social Security and RMDs.
That can create unusually low taxable-income years.
Mark and Susan have $1.2 million in tax-deferred retirement accounts. If they leave that money untouched, it could grow substantially before RMDs begin.
Instead, suppose they convert $75,000 per year to Roth for their first three years.
They move:
$225,000 from tax-deferred accounts into Roth accounts.
They pay tax today, but future growth on those dollars occurs inside the Roth, and those converted dollars no longer contribute to their future traditional IRA RMD balance.
If $225,000 subsequently grew at 5% for eight years, it would become roughly $330,000.
The goal is not to convert as much as possible. A conversion can affect tax brackets, capital-gains taxes, Medicare premiums, and other parts of the plan.
The better question is:
How much can we convert at a tax rate we are comfortable paying today compared with the tax rate we may face later?
3. Coordinate Social Security With IRA Withdrawals
Social Security should not be considered separately from investment withdrawals.
Suppose Mark is the higher earner and has a $3,200 monthly benefit at full retirement age. Delaying until age 70 could increase that benefit by approximately 24%, before future cost-of-living adjustments.
But delaying means Mark and Susan need to fund those years from somewhere else.
That can be useful.
They might spend taxable assets while completing Roth conversions before Social Security begins. Later, the larger Social Security benefit reduces the amount the portfolio needs to provide.
There is also a survivor consideration.
If Mark dies first, Susan generally does not continue receiving both Social Security benefits. The higher benefit can therefore become particularly important to the surviving spouse.
Key Insight: Delaying Social Security is not always best. Health, longevity, taxes, portfolio size, and survivor needs all matter.
4. Coordinate Roth Conversions, Capital Gains, and Medicare
This is where retirement tax planning becomes a balancing act.
Suppose Mark and Susan own an investment worth $60,000 with a $30,000 cost basis.
Selling it creates a $30,000 long-term capital gain.
During a low-income retirement year, some or potentially all of that gain could qualify for the 0% federal long-term capital-gains rate, depending on their other income.
That could allow them to diversify the portfolio while increasing the cost basis of their taxable investments.
But there is a catch.
If they complete a large Roth conversion first, that additional income can reduce the amount of capital gains eligible for the 0% rate.
Medicare creates another consideration.
Medicare generally uses income from two years earlier when determining IRMAA surcharges. A large Roth conversion or capital gain today could therefore increase Medicare premiums later.
That does not automatically make the transaction a bad idea.
Sometimes paying additional tax or Medicare premiums today creates greater long-term savings.
The important part is knowing the tradeoff before making the decision.
5. Prepare for RMDs Before You Have RMDs
One of the biggest retirement mistakes is waiting until RMDs begin to start planning for them.
Mark and Susan already have $1.2 million in tax-deferred accounts at age 64.
If those accounts continue growing, future RMDs could create more taxable income than they actually need.
Before RMDs begin, they have more control through:
Roth conversions
Strategic IRA withdrawals
Social Security timing
Charitable planning
This becomes even more important when one spouse dies.
The surviving spouse may eventually file as single while still owning much of the same IRA assets. That means narrower tax brackets and lower Medicare IRMAA thresholds.
A Roth conversion today should therefore sometimes be evaluated against the survivor's future tax rate, not just the couple's current rate.
6. Have a Plan for a Bad Market in Year One
Imagine stocks fall 25% six months after Mark and Susan retire.
Their expenses do not fall 25%.
Where does their income come from?
This is why retirement portfolios should be designed differently from portfolios that are still accumulating.
If Mark and Susan need $50,000 annually from their portfolio and maintain $75,000 to $100,000 in cash and short-term investments, they may have roughly 18 to 24 months of withdrawals available without relying heavily on stock sales.
During a major decline, income could come from:
Cash
Short-term bonds
Dividends and interest
Investments that held up better
The goal is to avoid being forced to sell stocks after a major decline simply because the monthly bills are due.
This is called sequence-of-returns risk. Poor returns early in retirement can be particularly damaging when withdrawals are occurring at the same time.
That does not mean retirees should abandon stocks. A retirement lasting 25 or 30 years still needs long-term growth.
The objective is to balance short-term spending needs with long-term growth.
7. Plan for the Expenses and Life Changes That Do Not Fit the Spreadsheet
Retirement rarely follows a perfectly predictable annual budget.
Suppose Mark and Susan decide to spend $100,000 remodeling their home.
Taking $100,000 from an IRA could create a much larger tax bill, reduce Roth-conversion capacity, affect capital-gains taxation, and potentially increase future Medicare premiums.
Paying cash, selling taxable investments, taking an IRA distribution, or financing the project can each produce a different result.
The same planning applies to an RV, new vehicle, vacation home, or other major purchase.
Retirement is also a natural time to review:
Beneficiaries
Wills and trusts
Powers of attorney
Account titling
Long-term-care funding
Emergency reserves
Charitable giving
Charitably inclined retirees may also benefit from donating appreciated securities, using donor-advised funds in certain situations, or eventually making qualified charitable distributions from IRAs after reaching the eligible age.
One practical question is especially useful for married retirees:
If one of us died tomorrow, could the other person manage everything?
The surviving spouse should know where accounts are held, how income is generated, where estate documents are located, and who to contact.
Option A vs. Option B: What Coordination Can Change
Consider Mark and Susan's first three years.
Option A: Autopilot
They withdraw whatever they need from their IRAs, claim Social Security relatively early, complete no Roth conversions, and wait until RMDs begin to worry about taxes.
Their plan may still work.
But several planning opportunities may disappear.
Option B: Coordinated Planning
Instead, they:
Fund some spending from cash and taxable investments
Convert approximately $225,000 to Roth over three years
Delay the higher earner's Social Security when appropriate
Realize selected capital gains during lower-income years
Monitor Medicare IRMAA
Maintain short-term reserves for market declines
They might actually pay more tax during their first three years.
That can be intentional.
They are potentially trading a higher tax bill today for smaller future RMDs, more Roth assets, a larger Social Security benefit, and greater flexibility for the surviving spouse.
That is the difference between minimizing taxes this year and managing taxes throughout retirement.
How Much Can You Safely Spend?
There is no single withdrawal percentage that answers this question.
Your sustainable spending depends on:
Portfolio size
Social Security and pensions
Taxes
Investment allocation
Inflation
Healthcare expenses
Longevity
Large future purchases
For Mark and Susan, the better question is not simply whether $90,000 is a safe percentage of $1.8 million.
It is:
How much does the portfolio need to provide before Social Security begins, and how much will it need to provide afterward?
Retirement income changes over time. Your spending plan should account for those changes.
The First Three Years: A Simple Checklist
Year One
Determine how much you can spend, establish where your retirement paycheck will come from, build cash reserves, review the portfolio, and calculate whether a Roth conversion makes sense.
Year Two
Recalculate taxes, Roth-conversion capacity, capital gains, Medicare exposure, and Social Security timing based on what actually happened during year one.
Year Three
Stress-test the plan for a major market decline, future RMDs, long-term-care costs, large purchases, and the death of either spouse.
What Opportunities Disappear If You Do Nothing?
This may be the most important question.
Doing nothing during the first few years of retirement may not create an immediate problem.
But you may lose:
Lower-income years for Roth conversions
Opportunities to realize gains at favorable tax rates
Additional Social Security growth
Opportunities to reduce future RMDs
Years of planning while both spouses can use joint tax brackets
The cost may not show up today.
It may appear 10 or 15 years later.
Final Thoughts
The first three years of retirement are about more than replacing your paycheck.
Withdrawals affect taxes. Taxes affect Roth conversions. Roth conversions can affect Medicare. Social Security affects future withdrawals. Today's IRA balance affects future RMDs. And all of those decisions can look very different after one spouse dies.
There is no universal withdrawal order or Roth-conversion strategy.
At Greenbush Financial Group, we believe the opportunity is in coordinating these decisions around the household's complete retirement plan.
The first few years of retirement give you something valuable: choices.
The goal is to use those choices before they begin disappearing.
Rob Mangold
About Rob……...
Hi, I’m Rob Mangold. I’m the Chief Operating Officer at Greenbush Financial Group and a contributor to the Money Smart Board blog. We created the blog to provide strategies that will help our readers personally, professionally, and financially. Our blog is meant to be a resource. If there are questions that you need answered, please feel free to join in on the discussion or contact me directly.
Frequently Asked Questions
-
Which account should I withdraw from first in retirement?There is no universal order. The best approach may combine cash, taxable investments, traditional retirement accounts, and Roth accounts based on taxes, spending needs, future RMDs, and Social Security.
-
Should I take Social Security or spend investments first?It depends on longevity, taxes, portfolio size, and survivor needs. Spending investments first can sometimes create additional Roth-conversion opportunities while allowing Social Security benefits to grow.
-
Should I convert my IRA to Roth before RMDs?A partial Roth conversion may make sense if your current tax rate is attractive compared with the rate you or a surviving spouse could face later.
-
How much should I convert to Roth?Consider tax brackets, capital gains, Medicare IRMAA, state taxes, and future RMDs. The appropriate amount should generally be recalculated each year.
-
What happens if the market crashes right after I retire?Cash and short-term investments can provide spending money without requiring immediate stock sales. This is one reason retirement portfolios should be structured around both withdrawals and long-term growth.
-
Why should I worry about RMDs years before they begin?The years before RMDs often provide the most flexibility to reduce future tax-deferred balances through Roth conversions and strategic withdrawals.
This article is for educational purposes and uses simplified hypothetical examples. Tax laws, Medicare rules, investment returns, and individual circumstances can change. The examples are not intended as individualized tax, investment, or legal advice.
How Can I Reduce Taxes in Retirement?
How can you reduce taxes in retirement? Explore strategies for managing retirement withdrawals, Roth conversions, Social Security taxes, RMDs, capital gains, charitable giving, and Medicare premiums to potentially reduce taxes over your lifetime.
By Michael Ruger, CFP®
Partner and Chief Investment Officer at Greenbush Financial Group
You would think tax planning gets easier after you retire. There is no longer a paycheck coming in every two weeks. You may no longer be contributing to a 401(k), receiving bonuses, or dealing with stock compensation. At first glance, your tax return might seem like it should become much simpler.
But from a financial planning perspective, retirement is often when tax strategy becomes more important. The reason is control.
While you are working, much of your income is determined for you. If your employer pays you a $150,000 salary, you generally have $150,000 of wages whether you want the taxable income or not. In retirement, you may have much more flexibility.
You might have traditional IRAs, 401(k)s, Roth IRAs, taxable brokerage accounts, Social Security, pensions, rental income, or even part-time self-employment income. Depending on your situation, you may be able to control how much taxable income you recognize and where your retirement cash flow comes from. That creates opportunities—but it also creates complexity.
Some of the retirement tax strategies we will cover include:
Creating a tax-efficient retirement withdrawal strategy
Using the 0% long-term capital-gains tax bracket
Managing taxes on Social Security benefits
Taking advantage of the enhanced $6,000 senior deduction
Reducing future required minimum distributions
Roth conversion planning
Using qualified charitable distributions
Managing self-employment income in retirement
Harvesting investment losses
Improving the tax efficiency of taxable investment accounts
Evaluating a change in state domicile
Managing Medicare IRMAA premiums
The objective isn't necessarily to pay the least amount of tax possible in any one year. The objective is to manage your taxes over your entire retirement.
Start With Your Retirement Withdrawal Strategy
One of the first places we look when trying to reduce taxes in retirement is the retiree's withdrawal strategy. Most retirees don't have all of their money in one type of account. You may have pre-tax retirement accounts such as traditional IRAs and 401(k)s. You may have after-tax assets in savings accounts and taxable brokerage accounts. You may also have Roth IRAs or Roth 401(k)s.
Each of these accounts is taxed differently. Traditional IRA and 401(k) distributions generally create ordinary taxable income when the money represents pre-tax contributions and earnings. A taxable brokerage account is generally taxed based on interest, dividends, and realized gains rather than the total amount of cash withdrawn. Qualified Roth distributions can potentially be received tax-free.
This gives retirees the ability to create a blended withdrawal strategy.
Don't Automatically Spend All of Your Brokerage Assets First
One of the most common mistakes we see is a retiree who decides to spend all of their cash and taxable brokerage assets before touching their traditional IRA. The reasoning seems logical.
“If I don't withdraw from my IRA, I don't have to pay taxes.”
For the first several years of retirement, that strategy may produce a very small tax bill. But it can create a much larger problem later. If you leave a large traditional IRA untouched, the account can continue growing. Eventually, required minimum distributions may force taxable money out of the account whether you need it or not.
Instead of having relatively modest taxable income throughout retirement, you may end up with very little taxable income during your 60s followed by substantial taxable income during your 70s and 80s. In some situations, it can make more sense to intentionally take traditional IRA distributions during lower-income years. You voluntarily pay some tax today to potentially avoid paying tax at higher marginal rates later.
Think About Lifetime Taxes, Not Just This Year's Taxes
Imagine two retirement strategies.
Under Strategy A, you pay $5,000 in federal income tax this year.
Under Strategy B, you pay $10,000.
Strategy A sounds better.
But what if Strategy A causes your traditional IRA to grow substantially larger and ultimately results in much higher RMDs? Perhaps you save $5,000 today but pay an additional $50,000 or $100,000 of taxes over the next 20 years.
That is why retirement tax planning requires projections.
The question shouldn't simply be:
“How can I reduce my taxes this year?”
It should be:
“How can I structure my income to potentially reduce my total tax liability throughout retirement?”
Take Advantage of the 0% Long-Term Capital-Gains Rate
For retirees with taxable brokerage accounts, one of the most valuable planning opportunities can be the 0% federal long-term capital-gains rate.
For tax year 2026, the top of the 0% long-term capital-gains bracket is $49,450 of taxable income for single filers and $98,900 for married couples filing jointly. The threshold is $66,200 for heads of household. The important phrase is taxable income.
These thresholds don't mean a married couple earning $98,000 can sell an unlimited amount of appreciated investments tax-free. Capital gains are layered on top of other taxable income.
An Example of the 0% Capital-Gains Rate
Assume a married retired couple owns an investment in Company ABC in their taxable brokerage account. The position is worth $100,000.
They originally invested $50,000, so they have a $50,000 unrealized long-term capital gain.
Now assume their other taxable income and deductions leave them with enough room that the entire $50,000 gain remains within the 0% long-term capital-gains bracket.
They may potentially be able to sell the investment and recognize that $50,000 gain while paying 0% federal long-term capital-gains tax on the gain. That can be an extremely valuable planning opportunity.
It could allow the couple to diversify a concentrated investment, raise cash for retirement expenses, or sell and reinvest in a different investment while effectively resetting the cost basis at a higher level. State income taxes can still apply.
The 0% Capital-Gains Bracket Is Not Unlimited
This is where people sometimes misunderstand the rule.
Suppose a married couple has $30,000 of taxable ordinary income and then realizes a $200,000 long-term capital gain.
They don't get the entire $200,000 gain at the 0% federal rate simply because their ordinary income began below $98,900. Instead, the income is stacked.
The ordinary taxable income uses the lower portion of the tax brackets first. Long-term capital gains then stack on top.
Using a simplified example, if $30,000 of taxable income has already occupied part of the 0% capital-gains range, approximately another $68,900 could potentially fit below the $98,900 threshold. Gains above that threshold would move into the applicable higher capital-gains rate, which for many taxpayers is 15%, with higher-income taxpayers potentially facing a 20% rate and possibly the 3.8% net investment income tax as well.
The exact calculation depends on the taxpayer's complete return. This is why we generally determine how much gain to realize before selling a large appreciated investment.
Can You Reduce Taxes on Social Security?
Social Security taxation is another important part of retirement tax planning. A common misconception is that Social Security is either completely tax-free or completely taxable.
Neither is necessarily true.
At the federal level, anywhere from none to as much as 85% of your Social Security benefits can be included in taxable income depending on your other income.
Notice what that does not mean. It does not mean the federal government imposes an 85% tax rate on Social Security. It means up to 85% of the benefit can become taxable income and is then taxed at your applicable income-tax rates.
How Social Security Taxation Is Calculated
The calculation generally begins with what is commonly called combined income or provisional income.
A simplified version includes:
Adjusted gross income before Social Security + tax-exempt interest + 50% of Social Security benefits.
That amount is then compared with certain thresholds.
For a single filer, the primary thresholds are:
$25,000 or less: Benefits generally aren't taxable.
$25,000 to $34,000: Up to 50% of benefits may be taxable.
More than $34,000: Up to 85% of benefits may be taxable.
For a married couple filing jointly, the primary thresholds are:
$32,000 or less: Benefits generally aren't taxable.
$32,000 to $44,000: Up to 50% of benefits may be taxable.
More than $44,000: Up to 85% of benefits may be taxable.
Special rules apply to married individuals filing separately, particularly when they lived with their spouse during the year.
These thresholds have remained relatively low, which means many retirees with pensions, IRA distributions, investment income, or other income sources can find themselves with a portion of Social Security subject to federal taxation.
Why One Extra Dollar of Income Can Have a Bigger Tax Impact Than Expected
Social Security taxation creates what is sometimes referred to as the Social Security tax torpedo.
Suppose you take an additional distribution from a traditional IRA. Not only can that IRA distribution itself be taxable, but the additional income may also cause a larger portion of your Social Security benefit to become taxable. In other words, $1 of additional IRA income can sometimes increase taxable income by more than $1.
This is why withdrawal strategy matters. Using qualified Roth distributions or carefully managing IRA withdrawals in certain years may help control combined income.
However, avoiding taxable income at all costs isn't necessarily the answer. If reducing today's Social Security taxation causes you to build a much larger traditional IRA and substantially larger RMDs later, you may simply be trading a smaller tax bill today for a larger one in the future. Again, lifetime tax planning matters.
The New $6,000 Enhanced Senior Deduction
Taxpayers age 65 and older may also qualify for a newer federal tax deduction.
For tax years 2025 through 2028, eligible taxpayers age 65 or older can claim an enhanced deduction of up to $6,000 per qualifying individual.
That means a married couple in which both spouses qualify could potentially receive a $12,000 deduction. Importantly, this deduction is in addition to the existing age-based additional standard deduction. It is also available to eligible taxpayers whether they use the standard deduction or itemize.
However, the enhanced senior deduction is income-limited.
For single taxpayers, the deduction begins phasing out when modified adjusted gross income exceeds $75,000 and is fully phased out above $175,000.
For married couples filing jointly, the phaseout begins above $150,000 of modified adjusted gross income and is fully phased out above $250,000.
The phaseout occurs at 6% of MAGI above the applicable threshold. This creates yet another income threshold retirees need to consider. A large IRA distribution, Roth conversion, capital gain, or other income event could reduce the senior deduction. As a result, a tax strategy that appears attractive when looking at the income-tax brackets alone may look different once the enhanced senior deduction is included.
Roth Conversions Can Help Reduce Future Retirement Taxes
Roth conversions can be another powerful retirement tax strategy. A Roth conversion involves moving money from a traditional IRA into a Roth IRA and recognizing the taxable conversion amount as income in the year of conversion.
Why voluntarily pay tax today?
Because retirement can create unusually low-income years.
Imagine you retire at age 62.
Your salary stops. Perhaps you decide to delay Social Security. Your required minimum distributions won't begin for years. That period could create an attractive Roth conversion window.
Instead of leaving lower tax brackets unused, you may choose to convert a portion of your traditional IRA each year. The goal is not simply to create a large Roth IRA. The goal is to determine whether paying tax on those dollars today at a particular marginal rate could be preferable to paying tax on them later.
Roth Conversions and Medicare Need to Be Coordinated
There is an important catch.
Roth conversions increase income. If you are on Medicare, a large Roth conversion could potentially increase your Medicare Part B and Part D premiums through IRMAA.
That doesn't necessarily mean you shouldn't process the conversion. Perhaps paying an additional Medicare premium for one year is worthwhile if the conversion substantially reduces future RMDs and future taxes.
But that Medicare cost needs to be included in the calculation. Tax planning and Medicare planning should not occur in separate silos.
RMD Planning Can Reduce Taxes Later in Retirement
Required minimum distributions are another major retirement tax consideration.
Under current federal rules, the applicable RMD age is generally 73 for individuals reaching the applicable age under the earlier SECURE 2.0 schedule, while individuals born in 1960 or later generally have an applicable RMD age of 75.
Once RMDs begin, the IRS requires minimum distributions from applicable pre-tax retirement accounts each year. Whether you need the money or not doesn't matter. This can create a problem for retirees with very large traditional IRA and 401(k) balances.
The $1 Million RMD Problem
Assume you are 65 and have $1 million in traditional retirement accounts.
You don't need the money, so you decide not to touch the account. Now assume hypothetically that by the time your RMDs begin, that $1 million has grown to $2 million. At age 75, the IRS Uniform Lifetime Table currently uses a life-expectancy factor of 24.6. A $2 million prior-year-end balance divided by 24.6 would produce an RMD of approximately $81,300.
That is more than $80,000 of potential ordinary taxable income before considering Social Security, pensions, investment income, or other sources. Compare that with someone who strategically reduced their pre-tax balance before RMDs began through IRA distributions and Roth conversions. If that person's applicable pre-tax balance entering the RMD calculation were only $1 million, an age-75 RMD using the same factor would be approximately $40,650.
The difference can materially affect both income taxes and Medicare premiums. The point isn't that everyone should empty their traditional IRA before RMDs. The point is that RMD planning should begin years before the first RMD is due.
Qualified Charitable Distributions Can Be Extremely Valuable
For retirees who regularly give money to charity, qualified charitable distributions—or QCDs—can be one of the most valuable retirement tax strategies.
You generally become eligible to make QCDs once you have reached age 70½.
A QCD involves directing money from an eligible IRA directly to a qualifying charitable organization. When all requirements are satisfied, the QCD is excluded from taxable income. This is different from taking an IRA distribution yourself, depositing the money in your checking account, and then writing a check to charity.
Why QCDs Can Be Better Than Writing a Check to Charity
Many retirees use the standard deduction.
If you give $10,000 to charity but don't have enough itemized deductions to exceed your standard deduction, that charitable gift may not create an additional federal itemized deduction.
A QCD can change the equation.
Suppose you normally donate $15,000 per year to charity. Instead of writing checks from your bank account, you direct $15,000 from your traditional IRA to eligible charities through properly executed QCDs. Assuming all QCD requirements are satisfied, that $15,000 can be excluded from taxable income. You don't also receive a charitable deduction for the same gift, but you have used pre-tax IRA dollars to accomplish a charitable goal without including the qualifying distribution in income.
QCDs Become Especially Powerful Once RMDs Begin
Now assume your annual RMD is $30,000 and you already plan to give $15,000 to charity.
You direct $15,000 from your IRA to qualifying charities as QCDs.
That $15,000 can count toward satisfying your RMD.
You then take the remaining $15,000 RMD for yourself.
Instead of recognizing $30,000 of taxable RMD income and potentially receiving little or no incremental tax benefit from a separate charitable contribution, you may only have $15,000 of that $30,000 included as taxable IRA income, assuming the QCD is otherwise fully excludable.
Reducing adjusted gross income can have benefits beyond the ordinary income-tax calculation because AGI can affect other parts of the tax return and Medicare premiums. For charitably inclined retirees, QCD planning should often be considered before simply taking an RMD and later writing a personal check to charity.
Self-Employment Income Can Create Planning Opportunities in Retirement
Retirement doesn't always mean you stop working completely. Many retirees consult, teach, freelance, serve on boards, or operate small businesses. That self-employment income is taxable, and applicable net earnings can also be subject to self-employment taxes.
However, legitimate self-employment can create planning opportunities as well.
Depending on the business and applicable rules, ordinary and necessary business expenses may be deductible. A retiree with qualifying self-employment income may also have opportunities to contribute to a retirement plan such as a SEP IRA, SIMPLE IRA, or individual 401(k), depending on the circumstances and plan requirements.
For example, someone who retires from a corporate career but continues consulting may have more tax-planning options than someone who simply receives the same amount as additional IRA distributions.
The important point is that a retirement side business should be treated like a real business. Income needs to be reported, deductions need to be legitimate, and retirement-plan contributions must follow applicable rules.
Use Tax-Loss Harvesting in Your Brokerage Account
For retirees with taxable brokerage accounts, investment losses can also be valuable from a tax-planning perspective. Suppose you sell one investment during the year and realize a $20,000 capital gain. At the same time, another investment in the portfolio has declined and is sitting at a $15,000 unrealized loss.
If selling that investment also makes sense from an investment perspective, realizing the loss could help offset capital gains. This strategy is generally referred to as tax-loss harvesting.
Pay Attention to the Investments You Hold in Taxable Accounts
Asset location can also influence taxes in retirement. Mutual funds held in taxable brokerage accounts can sometimes distribute capital gains to shareholders. Those distributions can create taxable income even if you personally didn't sell your mutual-fund shares. That can be frustrating for a retiree who is carefully managing taxable income.
ETFs can often be more tax-efficient because of the way many ETF structures handle portfolio transactions, although ETFs can still make taxable capital-gain distributions. Individual securities can provide even more control over when gains and losses are realized, although owning individual stocks introduces other considerations such as diversification and investment risk.
The objective shouldn't be to select investments based solely on taxes. But when two investment solutions are otherwise appropriate, their tax efficiency can be an important consideration in a taxable brokerage account.
Medicare IRMAA Is a Tax-Planning Issue Even Though It Isn't a Tax
When we're helping retirees manage taxes, we also pay close attention to Medicare premiums.
Higher-income Medicare beneficiaries can pay additional amounts for Medicare Part B and Part D through the Income-Related Monthly Adjustment Amount, or IRMAA.
For 2026, the standard Part B premium applies when modified adjusted gross income is $109,000 or less for an individual or $218,000 or less for a married couple filing jointly.
Above those levels, income-related premiums begin.
For 2026, the Part B premium ranges from the standard $202.90 per month to as much as $689.90 per month for beneficiaries in the highest IRMAA tier. Part D can also carry an additional income-related adjustment.
For a married couple in which both spouses are on Medicare, crossing an IRMAA threshold can have a meaningful impact on annual healthcare costs.
Medicare Uses a Two-Year Lookback
One of the more frustrating parts of IRMAA is the timing. Medicare generally uses tax-return information from two years earlier to determine current-year income-related premiums. That means an income decision you make today may not show up in your Medicare premium until two years later.
Suppose you process a very large Roth conversion, realize a large capital gain, or take an unusually large IRA distribution. The tax bill is obvious. What is less obvious is that the additional income could also increase Medicare premiums later. This doesn't mean you should never cross an IRMAA threshold. Sometimes realizing additional income is still the correct long-term financial decision. But IRMAA should be treated as another cost in the calculation.
The Enhanced Senior Deduction and IRMAA Create More Retirement Income Thresholds
This is why retirement tax planning has become increasingly complex.
You may be trying to stay within a particular federal income-tax bracket.
At the same time, you may be monitoring the 0% long-term capital-gains threshold.
You could be trying to preserve some or all of the enhanced senior deduction.
You may also be watching Social Security taxation and an IRMAA threshold.
These different rules do not necessarily use exactly the same income calculations.
As a result, simply saying, “Stay in the 12% bracket,” isn't enough to create a comprehensive retirement tax strategy. You have to look at the entire return and the financial consequences outside the return.
Could Changing Your State of Domicile Reduce Retirement Taxes?
For retirees who are already considering relocating, state taxes can become another major planning opportunity. Consider someone who owns a home in New York and another home in Florida.
If that person genuinely intends to make Florida their permanent home, changing domicile could potentially change the state taxation of certain retirement and investment income because Florida does not impose an individual state income tax. But changing domicile is not as simple as saying, “I spent six months in Florida.”
Domicile generally refers to the place you consider your permanent home and intend to return to.
For New York taxpayers in particular, the rules require careful attention.
New York states that a person's New York domicile does not change until they can demonstrate that they abandoned the New York domicile and established a new domicile elsewhere. New York looks at the broader facts and circumstances of the individual's life.
Things such as where you actually live, the location of important personal connections, and other evidence of where you have established your permanent home can matter. Registering to vote or changing your driver's license can support the facts, but no single action necessarily determines domicile by itself.
State-Tax Planning Can Be Particularly Important Before Large Transactions
Suppose you are planning to move from a higher-tax state to a state without an individual income tax. You also intend to process a $500,000 Roth conversion. Doing the conversion immediately before establishing the new domicile could produce a very different state-tax result than doing it afterward. The same could potentially apply to large IRA distributions or certain investment income.
However, state sourcing rules can be complex, and not every type of income automatically escapes taxation simply because someone changes residency. This is an area where advance planning with a qualified tax professional can be particularly important.
The Best Retirement Tax Strategy Changes From Year to Year
One of the most important concepts to understand is that your tax strategy at age 62 may be completely different from your tax strategy at age 75. At 62, you may have no salary, no Social Security, and no RMDs. That could be an attractive Roth conversion or capital-gain harvesting year.
At 65, Medicare enters the picture. Once Social Security begins, you need to consider how other income affects taxation of your benefits.
At age 70½, QCDs become available.
At age 73 or 75, depending on your applicable RMD age, required minimum distributions may become a significant part of your taxable income.
The retirement tax plan should change as you move through those stages.
So, How Can You Reduce Taxes in Retirement?
The first step is to stop looking at your tax return one year at a time.
Retirement creates an opportunity to coordinate your traditional retirement accounts, Roth accounts, brokerage assets, Social Security, charitable giving, investment gains and losses, Medicare premiums, and potentially even your state of residence.
Sometimes reducing taxes means realizing more taxable income today.
You might intentionally take an IRA distribution while you are in a low tax bracket.
You might process a Roth conversion before RMDs begin.
You might realize a long-term capital gain while it qualifies for the 0% federal rate.
You might use a QCD rather than writing a personal check to charity.
Or you may realize investment losses to offset gains elsewhere in your portfolio.
The lowest tax bill this year isn't necessarily the best tax strategy.
The goal is to manage your income so that you are taking advantage of lower tax rates and planning opportunities throughout retirement while avoiding unnecessary taxes, Medicare costs, and large taxable distributions later in life.
That is why tax planning can become more important—not less important—after the paycheck stops.
About Michael……...
Hi, I’m Michael Ruger. I’m the managing partner of Greenbush Financial Group and the creator of the nationally recognized Money Smart Board blog . I created the blog because there are a lot of events in life that require important financial decisions. The goal is to help our readers avoid big financial missteps, discover financial solutions that they were not aware of, and to optimize their financial future.
Frequently Asked Questions About Reducing Taxes in Retirement
-
How can I legally reduce my taxes in retirement?Retirees may be able to reduce taxes through coordinated withdrawals from traditional IRAs, Roth accounts, and taxable brokerage accounts; Roth conversions; 0% long-term capital-gain harvesting; qualified charitable distributions; tax-loss harvesting; and advance RMD planning. The best strategy depends on both your current tax situation and the income you expect later in retirement.
-
What is the most tax-efficient way to withdraw money in retirement?There is no universal withdrawal order. A tax-efficient retirement withdrawal strategy often combines distributions from taxable brokerage accounts with strategic withdrawals from traditional retirement accounts while preserving Roth assets when appropriate. The objective is generally to manage tax brackets over your lifetime rather than completely emptying one account before using another.
-
How can retirees pay 0% tax on long-term capital gains?For 2026, the 0% federal long-term capital-gains bracket extends to $49,450 of taxable income for single filers and $98,900 for married couples filing jointly. Ordinary taxable income generally occupies the lower portion of the income stack first, with long-term capital gains layered on top. Only the portion of qualifying gains that remains within the 0% range receives the 0% federal rate.
-
How much of my Social Security is taxable in retirement?Depending on your combined income, none, up to 50%, or up to 85% of Social Security benefits may be included in taxable income for federal purposes. For single filers, the primary combined-income thresholds are $25,000 and $34,000. For married couples filing jointly, they are $32,000 and $44,000. An 85% taxable portion does not mean Social Security is taxed at an 85% tax rate.
-
What is the $6,000 tax deduction for seniors age 65 and older?For tax years 2025 through 2028, qualifying individuals age 65 and older may receive an enhanced federal deduction of up to $6,000 per person, or $12,000 for a married couple if both spouses qualify. The deduction begins phasing out when MAGI exceeds $75,000 for single filers or $150,000 for married couples filing jointly and is fully phased out above $175,000 and $250,000, respectively.
-
Can Roth conversions reduce taxes in retirement?Roth conversions can potentially reduce lifetime taxes when pre-tax retirement assets are converted during years when the taxpayer is in a relatively favorable tax bracket. Conversions can also reduce future pre-tax balances and RMDs. However, conversions create taxable income in the year they occur and can affect Social Security taxation, the enhanced senior deduction, Medicare IRMAA, and state income taxes.
-
How can I reduce taxes on required minimum distributions?Planning before RMDs begin can be important. Strategies may include taking intentional traditional IRA distributions during lower-income years, completing partial Roth conversions, and using qualified charitable distributions once eligible. Reducing the pre-tax account balance before RMD age can potentially reduce future required distributions, although the tax cost of implementing those strategies needs to be considered.
-
Do qualified charitable distributions reduce taxable income?A properly executed QCD allows an eligible IRA owner age 70 1/2 or older to send qualifying IRA assets directly to an eligible charitable organization. The qualifying distribution can generally be excluded from taxable income and can count toward an RMD once RMDs apply. A taxpayer cannot also claim a charitable deduction for the same QCD.
-
How can I avoid higher Medicare premiums in retirement?Medicare IRMAA is based on modified adjusted gross income and generally uses tax information from two years earlier. Managing the timing of Roth conversions, IRA distributions, capital gains, and other income may help retirees manage exposure to higher Part B and Part D premiums. However, avoiding IRMAA should not necessarily take priority over a tax strategy that produces greater long-term savings.
-
Should I move to a state with no income tax when I retire?State income taxes can be one factor when deciding where to live in retirement, particularly for retirees expecting substantial IRA distributions, Roth conversions, or investment income. However, taxes should be considered alongside housing costs, healthcare, family, lifestyle, and other financial factors. If changing domicile from a state such as New York, make sure the change is legitimate under the applicable residency and domicile rules before relying on the expected state-tax savings.




Should Your Investment Strategy Change when You Retire
Should your investment strategy change when you retire? Most people don’t realize how much the answer impacts taxes, income, and long-term security. Retirement isn’t the end of your financial planning—it’s the start of a new phase. Your goals shift from growth to income, and your investment strategy should evolve with them.
Retirement marks a major shift in your financial life: you move from saving and accumulating wealth to spending it. But does that mean your investment strategy should change the moment you stop working?
The answer isn’t a simple yes or no—it depends on your goals, income needs, and risk tolerance. Let’s explore what changes may be necessary, what can stay the same, and how to align your investment approach with the realities of retirement.
1. Accumulation vs. Distribution: A New Financial Phase
During your working years, your investment strategy likely focused on growth—maximizing returns over the long term. For most, in retirement, the focus shifts to income and moderate growth. Your portfolio now needs to:
Support monthly withdrawals
Last for 20–30+ years
Withstand market volatility without derailing your lifestyle
This shift doesn't mean abandoning growth altogether, but it does mean adjusting how you balance risk and reward.
2. Reassess Your Asset Allocation
One of the first things to review in retirement is your asset allocation—how your investments are divided among stocks, bonds, and cash.
A typical pre-retirement portfolio may be 70–100% in equities. But in retirement, many advisors recommend dialing that back to reduce risk.
Example:
If you have a $1 million portfolio:
A 60/40 allocation would mean $600,000 in diversified stock funds and $400,000 in bonds or other fixed-income assets.
A 40/60 allocation might suit someone who is more risk-averse or heavily reliant on portfolio withdrawals.
Mistake Alert:
Some retirees swing too far into conservative territory. While that may feel safe, inflation can quietly erode your purchasing power—especially over a 25- to 30-year retirement.
3. Add an Income Strategy
Now that you’re drawing from your investments, it’s essential to have a plan for generating reliable income and decreasing the level of volatility with your portfolio. This may include:
Dividend-paying stocks or ETFs
Bond holdings or short-term fixed income
The goal is to create stable cash flow while giving your growth assets time to recover from market dips.
4. Be Strategic With Withdrawals
Your withdrawal strategy has a major impact on taxes and portfolio longevity. The order you pull from different account types matters.
Example:
Let’s say you need $80,000/year from your portfolio. You might:
Take $40,000 from a taxable account (capital gains taxed at lower rates)
Pull $20,000 from a Traditional IRA (fully taxable as income)
Social Security $20,000 (up to 85% taxable)
This balanced approach spreads the tax burden, avoids pushing you into a higher bracket, and gives your Roth assets (if you have them) more time to grow.
Common Misstep:
Many retirees default to depleting all of their after-tax assets first, but by not taking withdrawals from their tax-deferred accounts, like Traditional IRAs and 401(k) accounts, they potentially miss out on realizing those taxable distributions at very low tax rates. Having a withdrawal plan that coordinates your social security, Medicare premiums, after-tax accounts, pre-tax accounts, and Roth accounts is key.
5. Stay Diversified—Reduce Volatility In Portfolio
Diversification and reducing volatility are key considerations when entering retirement years. When you take withdrawals from your retirement accounts, the investment returns can vary significantly from those of the accumulation years. Why is that?
When you were working and contributing to your retirement accounts, and the economy hit a recession, since you were not withdrawing any money from your accounts when the market rebounded, you likely regained those losses fairly quickly. But in retirement, when you are taking distributions from the account as the market is moving lower, there is less money in the account when the market begins to rally. As such, your rate of return is more significantly impacted by market volatility when you enter distribution mode.
To reduce volatility in your portfolio, you may need to:
Increase your level of diversification across various asset classes
Keep a large cash reserve on hand to avoid selling stocks in a downturn
Be more proactive about adjusting your investment allocation in response to changing market conditions
6. Don’t Forget About Growth
Retirement could last 30 years or more. That means your portfolio needs to outpace inflation, especially with rising healthcare and long-term care costs.
Even if you’re taking distributions, keeping 30–60% in equities may help ensure your money grows enough to support you in later decades.
Final Thoughts: Don’t “Set It and Forget It”
Your investment strategy should evolve with you. Retirement isn’t a one-time financial event—it’s a new chapter that requires ongoing planning and regular reviews.
About Michael……...
Hi, I’m Michael Ruger. I’m the managing partner of Greenbush Financial Group and the creator of the nationally recognized Money Smart Board blog . I created the blog because there are a lot of events in life that require important financial decisions. The goal is to help our readers avoid big financial missteps, discover financial solutions that they were not aware of, and to optimize their financial future.
Frequently Asked Questions (FAQs):
Should your investment strategy change when you retire?
While the focus shifts from accumulation to income and preservation, your investment approach should evolve based on your goals, risk tolerance, and income needs. Many retirees move toward a more balanced portfolio that supports sustainable withdrawals while still allowing for growth.
What’s the difference between the accumulation and distribution phases?
During the accumulation phase (your working years), the goal is to grow wealth through regular contributions and long-term compounding. In the distribution phase (retirement), you rely on your savings for income, so the emphasis shifts to generating steady cash flow and managing risk.
How should retirees adjust their asset allocation?
Many retirees move from aggressive stock-heavy portfolios to more balanced allocations—like 60/40 (stocks/bonds) or 40/60—depending on their comfort with risk. However, being too conservative can expose you to inflation risk, which can erode purchasing power over time.
How can you generate income from your investments in retirement?
Common income strategies include using dividend-paying stocks, bonds, or fixed-income funds to provide a steady cash flow. A well-structured income plan helps cover expenses while allowing growth-oriented investments to recover from market downturns.
What’s the best order to withdraw funds from retirement accounts?
Strategic withdrawals can help minimize taxes and extend portfolio longevity. The right order depends on your income, Social Security, and Medicare situation.
Why is diversification so important in retirement?
Diversification can reduce portfolio volatility—critical during retirement, when you’re withdrawing funds. Selling assets during a market downturn can permanently harm portfolio growth. Diversifying across asset classes and maintaining a cash buffer may help reduce the impact of market volatility.
Should retirees still invest in stocks?
In most cases, yes. Even in retirement, equities are important for long-term growth and inflation protection. With retirees living longer, it’s not uncommon for retirees to maintain investment accounts for 15+ years into retirement.
How often should retirees review their investment strategy?
At least once a year—or after major life or market changes. Retirement isn’t static, and your investment strategy should adjust to reflect evolving income needs, health costs, tax law updates, and market conditions.
What’s the most common mistake retirees make?
Becoming too conservative too soon. Avoiding market exposure entirely can limit growth and increase the risk of outliving your savings. A balanced approach that manages volatility while maintaining some growth potential is ideal in most situations.
