
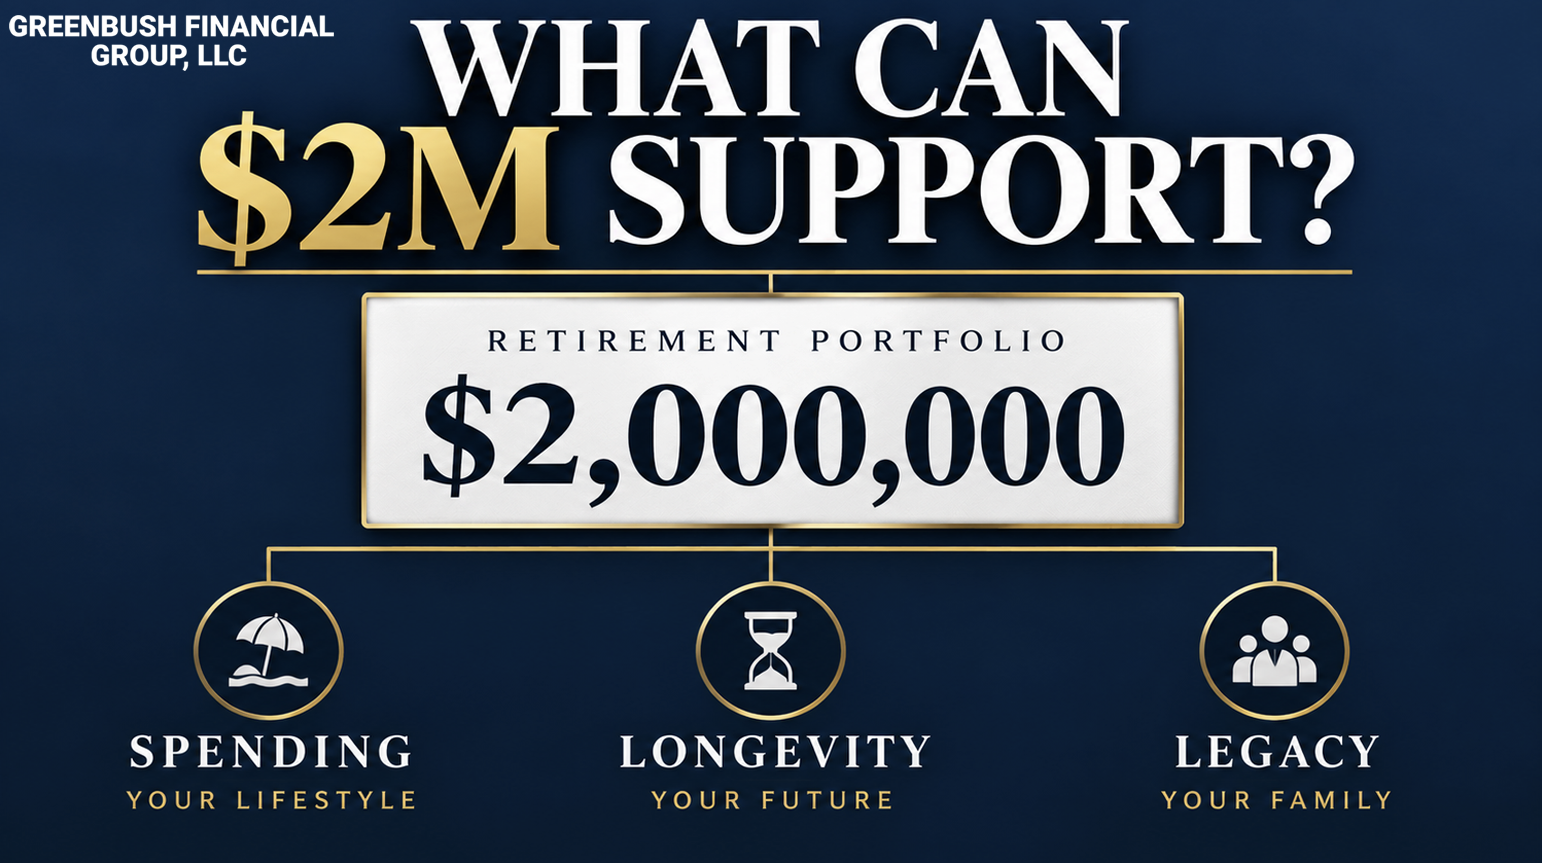
You’re Retired With $2 Million. Why Are You Still Afraid to Spend It?
Many retirees with $2 million or more still hesitate to spend after decades of saving. Learn how Social Security, taxes, healthcare, longevity, market risk, and legacy goals can help determine how much you can comfortably spend in retirement.
Many retirees with $2 million or more still hesitate to spend because they spent decades learning how to save. The solution is not simply spending more. It is determining how much your retirement plan can support after accounting for Social Security, taxes, market declines, longevity, healthcare, and legacy goals. Greenbush Financial Group helps retirees turn those variables into a practical “permission to spend” number.
Why Is Spending So Difficult After You Retire?
For 30 or 40 years, successful retirement savers are rewarded for accumulating money.
You contribute to the 401(k), invest extra cash, and avoid unnecessary withdrawals. Then you retire and suddenly you are supposed to reverse that behavior.
Even when you have $2 million saved, withdrawing $50,000 can feel like you are moving backward.
That feeling is understandable, but your investment balance alone does not determine whether you can afford to spend more.
A better question is:
What does your $2 million actually need to accomplish?
It may need to fund your lifestyle, taxes, healthcare, travel, future home repairs, a surviving spouse, and perhaps an inheritance for your children.
Once those goals are defined, you can determine how much of the portfolio is actually needed and how much represents a safety margin.
Start With Your Retirement Income Gap
The simplest starting point is to compare what comes in with what goes out.
Add up your expected annual spending and taxes, then subtract reliable income such as Social Security and pensions.
The remaining amount needs to come from your investments.
Example: Retired With $2 Million
Assume a retired couple has:
$2 million invested
$70,000 of annual Social Security
$120,000 of annual lifestyle spending
$15,000 of estimated taxes
Their total annual cash need is approximately $135,000.
After Social Security, they need about $65,000 per year from their portfolio.
That represents an initial withdrawal of approximately 3.25% of their $2 million portfolio.
That percentage does not automatically mean the spending is safe. But now we have a number that can be tested.
How Do You Create a “Permission to Spend” Number?
Your permission-to-spend number is the amount your retirement plan can reasonably support after accounting for the major risks you may face.
A simple starting calculation is:
Lifestyle spending + taxes + major planned expenses − Social Security and pension income = required portfolio withdrawals
Then stress-test that number.
Ask:
What if the market falls early in retirement?
What if one or both spouses live into their 90s?
Have healthcare and potential long-term care costs been considered?
What happens financially when the first spouse dies?
Are large home repairs or vehicle purchases included?
How much do you actually want to leave to your children?
If your desired spending continues to work under reasonable stress tests, you have stronger evidence that you can afford it.
What If the Market Drops?
One of the biggest risks is a major market decline early in retirement.
Suppose the couple's $2 million portfolio falls 20%, temporarily reducing it to approximately $1.6 million before accounting for withdrawals.
Their $65,000 withdrawal is no longer 3.25% of the portfolio. It is now approximately 4.1%.
That does not mean they immediately need to cancel every vacation.
It means their plan should have flexibility.
That could include maintaining a cash reserve, holding a diversified investment allocation, and identifying discretionary expenses that could temporarily be reduced during a prolonged market decline.
The important question is not whether the market will decline. It eventually will.
The question is whether your retirement plan can absorb it without requiring major permanent changes.
What If You Live Into Your 90s?
Longevity is another reason retirees hesitate to spend.
Instead of allowing “What if I live to 100?” to become a reason to never use your money, model longer life expectancies directly.
A retirement projection can test what happens if one or both spouses live to 90, 95, or beyond.
It should also account for what happens after the first spouse dies. Social Security income may decline, tax filing status may change, and the surviving spouse may still have many of the same household expenses.
If your spending works even with conservative longevity assumptions, that provides much more useful information than simply assuming you need to preserve every dollar.
Healthcare Should Be a Number, Not an Unlimited Unknown
Healthcare and long-term care are legitimate retirement risks.
But “I might need the money for healthcare someday” can become a reason to never spend anything.
Instead, quantify the risk as much as possible.
Consider:
Medicare premiums and supplemental coverage
Normal out-of-pocket healthcare costs
Existing long-term care insurance
HSA balances
Potential long-term care expenses
How much of those costs you intend to self-fund
You cannot know exactly what healthcare will cost decades from now. You can, however, build a reasonable reserve into the plan.
That allows healthcare to become a planning assumption rather than an undefined reason to avoid spending.
How Much of Your $2 Million Is Actually Surplus?
This is often the most important question.
Suppose your retirement analysis indicates that $1.5 million is reasonably needed to support your lifestyle and future risks under conservative assumptions.
That leaves approximately $500,000 of additional cushion.
It does not mean you should immediately spend $500,000.
It means those dollars may have a different purpose.
They could potentially fund:
More travel
Gifts to children or grandchildren
Home improvements
Charitable giving
Additional financial security
A larger inheritance
There is a major psychological difference between thinking, “I cannot touch my $2 million,” and understanding, “My plan requires approximately this much, and the rest is my safety margin.”
Do You Actually Want to Leave the Money to Your Children?
Many retirees say leaving money to their children is important.
The next question should be: How much?
There is a difference between intentionally planning to leave $500,000 and leaving $2 million because you were afraid to spend throughout retirement.
Neither outcome is necessarily wrong.
But your legacy should ideally be a goal, not an accident.
If your retirement projection shows a substantial estate remaining even under conservative assumptions, you may have a choice: leave more later, give some away during your lifetime, spend more on experiences today, or simply maintain a larger safety margin.
Don't Forget About Taxes
Where your $2 million is held matters.
A retiree with $2 million in traditional IRAs has a different spending and tax situation than someone with assets spread among traditional IRAs, Roth IRAs, taxable brokerage accounts, and cash.
Traditional IRA withdrawals can increase taxable income and potentially affect Medicare IRMAA premiums. Future required minimum distributions can also increase taxable income later in retirement.
This is why spending decisions should be coordinated with:
Roth conversions
Social Security
Capital gains
Required minimum distributions
Medicare
The surviving spouse's future tax situation
Sometimes spending or converting tax-deferred money earlier can be part of a longer-term tax strategy.
When Can You Reasonably Give Yourself Permission to Spend More?
You may have room to spend more when:
Social Security and pensions cover a meaningful portion of core expenses
Portfolio withdrawals remain reasonable under conservative assumptions
The plan can withstand a significant market decline
Longevity into the 90s has been tested
Healthcare and long-term care risks have been considered
Major future expenses are included
Survivor income and taxes have been modeled
Your desired legacy is already incorporated
You still maintain a meaningful safety margin
You may need to remain more cautious if your plan depends on strong investment returns, requires consistently large withdrawals, has little flexibility during bad markets, or does not account for major future expenses.
Common Mistakes Retirees Make
Some of the most common mistakes include:
Treating principal as money that can never be spent
Using a generic withdrawal percentage without looking at the household plan
Keeping an excessive healthcare reserve with no specific calculation behind it
Ignoring the surviving spouse's financial situation
Forgetting about taxes and future RMDs
Leaving a large inheritance by default instead of by choice
Waiting until health declines to begin using money for important experiences
Final Thoughts
If you have $2 million and are still afraid to spend, the answer is not simply to spend more.
The answer is to determine what your money needs to accomplish and test whether your desired lifestyle fits within those boundaries.
At Greenbush Financial Group, we look at retirement spending in the context of income, investments, taxes, market risk, longevity, healthcare, survivor needs, and legacy goals.
Here is what gives you reasonable permission to spend more: your desired spending continues to work under conservative assumptions and leaves an adequate safety margin.
Here is what tells you to remain cautious: your plan depends on strong markets, high withdrawals, or leaves little room for unexpected expenses.
Retirement savings are meant to provide financial security. But once that security has been established, some of those dollars may also be available to help you enjoy the retirement you spent decades saving for.
Rob Mangold
About Rob……...
Hi, I’m Rob Mangold. I’m the Chief Operating Officer at Greenbush Financial Group and a contributor to the Money Smart Board blog. We created the blog to provide strategies that will help our readers personally, professionally, and financially. Our blog is meant to be a resource. If there are questions that you need answered, please feel free to join in on the discussion or contact me directly.
Frequently Asked Questions
-
Is $2 million enough to retire?It can be. Whether $2 million is enough depends on your spending, Social Security and pension income, taxes, retirement age, healthcare costs, investments, longevity, and legacy goals.
-
How much can I spend each year with $2 million?Start by subtracting reliable income from your annual spending and taxes. The remaining portfolio withdrawal should then be tested against market declines, inflation, longevity, healthcare costs, and other financial goals.
-
Is a 4% withdrawal rate safe with $2 million?A 4% initial withdrawal equals $80,000 from a $2 million portfolio. Whether that is appropriate depends on your retirement timeline, investments, inflation, other income, taxes, and ability to adjust spending.
-
Should I be afraid to spend principal in retirement?Not necessarily. Retirement assets were generally accumulated to help fund retirement. The important question is whether withdrawals are sustainable within your overall financial plan.
-
How much should I leave my children?There is no standard amount. Establishing a specific legacy goal can help determine whether additional assets should be preserved, gifted during your lifetime, or available for your own retirement spending.

Your Spouse Dies First. What Happens to Your Retirement Plan?
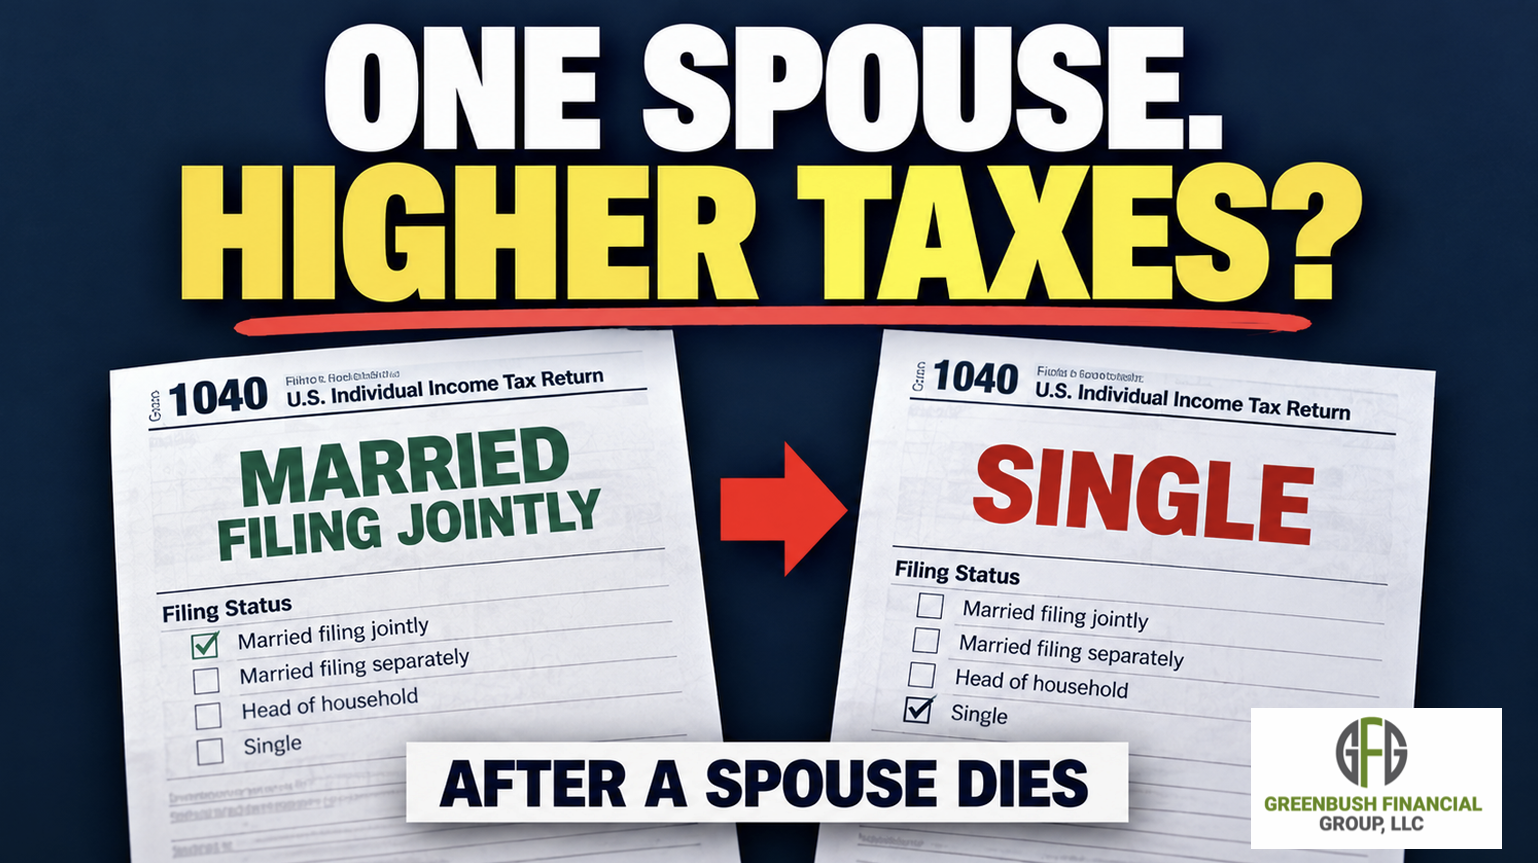
When one spouse dies, the surviving spouse’s retirement plan can change significantly. Social Security income may decrease, taxes and Medicare premiums can shift, and retirement accounts may need to be retitled or transferred. Planning ahead can make the financial transition easier to manage.
When one spouse dies, the surviving spouse's retirement plan can change significantly. One Social Security benefit generally disappears, tax filing status may eventually change, Medicare premiums can be affected, and retirement accounts may need to be retitled or transferred. At Greenbush Financial Group, we encourage couples to plan for this transition before it happens because the surviving spouse may have less income while facing many of the same household expenses.
What Happens Financially When One Spouse Dies?
Most retirement plans are built around two people.
There may be two Social Security checks, pension income, IRA withdrawals, investment income, and a household budget designed around both spouses.
When one spouse dies, the financial plan does not simply become half as large. Some expenses decline, but many do not. Property taxes, utilities, home maintenance, insurance, and other fixed expenses may remain relatively similar.
At the same time, household income can decline.
That combination is why every retirement plan should answer one important question:
Could either spouse understand and manage the retirement plan alone tomorrow?
If the answer is no, there is planning work to do.
What Happens to Social Security When a Spouse Dies?
For many retired couples, the first major income change involves Social Security.
If both spouses are receiving Social Security and one dies, the survivor generally does not continue receiving both full benefits. Instead, the survivor may be eligible for the higher benefit based on either their own record or the deceased spouse's record.
Social Security survivor benefits can range from 71.5% to 100% of the deceased spouse's benefit depending on factors including the survivor's age when benefits begin. A surviving spouse at survivor full retirement age can generally receive up to 100% of the deceased worker's benefit.
Example: Two Social Security Checks Become One
Assume a retired couple receives:
Spouse A: $3,500 per month
Spouse B: $2,000 per month
Combined Social Security: $5,500 per month
If Spouse A dies first and Spouse B qualifies for the full survivor benefit, Spouse B could receive approximately $3,500 per month rather than continuing to receive $5,500.
That is a $2,000 monthly reduction in household Social Security income, or $24,000 per year.
This is one reason the higher earner's Social Security claiming decision can be a household decision rather than simply an individual break-even calculation. Delaying the higher earner's benefit may potentially provide a larger benefit for the surviving spouse later.
The Survivor's Expenses May Not Fall as Much as Income
It is easy to assume that expenses will decline substantially when there is only one person in the household.
Some will. Food, travel, personal spending, and certain healthcare expenses may decrease.
But many costs remain:
Property taxes
Homeowners insurance
Utilities
Home maintenance
Vehicle expenses
Medicare premiums
Long-term care planning
Investment management and professional services
A retirement plan should therefore model both phases of retirement: retirement as a couple and retirement as a surviving spouse.
The Surviving Spouse May Face a Different Tax Situation
One of the most overlooked changes is the survivor's federal income tax filing status.
A surviving spouse can generally file a joint federal tax return with the deceased spouse for the year of death. Under certain circumstances involving a dependent child, qualifying surviving spouse status may also be available for the following two years. Otherwise, the survivor will generally move to single filing status.
That can create an unusual situation:
Household income may decline, but the survivor's tax rate on that income may increase.
A surviving spouse could still have substantial income from:
Social Security
Pensions
IRA distributions
Required minimum distributions
Interest and dividends
Capital gains
The difference is that much of this income may eventually be reported using the tax brackets and standard deduction applicable to a single taxpayer.
Key Insight
Couples sometimes focus heavily on minimizing taxes today without considering the survivor's future tax return.
For example, a couple entering retirement with large traditional IRA balances may want to evaluate whether Roth conversions during lower-income married years could reduce future taxable required distributions for the surviving spouse.
The goal is not necessarily to pay the least tax this year. It is to manage taxes over both spouses' lifetimes.
Medicare Premiums Can Change Too
Medicare Part B and Part D premiums can increase for higher-income beneficiaries through the Income-Related Monthly Adjustment Amount, commonly called IRMAA.
IRMAA is based on modified adjusted gross income, or MAGI, from a prior tax return, generally using income information from two years earlier.
After a spouse dies, two issues can arise.
First, the surviving spouse may eventually be subject to the lower IRMAA income thresholds that apply to a single taxpayer.
Second, Medicare premiums may initially be calculated using older income information that no longer reflects the survivor's financial circumstances.
The death of a spouse is considered a life-changing event for IRMAA purposes. If household income has declined, the survivor may be able to request that Social Security reconsider the Medicare premium adjustment, generally using Form SSA-44.
Important Note
Do not assume Medicare premiums will automatically reflect the survivor's new income immediately. This is an area that should be reviewed after a spouse dies.
What Happens to IRAs and Required Minimum Distributions?
Retirement accounts require special attention because the surviving spouse generally has more options than other beneficiaries.
Depending on the circumstances, a surviving spouse who inherits an IRA may be able to:
Treat the IRA as their own
Roll it into their own IRA
Keep the account as an inherited IRA
The appropriate decision can depend on the spouses' ages, whether required minimum distributions have begun, the survivor's need for income, and the tax consequences of each option.
If the deceased spouse had an RMD that was required but had not yet been taken for the year of death, that requirement also needs to be addressed. Future RMDs depend on how the surviving spouse handles the inherited account.
This matters because the surviving spouse could eventually own most or all of the couple's retirement assets while filing taxes as a single taxpayer.
That combination can make future RMDs particularly important to the tax plan.
What Happens to Joint Accounts, IRAs, and Other Assets?
Different assets transfer differently after death.
Joint accounts: Depending on how an account is titled and applicable state law, ownership may transfer directly to the surviving joint owner.
IRAs and retirement plans: These generally pass according to the beneficiary designation associated with the account. Retirement plans also have specific spousal protections and plan rules that can affect how benefits are paid.
Individual investment and bank accounts: Transfer depends on ownership, beneficiary designations such as transfer-on-death arrangements, and the estate plan.
Trust assets: Assets properly titled in a trust are generally administered according to the trust's terms.
This is why account titling and beneficiary designations should be coordinated with the estate plan rather than reviewed separately.
Beneficiaries Need to Be Correct Before Something Happens
Beneficiary forms are easy to overlook because they may have been completed decades earlier.
But retirement accounts generally pay according to the plan's beneficiary rules and designations. The IRS specifically recommends reviewing and updating retirement plan beneficiaries after major life events.
Couples should periodically review beneficiaries on:
IRAs
401(k)s and other employer retirement plans
Life insurance
Annuities
Transfer-on-death accounts
Other accounts with beneficiary designations
Do not assume that updating a will automatically updates these accounts.
What Happens to a Pension When a Spouse Dies?
Pensions can create another significant income change.
When pension payments begin, married retirees may have choices regarding survivor benefits. For example, a pension might offer a larger payment during the retiree's lifetime with no survivor benefit, or a smaller payment that continues partially or fully to the surviving spouse.
The election made at retirement can therefore have consequences many years later.
If a spouse receiving a pension dies, the survivor should contact the employer or plan administrator to determine what survivor benefit is available and how it will be paid.
Before choosing a pension option at retirement, couples should evaluate the decision alongside Social Security, life insurance, investment assets, longevity, and the survivor's expected income needs.
A Surviving-Spouse Retirement Example
Consider a retired couple with approximately $120,000 of annual household income:
$60,000 Social Security
$30,000 pension income
$30,000 IRA withdrawals
Total: $120,000
Now assume the husband dies first.
One Social Security benefit disappears, reducing Social Security income to approximately $40,000. Assume the pension has a 50% survivor benefit, reducing pension income from $30,000 to $15,000.
The surviving spouse now has:
$40,000 Social Security
$15,000 survivor pension
$30,000 IRA withdrawals
Total: $85,000
Household income has fallen by $35,000.
But her spending may not fall by $35,000.
She still has the house, property taxes, utilities, insurance, transportation, Medicare, and other fixed costs. Meanwhile, she may eventually file taxes as a single taxpayer and could inherit additional traditional IRA assets that create larger future RMDs.
Her retirement plan needs to be recalculated around her income, taxes, Medicare premiums, investments, and spending needs.
That is the transition couples should plan for in advance.
What Couples Should Organize Before Either Spouse Dies
Good survivor planning is not only about investment returns. It is also about making the financial household manageable for either spouse.
Before a crisis occurs, couples should organize:
Beneficiary designations: Confirm primary and contingent beneficiaries on retirement accounts, insurance policies, annuities, and applicable investment accounts.
Complete account list: Maintain an updated list of bank, brokerage, retirement, pension, insurance, credit, and other important accounts.
Access process: Make sure the surviving spouse knows how important financial information and password-management systems can be accessed securely.
Social Security information: Know what each spouse receives and what the approximate survivor benefit could be.
Pension information: Document pension elections and survivor benefits.
Insurance policies: Identify life insurance, long-term care insurance, annuities, and other relevant coverage.
Estate documents: Keep wills, trusts, powers of attorney, healthcare documents, and related records current.
Key contacts: Maintain contact information for the financial advisor, CPA, estate attorney, insurance professionals, pension administrator, and other important professionals.
Document location: Both spouses should know where important financial and estate documents are stored.
Survivor income plan: Estimate what income, taxes, Medicare costs, RMDs, and spending would look like if either spouse died first.
Common Survivor Planning Mistakes
Several mistakes can make an already difficult transition harder:
Assuming both Social Security checks continue
Planning taxes only while married
Ignoring the survivor's future RMD exposure
Choosing a pension option without analyzing survivor income
Failing to update beneficiaries
Assuming a will controls every financial account
Keeping financial information with only one spouse
Failing to review Medicare IRMAA after household income changes
Building a retirement plan that works only while both spouses are alive
Final Thoughts
A strong retirement plan should work for two people, but it should also work when there is only one.
The death of a spouse can change Social Security income, pension benefits, tax filing status, Medicare premiums, account ownership, beneficiary decisions, and future required withdrawals. These issues are interconnected, which is why survivor planning should be completed before a crisis occurs.
At Greenbush Financial Group, one of the most useful questions we can ask couples is simple:
Could either spouse understand and manage the retirement plan alone tomorrow?
If not, organizing the plan today can make the financial transition considerably easier for the surviving spouse.
Rob Mangold
About Rob……...
Hi, I’m Rob Mangold. I’m the Chief Operating Officer at Greenbush Financial Group and a contributor to the Money Smart Board blog. We created the blog to provide strategies that will help our readers personally, professionally, and financially. Our blog is meant to be a resource. If there are questions that you need answered, please feel free to join in on the discussion or contact me directly.
Frequently Asked Questions
-
Does a surviving spouse get both Social Security benefits?Generally, no. If the survivor is eligible for their own Social Security benefit and a higher survivor benefit, Social Security generally pays an amount equal to the higher applicable benefit rather than adding both full benefits together.
-
Can a surviving spouse file taxes jointly?A surviving spouse can generally file a joint federal income tax return for the year in which the spouse died. After that, filing status depends on the survivor's circumstances.
-
Can a spouse roll an inherited IRA into their own IRA?In many situations, yes. A surviving spouse has special options and may be able to treat an inherited IRA as their own or roll it into their own IRA. The best choice depends on factors including age, RMD requirements, and tax planning.
-
What happens to RMDs after a spouse dies?If an RMD was required for the deceased account owner in the year of death and had not been completed, it generally still must be taken. Future RMD requirements depend on the type of account, the survivor's status as beneficiary, and how the inherited account is handled.
-
Can a spouse's death affect Medicare premiums?Yes. A change in income and filing status can affect IRMAA for Medicare Part B and Part D. Death of a spouse is also an eligible life-changing event that may allow a survivor to request a reduction in IRMAA when prior income no longer reflects current circumstances.
-
Does a surviving spouse automatically receive the deceased spouse's pension?Not necessarily. The amount depends on the pension plan and the survivor option elected. The surviving spouse should contact the pension plan administrator to determine the benefits available.
Can You Afford to Retire at Age 60?
Can you afford to retire at age 60? Learn how healthcare costs, Social Security, taxes, inflation, income sources, and retirement withdrawals can impact your ability to retire before Medicare begins.
By Michael Ruger, CFP®
Partner and Chief Investment Officer at Greenbush Financial Group
Retiring at age 60 sounds pretty good.
You have reached a point where you may have accumulated significant savings in your 401(k), IRA, brokerage accounts, and other investments. Your mortgage may be paid down or close to being paid off. The kids may be out of the house. After working for several decades, you may finally be ready to spend more time traveling, pursuing hobbies, visiting family, or simply enjoying a schedule that isn't dictated by work.
But can you actually afford to retire at age 60?
The answer is going to be different for every household. Retiring at 60 can absolutely be achievable, but retiring before age 65 typically requires some additional planning. One of the biggest reasons is healthcare. Most people do not become eligible for Medicare based solely on age until 65, which potentially leaves a five-year period during which you need another source of health insurance.
At the same time, Social Security retirement benefits cannot generally begin until age 62, and claiming at 62 permanently reduces your monthly benefit compared with waiting until your full retirement age. For people born in 1960 or later, full retirement age is 67.
This creates what we might call the age-60 retirement bridge.
If you retire at 60, you need a plan for getting from age 60 to Medicare at 65, a strategy for when to begin Social Security, and enough income and investments to support your lifestyle potentially for several decades.
When evaluating whether you can afford to retire at 60, some of the most important questions include:
How will you obtain health insurance between age 60 and Medicare eligibility?
What will your annual after-tax expenses be?
How will inflation impact those expenses over a potentially long retirement?
When should you claim Social Security?
What pensions, part-time income, or other income sources will you have?
How much will you need to withdraw from your retirement accounts?
How will taxes impact the amount you actually have available to spend?
Let's walk through each of these areas.
Healthcare May Be the Biggest Challenge When Retiring at 60
For many people who want to retire at age 60, healthcare is one of the first issues we address in the financial plan.
Medicare generally becomes available at age 65 for people who qualify based on age. That means someone retiring at 60 could potentially have approximately five years in which they need another source of health insurance.
Those five years matter.
If health insurance costs $1,000 or more per month, that expense can significantly change the amount you need to withdraw from your retirement accounts. It can also affect your tax planning because the income you recognize during those years may influence the financial assistance available for certain Marketplace plans. Fortunately, there are several potential health insurance options for early retirees.
Option #1: Health Insurance Through Your Spouse's Employer
One of the simplest situations occurs when one spouse retires at 60 while the other spouse continues working. The retiring spouse may be able to obtain health insurance through the working spouse's employer-sponsored plan. Losing other health coverage can provide a special enrollment opportunity for an employer's group health plan, subject to applicable enrollment rules and deadlines.
However, don't assume the cost will be the same as what the working spouse is currently paying.
An employer might heavily subsidize coverage for its employees but provide a smaller subsidy for spouses or other dependents. Adding a spouse could therefore increase the monthly premium substantially. Before submitting your retirement paperwork, ask the working spouse's employer for the actual cost of family or employee-plus-spouse coverage. Also review deductibles, copays, provider networks, prescription coverage, and out-of-pocket maximums.
If adding the retiring spouse costs an additional $800 per month, for example, that represents $9,600 of additional annual expenses that should be included in the retirement plan.
Option #2: Retiree Health Insurance Through Your Former Employer
For someone retiring before 65, employer-sponsored retiree health coverage can be extremely valuable.
Although not every employer offers it, some organizations provide healthcare benefits to eligible retirees after they leave employment. Depending on the plan, coverage might continue until the retiree becomes eligible for Medicare, or benefits could continue in some form beyond age 65.
The important point is that retiree health plans vary significantly. One employer may subsidize most of the premium. Another may require retirees to pay a significant portion of the cost. Plans can also differ in deductibles, networks, prescription coverage, dependent coverage, and what happens once the retiree becomes eligible for Medicare.
If retiree health insurance is available to you, request the plan documents before you select a retirement date. You want to know exactly what you will pay, how premiums can change, whether your spouse is covered, and what happens at age 65. Those numbers should then be incorporated directly into your retirement projections.
Option #3: COBRA Coverage
COBRA can provide another potential bridge for someone leaving an employer before becoming eligible for Medicare. Under federal COBRA rules, eligible employees who retire or otherwise leave employment can generally continue their employer-sponsored health insurance for up to 18 months following the qualifying event. Certain circumstances can result in longer continuation periods.
The advantage is continuity. You can generally keep the same coverage you had immediately before leaving the employer. The disadvantage can be the cost.
While you were working, your employer may have been paying a significant portion of your health insurance premium without you really thinking about it. With COBRA, you generally become responsible for the full premium—the employee portion and the portion previously paid by your employer—plus a potential 2% administrative fee. That can make COBRA surprisingly expensive.
However, COBRA may still be a useful planning tool for someone retiring closer to age 65.
For example, someone retiring at age 63½ may be able to use COBRA to help bridge much or all of the period until Medicare eligibility. Someone retiring at exactly 60, on the other hand, generally cannot rely on the standard 18-month COBRA period to cover the entire five-year gap. That individual will likely need another healthcare solution after COBRA ends.
Option #4: Health Insurance Through the Marketplace
If you retire at 60 and don't have access to a spouse's employer plan or retiree health insurance—and COBRA isn't appropriate for the entire period—you may need to purchase individual health insurance through the Health Insurance Marketplace or an applicable state marketplace.
This is where retirement planning and tax planning can become closely connected. Marketplace premium tax credits can reduce the cost of coverage for qualifying households, and eligibility and the amount of the credit depend in part on household information and estimated income.
That means your retirement income strategy could potentially influence your health insurance costs.
For example, imagine you retire at 60 with substantial balances in a traditional IRA and a taxable brokerage account. The amount and type of income you recognize during the year could affect your eligibility for Marketplace financial assistance. This is one reason we don't look at healthcare planning, tax planning, and investment withdrawal strategies as three completely separate decisions. For an early retiree, they can interact with one another.
Depending on your location, age, household, income, and plan selection, unsubsidized Marketplace premiums can also be substantial. Instead of estimating the cost, research the plans available to you and incorporate realistic premiums, deductibles, and potential out-of-pocket costs into your financial plan.
Don't Just Budget for the Health Insurance Premium
Another mistake is looking only at the monthly premium. Your actual healthcare budget may include premiums, deductibles, copays, prescription expenses, dental care, vision care, and other out-of-pocket medical costs. Suppose you estimate that your health insurance premium will cost $12,000 per year. If you build your retirement projection using only that number, you may be understating your actual healthcare spending.
This is particularly important for someone retiring at age 60 because healthcare expenses don't disappear once Medicare begins at 65. The structure of the costs changes, but Medicare itself does not necessarily mean healthcare becomes free.
A good retirement projection should therefore model healthcare expenses both before and after age 65.
How Much Will You Spend If You Retire at 60?
Once healthcare is addressed, the next step is building a detailed retirement budget. We generally want to go line by line. That means looking at property taxes, mortgage payments, homeowners insurance, utilities, groceries, car payments, auto insurance, home maintenance, travel, entertainment, gifts, subscriptions, healthcare, and other recurring expenses.
This can be particularly important for someone retiring at 60 because some expenses that might disappear later in retirement may still exist. You might still have a mortgage. You could still be financially helping children. You may be replacing vehicles. Perhaps you plan to travel extensively during the first decade of retirement because you finally have the time to do it.
Rather than assuming you will spend 70% or 80% of your pre-retirement income, build the budget around the life you actually expect to live.
Inflation Has an Even Bigger Impact When You Retire Early
If you retire at 60, your retirement could potentially last 30 years or longer. That makes inflation an important variable.
For illustration, assume your household needs $80,000 per year after taxes at age 60 and we use a 3% annual inflation assumption.
Ten years later, you would need approximately $107,500 per year to maintain the purchasing power of that original $80,000.
Twenty years later, at age 80, you would need approximately $144,500 per year. That doesn't necessarily mean your lifestyle became more expensive. It means that, using our hypothetical 3% assumption, the same goods and services gradually cost more. Of course, inflation doesn't increase by exactly 3% every year. Some years it will be higher and some years lower. We are simply using 3% as a long-term financial planning assumption to illustrate how purchasing power can change.
The earlier you retire, the more years inflation potentially has to impact your expenses.
Social Security Creates Another Gap at Age 60
Another important consideration is that Social Security retirement benefits generally cannot begin at age 60. The earliest age most individuals can begin Social Security retirement benefits is 62. However, filing at 62 means accepting a permanently reduced monthly benefit compared with waiting until full retirement age. For individuals born in 1960 or later, claiming at 62 can reduce the monthly retirement benefit by as much as 30% compared with the benefit available at full retirement age of 67.
This creates another planning decision. If you retire at 60, should you begin Social Security immediately at 62? Or should you use your retirement assets to fund your lifestyle for a few additional years and allow your Social Security benefit to grow?
There isn't one answer that works for everyone.
Your health, life expectancy, marital status, other income sources, investment assets, taxes, and overall retirement strategy can all factor into the decision. The important point is that your retirement date and your Social Security filing date do not have to be the same. You can retire at 60 and potentially wait until 62, 67, or later to begin Social Security. Your financial plan should model those different scenarios so you can understand the tradeoffs.
Retiring at 60 Could Also Affect Your Social Security Benefit
There is another Social Security consideration that can be easy to overlook.
Social Security retirement benefits are calculated using your highest 35 years of earnings. If you stop working at 60 and have fewer than 35 years of earnings, years with no earnings can reduce your benefit calculation. Even if you already have 35 years of earnings, continuing to work could potentially replace lower-earning years with higher-earning years.
For many people with long careers, this may not dramatically change the retirement decision. But it is worth checking your individual Social Security earnings record and projected benefit before selecting a retirement date.
Identify All of Your Income Sources
Once we know what you expect to spend, we can begin identifying the income available to pay those expenses.
If you have a pension, when does it begin?
Can it begin at 60, or is there a reduction for starting it early?
Does the pension have a cost-of-living adjustment?
When will Social Security begin?
Do you expect rental income or income from another source?
Do you plan to work part-time?
Part-time work can be particularly helpful for someone retiring at 60. You may be finished with your primary career but still enjoy consulting, teaching, seasonal employment, or another flexible job. If you earn $20,000 or $30,000 per year for the first five years of retirement, that is money you potentially don't have to withdraw from your investments.
That can reduce pressure on the portfolio during the early years of retirement.
Your Investments Have to Cover Whatever Your Other Income Doesn't
Once your annual expenses and recurring income sources have been identified, we can determine how much needs to come from your assets.
Those assets could include:
401(k) and 403(b) accounts
457 plans
Traditional IRAs
Roth IRAs
Taxable brokerage accounts
Cash and savings
Other investment assets
Imagine that you need $100,000 of gross annual income to support your spending and taxes.
Perhaps a pension provides $30,000 and part-time work provides another $20,000.
That leaves approximately $50,000 that needs to come from your investment portfolio.
When the part-time work eventually ends, the amount required from the portfolio may increase. When Social Security eventually begins, the amount required from the portfolio may decrease again. This illustrates why early-retirement planning isn't as simple as dividing your investment balance by your annual expenses.
Your income needs can change significantly from year to year. A detailed financial plan can map those changes across the different phases of retirement.
Don't Forget About Taxes When Retiring at 60
Taxes are another major consideration.
Let's say you expect to spend $70,000 per year in retirement.
That is generally $70,000 after taxes because your mortgage company, grocery store, utility company, and airline don't care what your gross income was. They care whether you have enough cash available to pay the bill. If much of your retirement money is held in traditional 401(k)s and IRAs, withdrawals generally create taxable income. Pension income can also be taxable, and depending on your overall income, a portion of your Social Security benefits may eventually be subject to federal income tax.
As a result, you might need $80,000, $85,000, or some other amount of gross income to produce $70,000 of after-tax cash flow. The actual number depends on your individual tax situation. State taxes matter as well.
Different states have different rules regarding pension income, Social Security, and distributions from retirement accounts. If you are planning to move after retirement, the tax rules in your future state of residence may also need to be considered.
The Years Between 60 and 65 Can Create Tax-Planning Opportunities
There can also be opportunities associated with retiring early. For some retirees, the years immediately following retirement represent a period in which taxable income is lower than it was during their working years.
You might have stopped receiving a salary but have not yet begun Social Security. Required distributions from certain retirement accounts may also be years away. Depending on your circumstances, that period could create opportunities to evaluate strategies such as Roth conversions or realizing income at potentially lower tax rates.
However, those decisions should not be made in isolation.
For example, increasing taxable income through a Roth conversion could potentially affect Marketplace health insurance subsidies. A strategy that looks attractive strictly from an income-tax perspective could have a different result once healthcare costs are considered. This is another reason comprehensive planning can be particularly valuable between ages 60 and 65.
Can Your Portfolio Survive a Long Retirement?
Someone retiring at 60 also needs to consider longevity. If you retire at 60 and live to age 90, your investments need to support a 30-year retirement.
Live to 95, and you're looking at 35 years.
That doesn't mean you shouldn't retire early. It means the plan should be stress-tested over a sufficiently long period. It is also important to consider what happens if investment markets decline shortly after you retire. Taking large withdrawals while the portfolio is temporarily down can create additional challenges because you may have to sell more investments to generate the same amount of cash. A retirement plan should therefore evaluate not only whether the numbers work under an average set of assumptions, but also what happens when conditions aren't ideal.
A Hypothetical Age-60 Retirement Example
Consider a married couple, John and Lisa, who are both age 60.
They estimate that they need $80,000 per year after taxes to support their desired lifestyle. Lisa plans to continue working until age 65, while John would like to retire now.
John can join Lisa's employer health insurance plan, but doing so will increase their premiums by $9,000 per year.
John has a pension available immediately, and Lisa will eventually receive Social Security. They also have 401(k)s, IRAs, Roth IRAs, and a brokerage account.
Instead of simply asking whether their investment balance is “enough,” we would want to map out their cash flow year by year.
From 60 to 62, their income sources may look one way.
At 62, Social Security becomes available, although they may decide not to claim it yet.
At 65, Medicare changes the healthcare equation.
At 67, they reach full retirement age for Social Security if they were born in 1960 or later.
Later in retirement, additional tax and retirement-account considerations may arise.
The financial picture changes repeatedly. That is why a detailed retirement projection can provide far more useful information than a generic rule saying you need $1 million, $2 million, or some other arbitrary amount to retire at 60.
So, Can You Afford to Retire at Age 60?
You may be able to. Retiring at 60 can be a great option for individuals who have accumulated sufficient assets and have a clear plan for the additional variables that come with early retirement. The biggest hurdle is often healthcare coverage between retirement and Medicare eligibility at 65. But that is only one part of the analysis.
You also need to understand your annual expenses, account for inflation, determine your Social Security filing strategy, identify pensions and other income sources, estimate how much needs to be withdrawn from your investments, and account for federal and state taxes.
Retiring five or seven years earlier than the traditional retirement age gives you more years to enjoy retirement—but it also means your assets may need to support you for more years. The goal of financial planning isn't necessarily to determine whether you can retire at 60 based on one investment balance.
The better question is whether your combination of income, investments, healthcare coverage, taxes, and Social Security strategy can sustainably support the lifestyle you want throughout retirement. If the answer is yes, retiring at age 60 may be a very viable option.
About Michael……...
Hi, I’m Michael Ruger. I’m the managing partner of Greenbush Financial Group and the creator of the nationally recognized Money Smart Board blog . I created the blog because there are a lot of events in life that require important financial decisions. The goal is to help our readers avoid big financial missteps, discover financial solutions that they were not aware of, and to optimize their financial future.
Frequently Asked Questions About Retiring at Age 60
-
Can I afford to retire at age 60?Whether you can afford to retire at 60 depends on your annual expenses, retirement savings, healthcare costs, pensions, Social Security strategy, taxes, and other income sources. Because Medicare generally does not begin based on age until 65 and Social Security retirement benefits generally cannot begin until 62, someone retiring at 60 needs a plan to bridge those gaps. A detailed retirement projection can help determine whether your assets are sufficient to support your desired lifestyle over a potentially 30-year or longer retirement.
-
How much money do I need to retire at 60?There is no single amount you need to retire at 60. Someone with a pension, low expenses, and retiree health insurance may need substantially less than someone with no pension, high expenses, and expensive private health insurance. Instead of targeting an arbitrary amount such as $1 million or $2 million, calculate the difference between your expected after-tax spending and the recurring income available to support it.
-
How can I get health insurance if I retire at 60?Potential health insurance options for someone retiring at 60 include coverage through a working spouse's employer, retiree health insurance from a former employer, COBRA continuation coverage, and individual coverage through the Health Insurance Marketplace or an applicable state marketplace. Costs and coverage vary substantially, so healthcare should be researched before selecting your retirement date.
-
Can I use COBRA until Medicare starts at 65?It depends on your age when you retire and your eligibility. Following termination or retirement, federal COBRA continuation coverage is generally available for up to 18 months, although certain circumstances can extend coverage. Someone retiring at 63 1/2 might potentially use an 18-month COBRA period to bridge much of the gap to Medicare, while someone retiring at 60 would generally need another solution before reaching 65.
-
Can I collect Social Security if I retire at age 60?Retiring from your job and claiming Social Security are two separate decisions. Social Security retirement benefits generally cannot begin until age 62. You can retire at 60 and use pensions, savings, investments, or other income for several years before beginning Social Security. Waiting beyond age 62 can result in a larger monthly benefit than claiming at the earliest possible age.
-
Should I take Social Security at 62 if I retire at 60?Not necessarily. Claiming at 62 provides income sooner, but your monthly benefit is permanently reduced compared with waiting until full retirement age. For people born in 1960 or later, claiming at 62 can result in a benefit up to 30% lower than the full-retirement-age amount. Your life expectancy, marital situation, investments, tax situation, and other income sources should be considered when evaluating your Social Security filing strategy.
-
How much does health insurance cost if I retire before 65?The cost can vary significantly based on the type of coverage, location, age, household size, income, plan selection, and whether an employer subsidizes any portion of the premium. Early retirees should consider not only premiums but also deductibles, copays, prescriptions, and maximum out-of-pocket costs. If using Marketplace insurance, household income can also affect eligibility for premium tax credits.
-
What expenses should I include when planning to retire at 60?Your retirement budget should include housing, property taxes, mortgage payments, utilities, food, transportation, insurance, healthcare, travel, entertainment, home repairs, vehicle replacement, gifts, and other recurring or periodic expenses. Because someone retiring at 60 may still have a mortgage or other costs that disappear later, it is helpful to build a year-by-year projection rather than assuming expenses remain unchanged throughout retirement.
-
What are the biggest risks of retiring at 60?Important financial risks include unexpectedly high healthcare costs, inflation, a longer-than-expected lifespan, poor investment returns early in retirement, higher spending, and withdrawing too much from investments during the first several years. Retiring at 60 also means your portfolio may need to support you longer than if you retired at 65 or 67. Modeling different scenarios can help determine how resilient your retirement plan may be.
-
What should I do before retiring at age 60?Before retiring at 60, build a detailed after-tax retirement budget, determine your health insurance strategy through age 65, review your Social Security options, identify pensions and other income sources, estimate taxes, and determine how much you will need to withdraw from your investments each year. It can also be helpful to test the plan under different assumptions for inflation, investment returns, healthcare costs, and longevity. The objective is to determine whether your entire financial picture-not simply your current retirement account balance-can support the lifestyle you want for the rest of retirement.





Retirement Tax Traps and Penalties: 5 Gotchas That Catch People Off Guard
Even the most disciplined retirees can be caught off guard by hidden tax traps and penalties. Our analysis highlights five of the biggest “retirement gotchas” — including Social Security taxes, Medicare IRMAA surcharges, RMD penalties, the widow’s penalty, and state-level tax surprises. Learn how to anticipate these costs and plan smarter to preserve more of your retirement income.
Even the most disciplined savers can be blindsided in retirement by unexpected taxes, penalties, and benefit reductions that derail a carefully built plan. These “retirement gotchas” often appear subtle during your working years but can cost tens of thousands once you stop earning a paycheck.
Here are five of the biggest surprises retirees face—and how to avoid them before it’s too late.
1. The Tax Torpedo from Social Security
Many retirees are surprised to learn that Social Security isn’t always tax-free. Depending on your income, up to 85% of your benefit can be taxed.
The IRS uses something called “provisional income,” which includes half your Social Security benefit plus all other taxable income and tax-free municipal bond interest.
For individuals, taxes begin when provisional income exceeds $25,000.
For married couples, it starts at $32,000.
A well-intentioned IRA withdrawal or capital gain can push you over these thresholds—causing a sudden jump in taxes. Strategic Roth conversions and careful withdrawal sequencing can help smooth this out over time.
2. Higher Medicare Premiums (IRMAA)
The Income-Related Monthly Adjustment Amount (IRMAA) is one of the most overlooked retirement costs. Once your modified adjusted gross income (MAGI) exceeds certain limits, your Medicare Part B and D premiums increase—often by thousands of dollars per year.
For 2025, IRMAA surcharges begin when MAGI exceeds roughly $103,000 for single filers or $206,000 for married couples. The catch? Medicare looks back two years at your income. A Roth conversion, property sale, or large one-time distribution can unexpectedly trigger higher premiums two years later.
Proactive tax planning can prevent crossing these thresholds unintentionally.
3. Required Minimum Distributions (RMDs)
Once you reach age 73, the IRS requires you to start withdrawing from pre-tax retirement accounts each year—whether you need the money or not. These RMDs are taxed as ordinary income and can increase your tax bracket, raise Medicare premiums, and reduce your eligibility for certain deductions.
The biggest mistake is waiting until your 70s to plan for them. Roth conversions in your 60s can reduce future RMDs, and charitable giving through Qualified Charitable Distributions (QCDs) can offset the tax impact once they begin.
4. The Widow’s Penalty
When one spouse passes away, the surviving spouse’s tax brackets and standard deduction are cut in half—but income sources often don’t decrease proportionally. Social Security may drop by one benefit, but RMDs, pensions, and investment income remain largely the same.
The result is a higher effective tax rate for the survivor. This “widow’s penalty” can last for years, especially when combined with RMDs and Medicare surcharges. Couples can reduce the long-term impact through lifetime Roth conversions, strategic asset titling, and beneficiary planning.
5. State Taxes and Hidden Relocation Costs
Many retirees move to lower-tax states hoping to stretch their income, but state-level taxes can be tricky. Some states tax pension and IRA withdrawals, others tax Social Security, and a few impose taxes on out-of-state income or estates.
Additionally, higher property taxes, insurance premiums, and healthcare costs can offset income tax savings. A comprehensive cost-of-living comparison is essential before relocating.
Our analysis at Greenbush Financial Group often reveals that the “best” retirement state depends more on quality of life, healthcare access and total cost of living than on income tax rates alone.
How to Avoid These Retirement Surprises
Most retirement gotchas come down to timing and coordination—especially between taxes, Social Security, and healthcare. A few key steps can make a major difference:
Run retirement income projections that include taxes and IRMAA thresholds.
Consider partial Roth conversions before RMD age.
Sequence withdrawals intentionally between taxable, tax-deferred, and Roth accounts.
Evaluate the long-term impact of home state taxes before moving.
Review beneficiary and trust structures regularly.
The earlier you identify potential traps, the easier they are to fix while you still control your income and withdrawals.
The Bottom Line
Retirement is more complex than simply replacing a paycheck. The interplay between taxes, healthcare, and income sources can turn small decisions into costly mistakes. By spotting these gotchas early, you can preserve more of your wealth and enjoy a smoother, more predictable retirement.
Our advisors at Greenbush Financial Group can help you identify your biggest risk areas and design a plan to minimize the tax and income surprises most retirees never see coming.
FAQs: Retirement Planning Surprises
Q: Are Social Security benefits always taxed?
A: No. But depending on your income, up to 85% of your benefits may be taxable.
Q: How can I avoid higher Medicare premiums?
A: Manage your income below IRMAA thresholds through strategic Roth conversions and tax-efficient withdrawals.
Q: What happens if I miss an RMD?
A: You could face a 25% penalty on the amount not withdrawn, reduced to 10% if corrected quickly.
Q: Why do widows and widowers pay more in taxes?
A: Filing status changes from joint to single, cutting brackets and deductions in half while much of the income remains.
Q: Are all retirement states tax-friendly?
A: No. Some states tax retirement income or have higher overall costs despite no income tax.
Rob Mangold
About Rob……...
Hi, I’m Rob Mangold. I’m the Chief Operating Officer at Greenbush Financial Group and a contributor to the Money Smart Board blog. We created the blog to provide strategies that will help our readers personally, professionally, and financially. Our blog is meant to be a resource. If there are questions that you need answered, please feel free to join in on the discussion or contact me directly.
Social Security Cost of Living Increase Only 2.8% for 2026
The Social Security Administration announced a 2.8% cost-of-living adjustment (COLA) for 2026, slightly higher than 2025’s 2.5% increase but still below the long-term average. This modest rise may not keep pace with the real cost of living, as retirees continue to face rising prices for essentials like food, utilities, and healthcare. Learn how this affects your benefits, why COLA timing matters, and strategies to help offset inflation in retirement.
By Michael Ruger, CFP®
Partner and Chief Investment Officer at Greenbush Financial Group
The Social Security Administration (SSA) has announced that the annual Cost-of-Living Adjustment (COLA) for 2026 will be 2.8%, up slightly from 2.5% in 2025, but still below the ten-year average of about 3.1%. While any increase in Social Security benefits is welcome news for retirees, many experts and retirees alike worry that this modest adjustment may not be enough to keep pace with rising living costs.
In this article, we’ll cover:
How the 2026 COLA compares to previous years
Why this year’s increase may not keep up with inflation
The lag retirees face when inflation heats up
Possible strategies to help offset higher costs
The 2026 COLA: Modest in Historical Context
While the 2.8% increase may seem like a fair bump, it’s actually on the lower end of recent COLA adjustments. Here’s a look at the last five years of Social Security COLAs:
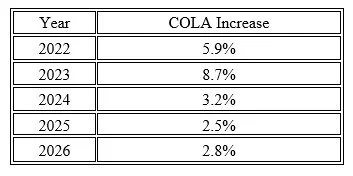
As the table shows, retirees experienced significant boosts during the high-inflation years of 2022 and 2023, but those increases have tapered off as inflation cooled — at least according to official data. However, many households continue to feel that everyday prices for groceries, utilities, and especially healthcare haven’t truly come back down.
Why the 2026 COLA May Not Be Enough
Although the 2.8% COLA aims to help beneficiaries keep up with inflation, many retirees report that their actual cost of living has increased by well over 3%. Everyday expenses — particularly healthcare premiums, prescription drugs, and food — have outpaced average inflation in recent years.
For retirees living on a fixed income, this can feel like a slow squeeze. Even small differences between the COLA and real inflation can add up to a meaningful loss in purchasing power over time.
The Timing Problem: If Inflation Heats Up, Help May Be a Year Away
One major challenge with the COLA system is timing. Adjustments are made once per year, based on inflation readings from the third quarter of the previous year.
That means if inflation begins to surge again in mid-2026 — say, to 4% or higher — retirees won’t see an increase in their Social Security benefits until January 2027. By then, a full year of higher prices could have eroded much of their financial cushion.
For retirees already struggling to cover basic costs, that lag can create a serious hardship.
What Can Retirees Do?
If the COLA isn’t keeping up with rising expenses, retirees may need to take proactive steps to protect their financial well-being. A few options to consider:
Reevaluate annual spending. Look for non-essential expenses that can be trimmed or delayed.
Explore part-time or flexible income. Even modest earnings can help bridge the gap during higher-inflation periods.
Lean on family support if necessary. Having an honest discussion about temporary help from family members can make a meaningful difference.
Revisit your financial plan. This is a good time to review your withdrawal strategy, investment income, and emergency savings to make sure your plan can weather inflation surprises.
The Importance of Adjusting Retirement Projections for Inflation
When planning for retirement, it’s critical to adjust annual expenses for inflation in your projections. Even modest inflation can dramatically change your future spending needs.
Let’s look at an example:
A 65-year-old retiree today has annual living expenses of $60,000.
If inflation averages 3% per year, by age 75, those same expenses would grow to roughly $80,600.
That’s over $20,000 more per year — just to maintain the same standard of living.
Failing to account for inflation in your retirement projections can lead to underestimating how much income you’ll truly need down the road. Whether you’re living off investment withdrawals, pensions, or Social Security, it’s essential to plan for rising costs and ensure your income sources can keep pace.
Final Thoughts
Now more than ever, staying proactive about budgeting, income planning, and inflation protection strategies is essential. Social Security was never meant to cover all retirement expenses — and in today’s environment, it’s important to ensure your broader financial plan can pick up where the COLA falls short.
About Michael……...
Hi, I’m Michael Ruger. I’m the managing partner of Greenbush Financial Group and the creator of the nationally recognized Money Smart Board blog . I created the blog because there are a lot of events in life that require important financial decisions. The goal is to help our readers avoid big financial missteps, discover financial solutions that they were not aware of, and to optimize their financial future.
Frequently Asked Questions (FAQ)
How much will Social Security benefits increase in 2026?
The Social Security Administration announced a 2.8% Cost-of-Living Adjustment (COLA) for 2026, a modest rise from 2.5% in 2025. This increase remains below the ten-year average of roughly 3.1%.
Why is the 2026 COLA increase considered modest?
While the 2.8% adjustment helps offset inflation, it’s smaller than the larger increases retirees saw in 2022 and 2023 during periods of high inflation. Many retirees feel everyday costs, especially for healthcare and essentials, continue to rise faster than official inflation measures suggest.
How does the timing of COLA adjustments affect retirees?
COLA calculations are based on inflation data from the third quarter of the previous year, meaning there’s often a delay in responding to rising prices. If inflation increases during 2026, beneficiaries won’t see higher payments until 2027, leaving a potential gap between expenses and income.
What can retirees do if their Social Security increase isn’t keeping up with inflation?
Retirees can review spending habits, trim non-essential costs, explore part-time income opportunities, and update financial plans to better manage inflation risks. Maintaining flexibility and preparing for price changes can help preserve purchasing power.
How can inflation impact long-term retirement planning?
Even moderate inflation significantly raises living costs over time. For example, a retiree spending $60,000 annually could need over $80,000 within ten years if inflation averages 3%, underscoring the importance of including inflation adjustments in retirement projections.
Why is it important to revisit a financial plan regularly during retirement?
Regularly reviewing your financial plan helps ensure that income sources, such as investments or pensions, continue to meet rising expenses. Adjusting for inflation, healthcare costs, and market changes can help retirees maintain their desired standard of living.
Advantages of Using A Bond Ladder Instead of ETFs or Mutual Funds
Bond ladders can provide investors with predictable income, interest rate protection, and more control compared to bond ETFs or mutual funds. Greenbush Financial Group breaks down how they work, the different ladder strategies, and why some investors prefer this approach.
By Michael Ruger, CFP®
Partner and Chief Investment Officer at Greenbush Financial Group
When it comes to investing, one of the biggest challenges is dealing with interest rate uncertainty. Rates go up, rates go down, and bond prices fluctuate with those changes. For investors who want predictable income and a way to smooth out the risks of rising and falling interest rates, a bond ladder can be a powerful strategy.
In this article, we’ll walk through:
What a bond ladder is and how it works
How a bond ladder helps hedge against interest rate fluctuations
The different types of bond ladders (equal-weighted, barbell, middle-loaded)
Why some investors prefer an individual bond ladder over bond mutual funds or ETFs
What Is a Bond Ladder?
A bond ladder is a portfolio of individual bonds with staggered maturity dates. For example, you might buy bonds maturing in 1 year, 2 years, 3 years, 4 years, and 5 years. When the 1-year bond matures, you reinvest the proceeds into a new 5-year bond, keeping the “ladder” in place.
This structure offers two key benefits:
Hedging Interest Rate Risk: Since a portion of your ladder matures every year (or at regular intervals), you always have an opportunity to reinvest at the prevailing interest rate—whether rates go up or down.
Consistent Income and Liquidity: The maturing bonds provide cash flow that can be reinvested or used for spending needs.
In short, a bond ladder helps smooth out the effects of interest rate fluctuations while still generating steady income.
Types of Bond Ladders and How They Work
There isn’t just one way to build a bond ladder. The structure you choose depends on your investment goals, risk tolerance, and views on interest rates. Here are three common approaches:
1. Equal-Weighted Bond Ladder
How it works: Bonds are spread evenly across maturity dates (e.g., equal amounts in 1, 2, 3, 4, and 5-year maturities).
Why use it: This is the most straightforward approach. It balances risk and return by spreading exposure across time horizons, making it a good fit for investors who want predictability.
2. Barbell Strategy
How it works: Bonds are concentrated at the short and long ends of the maturity spectrum, with little or nothing in the middle. For example, you might own 1-year and 10-year bonds, but nothing in between.
Why use it: Short-term bonds provide liquidity and flexibility, while long-term bonds lock in higher yields. This strategy can be appealing when you expect interest rates to change significantly in the future.
3. Middle-Loaded Ladder
How it works: Bonds are concentrated in intermediate maturities (e.g., 3–7 years).
Why use it: Provides a balance between short-term reinvestment risk and long-term interest rate exposure. This can be attractive if you think the current yield curve makes mid-range maturities the “sweet spot” for returns.
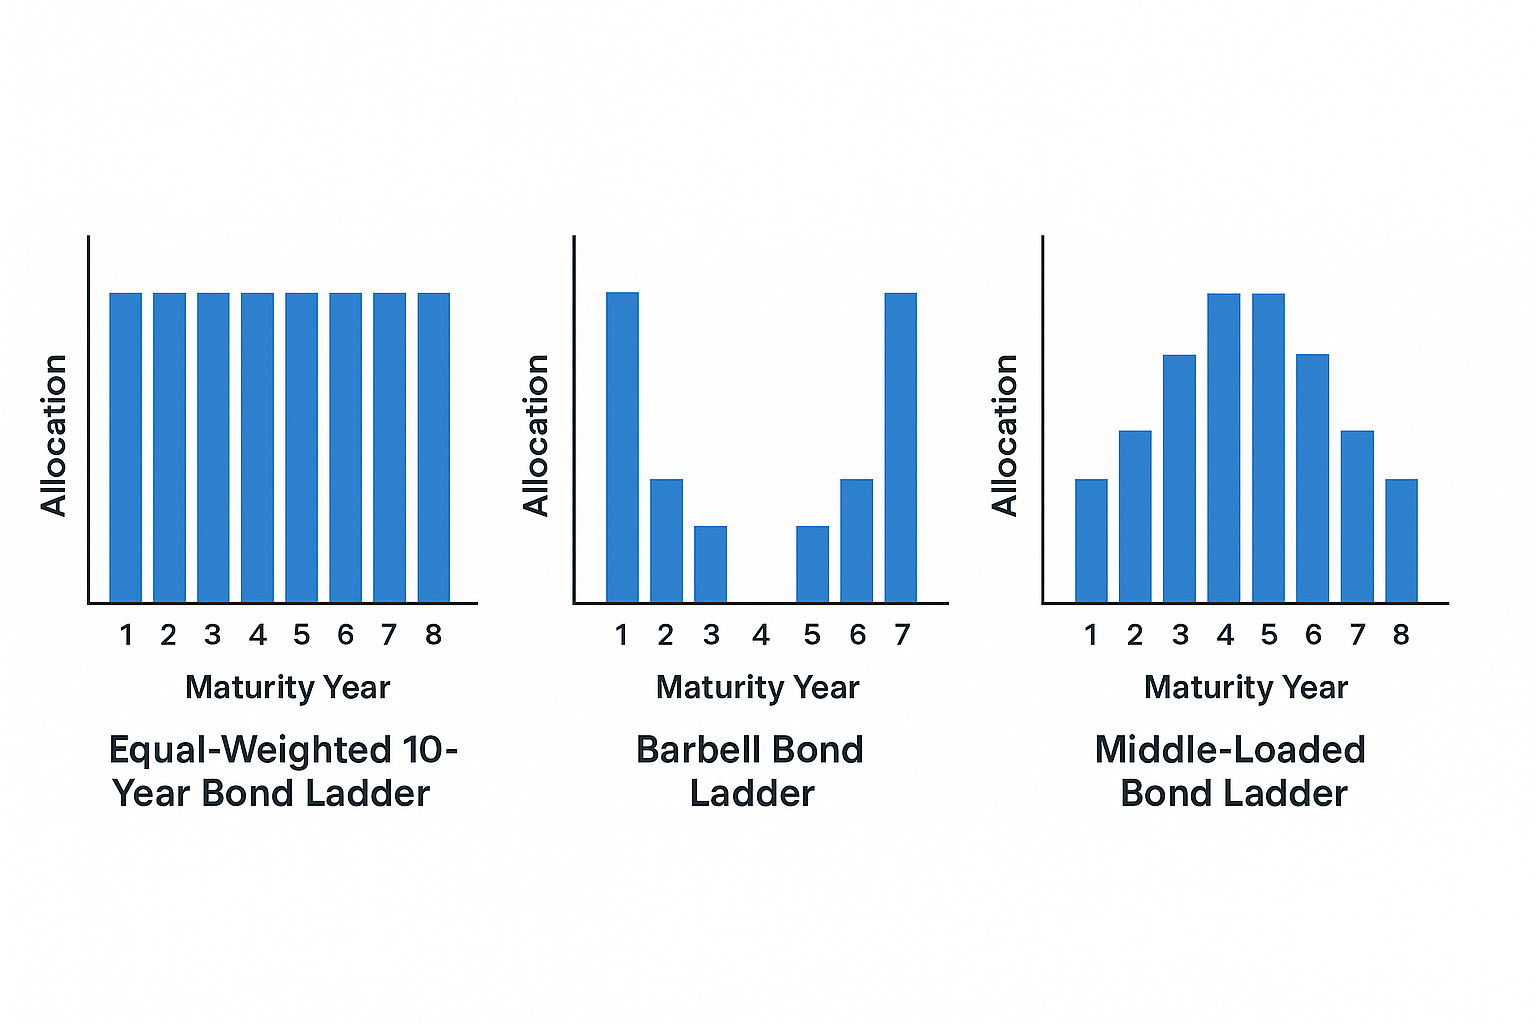
Bond ladders can also vary by duration. Some investors create 5-year ladders, 10-year ladders, or 20-year ladders.
Why Build a Bond Ladder Instead of Using a Mutual Fund or ETF?
You might wonder: why not just buy a bond fund and let the professionals handle it? There are several reasons why individual investors prefer building their own bond ladders:
Predictable Cash Flow: With a ladder, you know exactly when each bond will mature and what it will pay. Bond funds and ETFs fluctuate daily, and there are no set maturity dates.
Control Over Holdings: You decide the maturity schedule, the credit quality, and the exact bonds in your ladder. In a fund, you’re subject to the manager’s decisions.
Reduced Interest Rate Risk: In a bond ladder, if you hold bonds to maturity, you get your principal back regardless of market fluctuations. Bond funds never truly “mature,” so you’re always exposed to price swings.
Potentially Lower Costs: By buying individual bonds and holding them, you avoid ongoing expense ratios charged by mutual funds and ETFs.
In short, a bond ladder offers clarity, predictability, and control that pooled investment vehicles can’t always match.
Why You Need Significant Capital for a Bond Ladder
While bond ladders offer many advantages, they aren’t practical for every investor. Building a well-diversified ladder requires a substantial amount of money for a few reasons:
Minimum Purchase Amounts: Many individual bonds trade in $1,000 or $5,000 increments. To build a ladder with multiple rungs across different maturities, you need enough capital to meet those minimums. When investing in short-term U.S. treasuries, sometimes the purchase minimum is $250,000.
Diversification Needs: A proper ladder spreads risk across multiple issuers and maturities. Doing this with small amounts of money is difficult, leaving you concentrated in just a few bonds.
Transaction Costs: Buying and selling individual bonds often involves markups or commissions, which can eat into returns if the investment amount is too small.
Income Needs: If you’re using the ladder to generate income, small investments may not produce meaningful cash flow compared to what’s achievable with funds or ETFs.
For these reasons, investors with smaller portfolios often turn to bond mutual funds or ETFs. These vehicles pool money from many investors, allowing even modest contributions to achieve diversification, professional management, and steady income without the large upfront commitment required by a ladder
Final Thoughts
A bond ladder can be an excellent strategy for investors looking to hedge interest rate risk, generate predictable income, and maintain flexibility. Whether you choose an equal-weighted ladder for balance, a barbell strategy for flexibility and yield, or a middle-loaded approach to target the sweet spot of the curve, the right structure depends on your unique goals.
And while bond mutual funds and ETFs may be convenient, an individual bond ladder provides unmatched control, transparency, and reliability.
If you’re considering adding a bond ladder to your portfolio, the key is aligning it with your financial objectives, income needs, and risk tolerance. Done correctly, it’s a time-tested way to bring stability and consistency to your investment plan.
About Michael……...
Hi, I’m Michael Ruger. I’m the managing partner of Greenbush Financial Group and the creator of the nationally recognized Money Smart Board blog . I created the blog because there are a lot of events in life that require important financial decisions. The goal is to help our readers avoid big financial missteps, discover financial solutions that they were not aware of, and to optimize their financial future.
Frequently Asked Questions (FAQs)
What is a bond ladder and how does it work?
A bond ladder is a portfolio of individual bonds with staggered maturity dates, such as 1-, 2-, 3-, 4-, and 5-year terms. As each bond matures, the proceeds are reinvested into a new long-term bond, creating a cycle that provides steady income and helps manage interest rate risk.
How does a bond ladder help protect against interest rate changes?
Because bonds mature at regular intervals, you continually reinvest at current market rates. This means when interest rates rise, maturing bonds can be rolled into higher-yielding ones; when rates fall, the longer-term bonds in the ladder continue to earn higher fixed rates.
What are the different types of bond ladders?
Common structures include equal-weighted ladders (evenly spread maturities), barbell strategies (short- and long-term maturities), and middle-loaded ladders (focused on intermediate terms). Each structure balances risk, return, and flexibility differently.
Why might investors choose a bond ladder over a bond mutual fund or ETF?
An individual bond ladder offers predictable maturity dates, control over holdings, and stable cash flow if bonds are held to maturity. In contrast, bond funds and ETFs fluctuate in value and have no set maturity, which can expose investors to ongoing price volatility.
Who is a bond ladder best suited for?
Bond ladders typically work best for investors with larger portfolios who want predictable income and can meet minimum bond purchase requirements. Smaller investors may prefer bond funds or ETFs for diversification and lower entry costs. We advise consulting with your personal investment advisor.
What are the key advantages of using a bond ladder in a portfolio?
A bond ladder provides consistent income, reduces interest rate risk, and enhances liquidity through regular maturities. It also allows investors to match cash flow needs with future expenses while maintaining control over credit quality and investment duration.
What is the Value of My Pension?
In our latest article, we break down how to calculate the present value of your pension—a powerful way to compare your pension to your other retirement assets and make better long-term decisions.
Whether you’re 5 years from retirement or already collecting, this article will help you see your pension in a new light.
For many Americans approaching retirement, a pension represents one of the most valuable pieces of their financial picture. But while pensions may promise reliable income in the future, they can be hard to evaluate in present terms—especially if you’re trying to compare your pension to a 401(k), IRA, or a lump-sum offer from your employer. That’s where calculating the present value of your pension becomes useful.
In this article, we’ll break down what present value means, how to calculate it, and why it’s essential for retirement planning.
What Is Present Value and Why Does It Matter?
The present value (PV) of your pension tells you how much the future stream of income payments is worth in today’s dollars. It answers this question:
“If I had to replace my pension with a lump sum today, how much money would I need?”
This is especially important when:
You're offered a lump-sum payout option instead of monthly payments
You're comparing your pension to your other investments
You're trying to understand your net worth or financial independence readiness
Step 1: Gather the Details of Your Pension
To begin, you’ll need the following information, which you should be able to request from your employer or pension administrator:
Annual or monthly payment amount
Start date of pension payouts
Expected length of payments (based on life expectancy or plan rules)
Discount rate (assumed rate of return—typically between 4%–6%)
Let’s look at an example:
You’re eligible to receive $30,000 per year
Payments start at age 65
You expect payments to last for 20 years (Age 85 Life Expectancy)
You use a 5% discount rate
Step 2: Use the Present Value of an Annuity Formula
Most pensions pay a fixed amount each year. This makes them resemble a type of annuity. To calculate the present value of that annuity, use the formula:
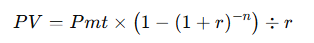
Where:
PV = present value
Pmt = annual pension payment
r = discount rate (as a decimal)
n = number of years of payment
In our example:
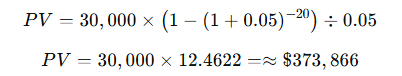
So the present value of this pension is about $373,866.
Step 3: Adjust for the Time Until Retirement
If you're not retiring immediately, you’ll need to discount the result back to today’s dollars.
Let’s say you're 55 now, and payments begin at 65. That’s a 10-year delay. The formula becomes:

This means the value of your pension—in today’s dollars—is roughly $229,625.
How Should You Choose a Discount Rate?
The discount rate reflects your assumed rate of return if you invested that money yourself. When we create financial plans for individuals, we typically assume a rate of return of 6-7% before retirement and 4% in retirement for investments. Unlike a 401(k) or other investment account where the account owner assumes the investment risk, a pension is more of a “promise to pay” and the investment risk is assumed by the organization paying the benefit. When estimating the present value of a pension, we typically recommend using a more conservative rate of 4-5%. If you believe your rate of return would be higher if you invested the money yourself, that would increase the discount rate used in the calculation above and reduce the estimated present value of your pension.
Other Factors to Consider
Cost of Living Adjustments (COLAs)
If your pension increases each year to keep up with inflation, it’s worth more than a flat pension and requires a different calculation.Joint Life Payouts
If your pension pays for your spouse’s lifetime too, you’ll need to factor in their life expectancy as well.Taxes
Pension payments are typically taxed as ordinary income. This doesn’t change the present value math, but it matters when comparing to Roth accounts or after-tax investments.
When Calculating Present Value Can Help
Here’s when you might want to calculate your pension’s present value:
Deciding between a monthly pension or lump sum
Coordinating pension income with Social Security and investment withdrawals
Evaluating your retirement readiness
Planning how to split retirement assets in a divorce
It gives you a common-dollar framework for comparison—turning an income stream into a lump sum you can benchmark and plan around.
Final Thoughts
Your pension may be one of the most stable sources of income in retirement, but stability doesn’t always equal clarity. By calculating its present value, you equip yourself with a concrete number you can use in your overall retirement strategy. Whether you’re weighing a lump sum, planning for early retirement, or just seeking a clearer financial picture, this number helps turn your pension into a more actionable asset.
Rob Mangold
About Rob……...
Hi, I’m Rob Mangold. I’m the Chief Operating Officer at Greenbush Financial Group and a contributor to the Money Smart Board blog. We created the blog to provide strategies that will help our readers personally, professionally, and financially. Our blog is meant to be a resource. If there are questions that you need answered, please feel free to join in on the discussion or contact me directly.
Should Your Investment Strategy Change when You Retire
Should your investment strategy change when you retire? Most people don’t realize how much the answer impacts taxes, income, and long-term security. Retirement isn’t the end of your financial planning—it’s the start of a new phase. Your goals shift from growth to income, and your investment strategy should evolve with them.
Retirement marks a major shift in your financial life: you move from saving and accumulating wealth to spending it. But does that mean your investment strategy should change the moment you stop working?
The answer isn’t a simple yes or no—it depends on your goals, income needs, and risk tolerance. Let’s explore what changes may be necessary, what can stay the same, and how to align your investment approach with the realities of retirement.
1. Accumulation vs. Distribution: A New Financial Phase
During your working years, your investment strategy likely focused on growth—maximizing returns over the long term. For most, in retirement, the focus shifts to income and moderate growth. Your portfolio now needs to:
Support monthly withdrawals
Last for 20–30+ years
Withstand market volatility without derailing your lifestyle
This shift doesn't mean abandoning growth altogether, but it does mean adjusting how you balance risk and reward.
2. Reassess Your Asset Allocation
One of the first things to review in retirement is your asset allocation—how your investments are divided among stocks, bonds, and cash.
A typical pre-retirement portfolio may be 70–100% in equities. But in retirement, many advisors recommend dialing that back to reduce risk.
Example:
If you have a $1 million portfolio:
A 60/40 allocation would mean $600,000 in diversified stock funds and $400,000 in bonds or other fixed-income assets.
A 40/60 allocation might suit someone who is more risk-averse or heavily reliant on portfolio withdrawals.
Mistake Alert:
Some retirees swing too far into conservative territory. While that may feel safe, inflation can quietly erode your purchasing power—especially over a 25- to 30-year retirement.
3. Add an Income Strategy
Now that you’re drawing from your investments, it’s essential to have a plan for generating reliable income and decreasing the level of volatility with your portfolio. This may include:
Dividend-paying stocks or ETFs
Bond holdings or short-term fixed income
The goal is to create stable cash flow while giving your growth assets time to recover from market dips.
4. Be Strategic With Withdrawals
Your withdrawal strategy has a major impact on taxes and portfolio longevity. The order you pull from different account types matters.
Example:
Let’s say you need $80,000/year from your portfolio. You might:
Take $40,000 from a taxable account (capital gains taxed at lower rates)
Pull $20,000 from a Traditional IRA (fully taxable as income)
Social Security $20,000 (up to 85% taxable)
This balanced approach spreads the tax burden, avoids pushing you into a higher bracket, and gives your Roth assets (if you have them) more time to grow.
Common Misstep:
Many retirees default to depleting all of their after-tax assets first, but by not taking withdrawals from their tax-deferred accounts, like Traditional IRAs and 401(k) accounts, they potentially miss out on realizing those taxable distributions at very low tax rates. Having a withdrawal plan that coordinates your social security, Medicare premiums, after-tax accounts, pre-tax accounts, and Roth accounts is key.
5. Stay Diversified—Reduce Volatility In Portfolio
Diversification and reducing volatility are key considerations when entering retirement years. When you take withdrawals from your retirement accounts, the investment returns can vary significantly from those of the accumulation years. Why is that?
When you were working and contributing to your retirement accounts, and the economy hit a recession, since you were not withdrawing any money from your accounts when the market rebounded, you likely regained those losses fairly quickly. But in retirement, when you are taking distributions from the account as the market is moving lower, there is less money in the account when the market begins to rally. As such, your rate of return is more significantly impacted by market volatility when you enter distribution mode.
To reduce volatility in your portfolio, you may need to:
Increase your level of diversification across various asset classes
Keep a large cash reserve on hand to avoid selling stocks in a downturn
Be more proactive about adjusting your investment allocation in response to changing market conditions
6. Don’t Forget About Growth
Retirement could last 30 years or more. That means your portfolio needs to outpace inflation, especially with rising healthcare and long-term care costs.
Even if you’re taking distributions, keeping 30–60% in equities may help ensure your money grows enough to support you in later decades.
Final Thoughts: Don’t “Set It and Forget It”
Your investment strategy should evolve with you. Retirement isn’t a one-time financial event—it’s a new chapter that requires ongoing planning and regular reviews.
About Michael……...
Hi, I’m Michael Ruger. I’m the managing partner of Greenbush Financial Group and the creator of the nationally recognized Money Smart Board blog . I created the blog because there are a lot of events in life that require important financial decisions. The goal is to help our readers avoid big financial missteps, discover financial solutions that they were not aware of, and to optimize their financial future.
Frequently Asked Questions (FAQs):
Should your investment strategy change when you retire?
While the focus shifts from accumulation to income and preservation, your investment approach should evolve based on your goals, risk tolerance, and income needs. Many retirees move toward a more balanced portfolio that supports sustainable withdrawals while still allowing for growth.
What’s the difference between the accumulation and distribution phases?
During the accumulation phase (your working years), the goal is to grow wealth through regular contributions and long-term compounding. In the distribution phase (retirement), you rely on your savings for income, so the emphasis shifts to generating steady cash flow and managing risk.
How should retirees adjust their asset allocation?
Many retirees move from aggressive stock-heavy portfolios to more balanced allocations—like 60/40 (stocks/bonds) or 40/60—depending on their comfort with risk. However, being too conservative can expose you to inflation risk, which can erode purchasing power over time.
How can you generate income from your investments in retirement?
Common income strategies include using dividend-paying stocks, bonds, or fixed-income funds to provide a steady cash flow. A well-structured income plan helps cover expenses while allowing growth-oriented investments to recover from market downturns.
What’s the best order to withdraw funds from retirement accounts?
Strategic withdrawals can help minimize taxes and extend portfolio longevity. The right order depends on your income, Social Security, and Medicare situation.
Why is diversification so important in retirement?
Diversification can reduce portfolio volatility—critical during retirement, when you’re withdrawing funds. Selling assets during a market downturn can permanently harm portfolio growth. Diversifying across asset classes and maintaining a cash buffer may help reduce the impact of market volatility.
Should retirees still invest in stocks?
In most cases, yes. Even in retirement, equities are important for long-term growth and inflation protection. With retirees living longer, it’s not uncommon for retirees to maintain investment accounts for 15+ years into retirement.
How often should retirees review their investment strategy?
At least once a year—or after major life or market changes. Retirement isn’t static, and your investment strategy should adjust to reflect evolving income needs, health costs, tax law updates, and market conditions.
What’s the most common mistake retirees make?
Becoming too conservative too soon. Avoiding market exposure entirely can limit growth and increase the risk of outliving your savings. A balanced approach that manages volatility while maintaining some growth potential is ideal in most situations.
