Should You Process Roth Conversions Before You Retire?
Should you process Roth conversions before you retire, or wait until retirement? Learn how tax brackets, income, Medicare premiums, state taxes, RMDs, and timing can determine when a Roth conversion may make the most sense.
By Michael Ruger, CFP®
Partner and Chief Investment Officer at Greenbush Financial Group
As you approach retirement, one of the biggest tax-planning questions you may encounter is whether you should begin converting some of your pre-tax retirement accounts to a Roth IRA.
Roth conversions can be a powerful retirement tax strategy when used correctly. They can allow you to take advantage of temporarily lower tax brackets, reduce the amount of money accumulating in pre-tax retirement accounts, potentially reduce future required minimum distributions, and create a larger pool of tax-free assets for later in retirement.
But a Roth conversion isn't automatically a good strategy simply because you are approaching retirement. In fact, processing a large Roth conversion during the wrong year can result in paying substantially more in taxes than necessary.
When we evaluate Roth conversions as part of a financial plan, some of the most important considerations include:
Your current federal and state income tax brackets
Your expected tax brackets after retirement
Whether you are experiencing an unusually low-income year
The amount you have accumulated in pre-tax retirement accounts
Your expected future required minimum distributions
Where you live now and where you plan to live in retirement
Potential future inheritances
Medicare premiums once you reach Medicare age
How you plan to pay the taxes generated by the conversion
The real question isn't simply, “Should I do a Roth conversion?” A better question is, “At what tax rate does it make sense for me to convert pre-tax retirement assets to Roth assets?”
What Is a Roth Conversion?
A Roth conversion involves moving money from a pre-tax retirement account, such as a traditional IRA, into a Roth IRA. Some 401K plan even allow “in plan Roth conversions” from pre-tax to a Roth source within the plan.
The important part is what happens for tax purposes.
Generally, the taxable portion of the amount converted from a traditional IRA to a Roth IRA is included in your taxable income for that year. You are essentially choosing to pay the income tax today in exchange for moving those assets into the Roth environment.
Why would you voluntarily accelerate a tax bill? Because qualified Roth IRA distributions can eventually be tax-free, and Roth IRAs are not subject to lifetime required minimum distributions for the original owner. By paying tax today, you may be able to create greater tax flexibility later in retirement. The strategy can be particularly attractive if you can pay tax on the conversion at the same or lower tax rate today, compared to the one you would pay in the future during the retirement years.
Be Careful With Roth Conversions During Your Peak Earning Years
One of the biggest mistakes we see in Roth conversion planning is focusing only on the benefits of the Roth IRA without considering the tax cost of getting the money there. Imagine that you are 60 years old, still working, and earning one of the highest salaries of your career. You decide to convert $200,000 from your traditional IRA into a Roth IRA.
That $200,000 doesn't replace your salary for tax purposes. Generally, the taxable conversion amount is added on top of your other taxable income. If you are already in a high federal income tax bracket—and potentially paying state income tax as well—the conversion could result in a very large tax bill. This is why Roth conversions immediately before retirement aren't always advantageous.
If you're going to retire in two years and your taxable income is expected to fall dramatically, why voluntarily recognize a large amount of additional income while you are still in one of your highest tax brackets? In some situations, waiting until retirement may provide a much better opportunity.
The Ideal Roth Conversion Opportunity: An Abnormally Low-Income Year
Some of the best Roth conversion opportunities occur when someone's income temporarily drops. This can happen before or after retirement. Consider a self-employed consultant who normally generates approximately $700,000 of annual income. For whatever reason, the business has a difficult year and the consultant only generates $100,000. If the consultant expects income to return to $700,000 the following year, that temporary decline may create an opportunity.
Instead of allowing lower tax brackets to go unused, the business owner could evaluate converting some traditional IRA assets to a Roth IRA and intentionally recognizing additional taxable income during the lower-income year.
The key word here is intentionally.
Rather than picking an arbitrary conversion amount, the taxpayer and their advisors can estimate taxable income for the year and determine how much could potentially be converted at acceptable marginal tax rates. This concept is often referred to as filling up the tax brackets.
Roth Conversions When One Spouse Retires Before the Other
Another common opportunity occurs when spouses retire at different times. Suppose both spouses have historically earned $150,000 per year. Their combined employment income is approximately $300,000.
Now assume one spouse retires at age 60 while the other continues working.
Their employment income suddenly falls from $300,000 to approximately $150,000.
Depending on their deductions and other income, this reduction could create room in lower tax brackets that wasn't available while both spouses were working. Instead of waiting until both spouses are retired, the couple could evaluate whether the period between the first and second retirement provides an attractive Roth conversion window. This is why Roth conversion planning often works best when it is mapped out over multiple years, rather than making the decision one year at a time.
What If Your Retirement Tax Rate Won't Be Lower?
A common assumption is that everyone moves into a lower tax bracket after retirement. That isn't always true. Some retirees accumulate very large balances in traditional IRAs, 401(k)s, 403(b)s, and other pre-tax retirement accounts. Eventually, distributions from those accounts can create substantial taxable income.
Required minimum distributions can also force money out of certain retirement accounts later in life, whether you need the income or not. Under current federal rules, traditional IRA owners generally begin RMDs at age 73, although applicable starting ages depend on birth year under current law.
For someone with significant pre-tax retirement assets, future taxable income may not decline nearly as much as expected. That can strengthen the case for evaluating Roth conversions earlier.
The $1 Million Traditional IRA Example
Assume you have $1 million in a traditional IRA.
You don't expect to need most of that money during the next decade. Over time, assume hypothetically that the account grows from $1 million to $2 million.
If the money remains in the traditional IRA, you have another $1 million of investment growth inside an account whose future taxable distributions will generally be subject to ordinary income tax. Now consider converting some of the traditional IRA to a Roth IRA today. You pay tax on the taxable conversion amount now, but future growth on the converted assets occurs inside the Roth IRA. If the applicable requirements are satisfied, qualified Roth distributions can eventually be received tax-free.
This can make Roth conversions particularly attractive when you expect your future marginal tax rate to be similar to or higher than your current rate. But there is an important caveat.
Don't Ignore the Tax Dollars You Give Up Today
It is easy to compare $1 million in a traditional IRA with $1 million in a Roth IRA and conclude that the Roth is obviously better. But those aren't economically equivalent balances. The traditional IRA contains money on which taxes generally haven't been paid yet. Converting it to Roth requires paying that tax.
Suppose a conversion would result in a combined federal and state marginal tax cost of 40%. That is a substantial upfront tax expense. If you pay the conversion tax from other assets, those dollars are no longer available to remain invested elsewhere. If you pay the tax from the IRA itself, less money makes it into the Roth account. That tax cost has to be included in the analysis.
In some situations, particularly when the current marginal tax rate is very high and the expected future tax rate is lower, not converting can produce a better financial result. This is why Roth conversion planning should involve an actual tax analysis rather than simply assuming that Roth accounts are always better than traditional retirement accounts.
New York Residents Have an Additional Roth Conversion Consideration
State income taxes can have a significant impact on Roth conversion decisions. New York provides a useful example.
Under current New York rules, taxpayers who meet the age requirements may exclude up to $20,000 of qualifying pension and annuity income from New York adjusted gross income. Married taxpayers who both have qualifying income can each potentially qualify for their own exclusion. New York's published guidance also recognizes qualifying IRA distributions, and state guidance specifically addresses Roth conversion income within the pension and annuity exclusion rules.
For a married couple in which both spouses qualify, this can potentially create an opportunity to convert qualifying amounts from traditional IRAs while reducing or eliminating New York income tax on a portion of the conversion.
Consider a hypothetical married couple who are both over age 59½ and each has a traditional IRA. If each spouse qualifies to use the full $20,000 exclusion against conversion income, they could potentially convert a combined $40,000 per year while excluding that qualifying amount for New York income-tax purposes.
If they did that for five years, they could potentially move $200,000 from traditional IRAs to Roth IRAs while using the available New York exclusions each year, assuming they continue to meet all applicable requirements. Federal income tax can still apply to those conversions.
Also, the $20,000 New York exclusion is not an additional $20,000 exclusively reserved for Roth conversions. Other qualifying pension or annuity income can use some or all of the same annual exclusion. This is why the taxpayer's entire income picture needs to be reviewed each year.
Your Future State of Residence Can Completely Change the Analysis
Now let's look at the state-tax question from the opposite direction. Assume you currently live and work in a state that imposes an income tax. However, you know that immediately after retirement you plan to establish residency in a state with no individual state income tax. Processing a large Roth conversion immediately before moving could potentially mean voluntarily paying state income tax that might have been avoided by waiting.
For example, imagine converting $500,000 while still domiciled in a state that taxes the conversion. If you instead retire, legitimately establish residency in a state without an individual income tax, and then process the conversion, the state-tax result could be materially different. Of course, residency and domicile involve specific rules, and moving to another state should not be treated as simply changing your mailing address.
But the larger planning point is important:
Where you live when the Roth conversion occurs can matter.
When someone is already planning a move in retirement, we want to coordinate the timing of Roth conversions with that move rather than viewing those decisions separately.
A Future Inheritance Can Affect Today's Roth Conversion Strategy
Potential inheritances can also influence Roth conversion planning. Suppose you are 60 years old and your parents are in their mid-80s. Your parents have accumulated substantial balances in traditional retirement accounts, and based on their current financial position, you expect that you may eventually inherit some of those assets.
Under current federal rules, many non-spouse designated beneficiaries who are not eligible designated beneficiaries generally must empty an inherited retirement account by the end of the tenth year following the original owner's death. Depending on when the owner died relative to their required beginning date and the beneficiary's status, annual distribution requirements can also apply during that period.
Taxable distributions from an inherited traditional IRA generally become income to the beneficiary. Now imagine inheriting a $1 million or $2 million traditional IRA while you already have significant pre-tax retirement assets of your own. That inheritance could materially increase taxable income during your retirement years.
In that situation, the assumption that “I'll be in a lower tax bracket after I retire” may turn out to be incorrect. If a significant inheritance is reasonably anticipated, it may be worth modeling whether converting some of your own traditional IRA assets earlier could reduce future tax concentration.
However, inheritances are inherently uncertain. Timing, asset values, healthcare expenses, estate-plan changes, and other circumstances can all change. For that reason, we generally would not want an entire Roth conversion strategy to depend on receiving a particular inheritance at a particular time.
Roth Conversions Can Affect Medicare Premiums
Medicare adds another important consideration.
Higher income can result in income-related monthly adjustment amounts, commonly called IRMAA, being added to Medicare Part B and Part D premiums. Roth conversions increase taxable income in the year of conversion and can therefore potentially result in higher Medicare premiums later, because Medicare generally uses income information from two years earlier when determining IRMAA.
This is particularly important for someone processing large Roth conversions at or after Medicare age.
However, there can also be a longer-term planning benefit. Reducing traditional IRA balances through Roth conversions may reduce future required minimum distributions. Lower future taxable income could potentially help reduce exposure to higher Medicare premiums in later years. In other words, Roth conversions don't automatically lower Medicare premiums.
A conversion could increase Medicare premiums in the short term while potentially helping control taxable income and Medicare costs later. That tradeoff needs to be included in the analysis.
Be Careful With Tax Withholding on Roth Conversions
Another important consideration is how you pay the tax generated by a Roth conversion. Suppose a 53-year-old wants to convert $100,000 from a traditional IRA to a Roth IRA. Assume the conversion creates an estimated $30,000 federal and state tax liability. Ideally, if appropriate and sufficient funds are available, the individual may consider paying that tax from cash or another non-retirement source so the entire $100,000 can reach the Roth IRA.
Why?
If $30,000 is withheld from the traditional IRA and only $70,000 actually reaches the Roth IRA, the withheld $30,000 is not part of the conversion. For someone under age 59½, amounts distributed and not rolled over may also be subject to the 10% additional tax on early distributions unless an exception applies. The IRS specifically illustrates this principle for rollover withholding.
That can make using retirement assets to pay conversion taxes particularly costly for someone younger than 59½. Once someone is over age 59½, the 10% early-distribution tax generally no longer applies based solely on age. However, withholding taxes from the retirement account still means fewer dollars ultimately reach the Roth IRA. For that reason, even after age 59½, paying the conversion tax from outside assets may be preferable when the overall financial plan supports it.
Why We Often Wait Until Later in the Year to Process Roth Conversions
Timing during the calendar year is another important part of Roth conversion planning. When possible, we often prefer to make final Roth conversion decisions later in the year.
Why?
Because income has a way of surprising people. This is especially true for business owners, executives, sales professionals, and anyone whose compensation includes bonuses, commissions, stock compensation, or other variable income. Consider an employee earning a $200,000 base salary who plans to process a $50,000 Roth conversion.
In March, everything looks straightforward.
The employee processes the $50,000 conversion.
Then the company has an exceptional year and, in November, the employee receives an unexpected $100,000 bonus.
That bonus may push some or all of the Roth conversion income into a higher marginal tax bracket than originally anticipated. Had the employee known about the bonus before converting, they might have reduced the conversion or skipped it entirely for that year.
November and Early December Can Be Good Planning Windows
By November or early December, you may have a much clearer picture of your annual income.
W-2 employees generally have a good idea of their salary, bonuses, and other compensation. Business owners have most of the year's financial results available. Investment income, capital gains, pension payments, and other income sources are also easier to estimate. At that point, you and your tax and financial professionals can prepare an income projection and determine how much Roth conversion room may be available within your desired tax brackets.
However, there is another side to this strategy:
Don't wait until December 31.
Financial institutions can have year-end processing deadlines, and conversion requests may require time to complete. Waiting until the final days of December creates the risk that the transaction will not be completed during the intended tax year. If you are considering a year-end Roth conversion, contact your custodian well in advance and determine its processing deadlines.
Roth Conversion Planning Should Be a Multi-Year Strategy
Perhaps the biggest mistake is viewing a Roth conversion as a one-time, all-or-nothing decision. Imagine that you have $800,000 in a traditional IRA.
The question isn't necessarily:
“Should I convert the entire $800,000?”
Doing so in one year could create an enormous tax bill and push a significant amount of the conversion into higher tax brackets. Instead, perhaps the better strategy is converting $50,000 this year, $80,000 next year, $100,000 during the first year of retirement, and additional amounts during subsequent lower-income years. The appropriate numbers will be different for everyone.
This approach allows you to potentially fill lower tax brackets over multiple years rather than creating one enormous taxable event.
The years immediately following retirement can sometimes provide an especially valuable Roth conversion window. Employment income may have stopped, Social Security may not have started, and required minimum distributions may still be years away.
That gap can provide opportunities to recognize income intentionally at tax rates you find acceptable.
So, Should You Process Roth Conversions Before Retiring?
Sometimes.
Roth conversions before retirement can make a lot of sense when you encounter an unusually low-income year, when one spouse retires before the other, when current and expected future tax rates are similar, when you have substantial pre-tax retirement balances, or when future income—including potential inherited retirement assets—could push you into higher tax brackets.
They can also make sense when state-specific tax provisions create an opportunity. But there are equally valid reasons to wait. If you are currently in your peak earning years and expect your income to fall substantially after retirement, converting today could mean voluntarily paying tax at a much higher rate.
If you plan to move from a state with an income tax to a state without one, waiting could potentially produce state-tax savings. And if you are approaching Medicare or already enrolled, the impact of conversion income on IRMAA should also be considered.
The goal isn't simply to get as much money into a Roth IRA as possible.
The goal is to determine when and how much to convert so that you can potentially reduce the amount of tax you pay over your lifetime while maintaining flexibility throughout retirement.
That requires looking beyond this year's tax return. A good Roth conversion analysis considers your current tax brackets, projected retirement income, Social Security, pensions, required minimum distributions, Medicare premiums, state taxes, investment growth, estate planning, and potentially even inherited retirement assets. When all of those variables are considered together, Roth conversions can become a powerful component of a comprehensive retirement tax strategy.
About Michael……...
Hi, I’m Michael Ruger. I’m the managing partner of Greenbush Financial Group and the creator of the nationally recognized Money Smart Board blog . I created the blog because there are a lot of events in life that require important financial decisions. The goal is to help our readers avoid big financial missteps, discover financial solutions that they were not aware of, and to optimize their financial future.
Frequently Asked Questions About Roth Conversions Before Retirement
-
Should I do a Roth conversion before I retire?A Roth conversion before retirement may make sense if your current marginal tax rate is lower than or similar to the rate you expect to pay later. It can be particularly attractive during an unusually low-income year or when one spouse retires before the other. However, individuals in their peak earning years may benefit from waiting until retirement if their taxable income is expected to decline substantially.
-
What is the best age to do a Roth conversion?There is no single best age for a Roth conversion. The best opportunities are often determined by your tax bracket rather than your age. Low-income years between retirement and the beginning of Social Security or required minimum distributions can be particularly valuable conversion windows. Your state taxes and Medicare situation should also be considered.
-
How much should I convert from my traditional IRA to a Roth IRA?The appropriate Roth conversion amount depends on your taxable income, deductions, federal and state tax brackets, Medicare considerations, and expected future income. Rather than choosing an arbitrary amount, many taxpayers evaluate how much they can convert while remaining within a targeted marginal tax bracket. A multi-year conversion strategy can sometimes be more tax-efficient than converting a large balance all at once.
-
Do I pay taxes when I convert a traditional IRA to a Roth IRA?Generally, yes. The taxable portion of a traditional IRA converted to a Roth IRA is included in income for the year of conversion. If the traditional IRA contains nondeductible contributions, the tax calculation can be more complicated. The conversion itself should therefore be coordinated with your overall tax situation.
-
Should I do Roth conversions before or after retirement?It depends primarily on your tax rates during each period. If you are in a high tax bracket while working and expect a substantially lower bracket immediately after retirement, waiting may be advantageous. If your income temporarily falls before retirement or future retirement income is expected to keep you in the same or a higher bracket, converting before retirement may deserve consideration.
-
Can a Roth conversion increase my Medicare premiums?Yes. A Roth conversion can increase modified adjusted gross income and may cause higher Medicare Part B and Part D premiums through IRMAA. Medicare generally uses tax-return information from two years earlier when determining these income-related adjustments. However, reducing pre-tax retirement balances through conversions could potentially reduce future required minimum distributions and taxable income, so both the short- and long-term Medicare effects should be considered.
-
Are Roth conversions taxable in New York State?Roth conversion income can be subject to New York income tax, but qualifying taxpayers age 59 1/2 or older may be eligible for New York's pension and annuity income exclusion of up to $20,000 per taxpayer. Married taxpayers can potentially each qualify for their own exclusion if each has qualifying income. Other pension income can also use the exclusion, so the full $20,000 may not always be available for a Roth conversion.
-
Should I pay Roth conversion taxes from my IRA or from cash?When possible and appropriate, paying the conversion tax from cash or other non-retirement assets can allow more of the retirement money to reach the Roth IRA. This can be especially important before age 59 1/2 because money distributed from an IRA for taxes rather than converted may be subject to the additional 10% early-distribution tax unless an exception applies. Even after age 59 1/2, withholding from the IRA reduces the amount transferred to the Roth.
-
Can an expected inheritance affect whether I should do Roth conversions?Yes. If you reasonably expect to inherit substantial traditional retirement accounts, future taxable distributions from those inherited accounts could increase your retirement income and potentially your marginal tax rate. Many non-spouse beneficiaries are subject to a 10-year distribution period under current federal rules. However, because the timing and amount of an inheritance are uncertain, it generally makes sense to model multiple scenarios rather than basing your entire Roth conversion strategy on an expected inheritance.
-
What time of year is best for a Roth conversion?Later in the year can be useful because you generally have a clearer picture of your salary, bonuses, business income, capital gains, and other taxable income. November or early December may provide enough information to estimate an appropriate conversion amount while still allowing time for the financial institution to process the transaction. Avoid waiting until the final days of December because custodians may have earlier year-end processing deadlines.




Common Backdoor Roth IRA Mistakes
A Backdoor Roth IRA can help high-income earners build tax-free retirement savings, but mistakes with the pro-rata rule, IRA balances, Form 8606, and conversion timing can create unexpected taxes. Learn the most common mistakes to avoid.
By Michael Ruger, CFP®
Partner and Chief Investment Officer at Greenbush Financial Group
The Backdoor Roth IRA strategy has become increasingly common among higher-income individuals who earn too much to make a direct contribution to a Roth IRA. The concept sounds relatively simple: make a nondeductible contribution to a Traditional IRA and then convert that money to a Roth IRA. Because there is no income limitation on Roth IRA conversions, this strategy can potentially allow higher-income taxpayers to continue building Roth assets even when their income prevents them from contributing directly to a Roth IRA.
However, simple does not always mean easy. We are seeing a growing number of mistakes in the execution of Backdoor Roth IRA strategies, and some of those mistakes can create unexpected taxable income, additional tax filings, and other complications.
In this article, we will cover some of the most common Backdoor Roth IRA mistakes, including:
How the Backdoor Roth IRA strategy works for high-income earners
How the Backdoor Roth IRA aggregation rule can create unexpected taxes
Why Traditional IRA, Rollover IRA, SEP IRA, and SIMPLE IRA balances can affect a Roth conversion
What investors should know about the Backdoor Roth IRA step-transaction rule
Why a Roth 401(k) does not prevent you from completing a Backdoor Roth IRA
Why IRS Form 8606 is critical when making nondeductible IRA contributions
How investment gains before a Roth conversion can create taxable income
How to avoid common Backdoor Roth IRA tax mistakes before executing the strategy
Understanding these rules before you move any money can make a significant difference. A Backdoor Roth IRA can be a powerful retirement planning strategy, but the tax treatment depends heavily on how the transaction is executed.
What Is a Backdoor Roth IRA?
A Backdoor Roth IRA is not a special type of retirement account. It is simply a strategy that generally involves making a nondeductible contribution to a Traditional IRA and then converting those assets to a Roth IRA. The strategy is primarily used by individuals whose income is too high to make a direct Roth IRA contribution.
For 2026, the Roth IRA contribution phaseout range is $153,000 to $168,000 for single filers and heads of household and $242,000 to $252,000 for married couples filing jointly. The 2026 IRA contribution limit is $7,500 for individuals under age 50 and $8,600 for individuals age 50 or older. While there are income limits that determine whether you can contribute directly to a Roth IRA, there is no similar income limitation that prevents an individual from converting Traditional IRA assets to a Roth IRA.
That difference is what makes the Backdoor Roth IRA strategy possible. Instead of contributing directly to a Roth IRA, the individual contributes after-tax money to a Traditional IRA and later converts that money to a Roth IRA. If the strategy is properly executed and the individual has no other pre-tax IRA money, the tax consequences of the conversion may be minimal or potentially zero.
Mistake #1: Ignoring the IRA Aggregation and Pro-Rata Rule
The IRA aggregation rule, also commonly called the pro-rata rule, is probably the most important Backdoor Roth IRA mistake to understand. Many investors assume that if they open a brand-new Traditional IRA, contribute after-tax money to that account, and convert only that account to a Roth IRA, the conversion will automatically be tax-free. Unfortunately, that is not always how the tax calculation works.
For purposes of determining how much of an IRA conversion is taxable versus nontaxable, the IRS generally does not allow you to isolate your nondeductible contribution from your other Traditional IRA money. Instead, applicable Traditional IRA balances are aggregated together when determining what percentage of the conversion represents pre-tax money and what percentage represents after-tax basis. This generally includes Traditional IRAs, Rollover IRAs, Traditional SEP IRAs, and Traditional SIMPLE IRAs.
A Simple $100,000 Backdoor Roth IRA Example
Assume John already has a Traditional IRA worth $95,000, and all $95,000 is pre-tax money. John then opens a separate Traditional IRA, contributes $5,000 to it, and does not take a tax deduction for that contribution. A few days later, he converts the entire $5,000 from the new Traditional IRA into his Roth IRA.
John may assume that because he contributed $5,000 of after-tax money and converted that same $5,000, the conversion should be tax-free. However, when the aggregation rule is applied, John effectively has $100,000 of total IRA money for purposes of this simplified example: $95,000 of pre-tax money and $5,000 of after-tax basis.
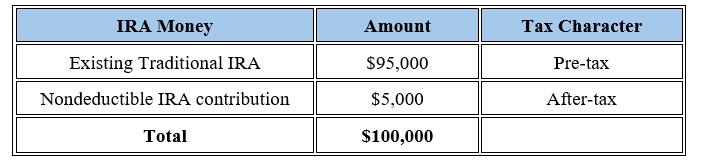
In this example, only 5% of John's IRA money represents after-tax basis, while 95% represents pre-tax money. Therefore, approximately 95% of the $5,000 Roth conversion would be taxable, or roughly $4,750. Only about $250 of the conversion would represent a nontaxable recovery of basis.
This is where many individuals get surprised. They believed they completed a tax-free $5,000 conversion, but because of the other pre-tax IRA assets, most of the conversion becomes taxable.
Opening a Separate IRA Does Not Avoid the Aggregation Rule
Another common misconception is that the aggregation rule can be avoided simply by opening a separate IRA at another financial institution. For example, someone may have a $500,000 Rollover IRA at one investment company and decide to open a brand-new Traditional IRA somewhere else specifically for the Backdoor Roth IRA strategy. Unfortunately, keeping the accounts physically separate does not necessarily separate them for tax purposes.
The same issue applies if one account is labeled a "Backdoor Roth IRA account." The IRS is generally looking at the applicable IRA balances collectively when determining the taxable portion of a distribution or conversion. Before executing a Backdoor Roth IRA, it is important to identify all existing Traditional, Rollover, SEP, and SIMPLE IRA balances that could potentially affect the calculation.
What About Money in a 401(k)?
A 401(k) is treated differently from an IRA for purposes of the Backdoor Roth aggregation calculation. Simply having a large balance in a current employer's 401(k) does not by itself create the same pro-rata problem. For example, an individual could have $800,000 in a pre-tax 401(k), no Traditional IRA balances, and still potentially execute a relatively clean Backdoor Roth IRA strategy.
This distinction can sometimes create planning opportunities. In certain situations, an employer's 401(k) may accept a rollover of pre-tax IRA assets, which could potentially move those assets out of the IRA aggregation calculation before year-end. However, that decision should not be made solely for tax convenience because investment choices, fees, creditor protections, withdrawal provisions, and other plan features should also be considered.
Mistake #2: Misunderstanding the Step-Transaction Concern
The second major issue surrounding Backdoor Roth IRAs involves what is commonly called the step-transaction doctrine. Very generally, this is a tax principle under which a series of formally separate transactions may, under certain circumstances, be viewed together based on their substance. Historically, this created concern that making a nondeductible Traditional IRA contribution and immediately converting it to a Roth IRA could potentially be viewed as an indirect way of making a Roth contribution that the individual was not otherwise eligible to make directly.
That concern has led to a lot of informal advice over the years suggesting that taxpayers should wait some period of time between making the nondeductible IRA contribution and completing the Roth conversion. You may hear recommendations to wait 30 days, 60 days, or 90 days. The important point is that there is no specific IRS safe harbor stating that waiting a particular number of days makes the strategy automatically protected from the step-transaction doctrine.
Current IRS guidance recognizes both nondeductible Traditional IRA contributions and Roth IRA conversions, and Roth conversions are not subject to the same income limits that apply to direct Roth IRA contributions. Therefore, we would be careful about presenting any specific waiting period as an IRS requirement. If you have concerns about how the step-transaction doctrine could apply to your specific situation, that is an issue to discuss with your CPA or tax attorney.
Waiting Can Create Another Backdoor Roth IRA Issue
There is another reason why blindly waiting 60 or 90 days is not necessarily the perfect solution. If the money inside the Traditional IRA is invested during that waiting period, the account could increase in value before the Roth conversion occurs. Those investment gains may create taxable income when the money is eventually converted.
For example, assume you make a $7,500 nondeductible contribution to a Traditional IRA and invest the money immediately. Over the next 90 days, the account grows to $7,900. If you then convert the entire $7,900 to the Roth IRA and you have no other IRA balances or basis, you generally have only $7,500 of after-tax basis, meaning the additional $400 of investment growth may be taxable.
This does not necessarily make the Backdoor Roth IRA strategy unsuccessful. Paying tax on a few hundred dollars of gains may be relatively minor. However, it is another reason why the timing of the contribution, investment, and conversion should be intentional rather than based on an assumed 60- or 90-day IRS requirement.
Mistake #3: Thinking a Roth 401(k) Prevents a Backdoor Roth IRA
Another common misconception is that someone who is already contributing to a Roth 401(k) cannot also execute a Backdoor Roth IRA strategy. That is not the case. Roth 401(k) contributions and IRA contributions are governed by separate annual contribution limits.
For example, assume a 45-year-old high-income employee is maxing out their Roth 401(k). For 2026, that individual could potentially contribute $24,500 to the Roth 401(k) and separately make a $7,500 nondeductible contribution to a Traditional IRA, followed by a Roth conversion, assuming the strategy is otherwise appropriate. The fact that both strategies involve Roth accounts does not cause the limits to overlap.
This can be especially valuable for higher-income households that are trying to accumulate more tax-free retirement assets. Someone who is already maximizing Roth 401(k) contributions may still have the opportunity to add additional money to a Roth IRA through the Backdoor Roth IRA strategy.
Mistake #4: Forgetting to File Form 8606
Form 8606 is one of the most important pieces of paperwork associated with a Backdoor Roth IRA. When you make a nondeductible contribution to a Traditional IRA, you need a tax record establishing that you did not take a deduction for that contribution and that the money represents after-tax basis. Without proper documentation, it may become much more difficult to prove years later how much of your IRA has already been taxed.
The IRS uses Form 8606 to report nondeductible Traditional IRA contributions, certain IRA distributions when basis exists, and conversions from Traditional IRAs to Roth IRAs. In practical terms, Form 8606 helps prevent you from potentially paying tax twice on the same money. If you contribute $7,500 to a Traditional IRA and do not claim a deduction, you do not want that same $7,500 to be treated as fully taxable when it is later converted or distributed.
This is why properly filing Form 8606 is not simply a minor administrative step. It is part of keeping an accurate tax record of your after-tax IRA basis. Individuals who execute Backdoor Roth IRA strategies year after year should pay close attention to making sure Form 8606 is prepared correctly each year.
Mistake #5: Forgetting About an Old SEP IRA or SIMPLE IRA
One of the easiest mistakes to make is forgetting about an old retirement account from years ago. Someone may currently be a W-2 employee with no obvious Traditional IRA or Rollover IRA and assume that their Backdoor Roth IRA will be straightforward. However, they may have opened a SEP IRA or SIMPLE IRA years earlier when they were self-employed or worked for a different company.
If that account still contains pre-tax money, it may affect the pro-rata calculation. For example, an old $80,000 SEP IRA sitting at another custodian may suddenly become very relevant when determining how much of a current Roth conversion is taxable.
This is why we recommend completing a retirement-account inventory before implementing the strategy. Do not simply ask whether you have a Traditional IRA. Ask whether you have any Traditional, Rollover, SEP, or SIMPLE IRA balances that could impact the calculation.
Mistake #6: Confusing the IRA Contribution Limit With the Roth Conversion Limit
Another common misunderstanding is assuming that if the annual IRA contribution limit is $7,500, then the maximum Roth conversion is also $7,500. Those are two completely different rules. The annual contribution limit determines how much new money can be contributed to an IRA, while a Roth conversion involves moving existing Traditional IRA assets into a Roth IRA.
For example, someone could make a $7,500 nondeductible Traditional IRA contribution and separately decide to convert $100,000 of existing pre-tax IRA assets to a Roth IRA. There is no general $7,500 annual limit on Roth conversions. However, converting pre-tax retirement assets to a Roth IRA generally creates taxable income, which means large conversions require careful tax planning.
This distinction is important because the Backdoor Roth IRA strategy involves both a contribution and a conversion. The contribution limit applies to the first step. The tax consequences of the conversion depend on the character of the money being converted and the individual's overall IRA situation.
A Backdoor Roth IRA Pre-Flight Checklist
Before executing a Backdoor Roth IRA, it can help to work through a short checklist. A few minutes spent reviewing your accounts before making the contribution or conversion can potentially prevent an unpleasant surprise when your tax return is prepared.
Am I above the income limit for making a direct Roth IRA contribution?
How much am I eligible to contribute to an IRA this year?
Do I have any Traditional IRAs or Rollover IRAs?
Do I have a SEP IRA or SIMPLE IRA?
Do I have existing nondeductible IRA basis from prior years?
Have I reviewed the Backdoor Roth IRA pro-rata calculation before converting?
Could investment gains occur before the Roth conversion?
Will IRS Form 8606 be properly prepared with my tax return?
Does my employer's 401(k) accept incoming IRA rollovers?
Should I review the strategy with my CPA before completing the transaction?
The more complicated your retirement-account history is, the more important this review becomes. A forgotten Rollover IRA or old SEP IRA can materially change the tax result of a Backdoor Roth IRA conversion.
The Backdoor Roth IRA Can Still Be a Powerful Strategy
None of these potential mistakes mean that investors should avoid Backdoor Roth IRAs. For the right individual, the strategy can be an excellent way to accumulate Roth assets when income prevents a direct Roth IRA contribution. Once assets are successfully inside a Roth IRA, they have the potential to grow tax-deferred, and qualified Roth IRA distributions can ultimately be tax-free.
The biggest issue is not necessarily choosing the wrong investment. It is assuming the transaction is simpler than it actually is. Before making the contribution, understand the aggregation rule; before making the conversion, understand what portion may be taxable; and after completing the transaction, make sure the tax reporting is handled properly.
The Backdoor Roth IRA strategy is often described as a simple two-step process: make a nondeductible Traditional IRA contribution and then convert it to a Roth IRA. In reality, several important tax rules sit underneath those two steps. The goal is not simply to get money into the Roth IRA—it is to get the money into the Roth IRA correctly.
About Michael……...
Hi, I’m Michael Ruger. I’m the managing partner of Greenbush Financial Group and the creator of the nationally recognized Money Smart Board blog . I created the blog because there are a lot of events in life that require important financial decisions. The goal is to help our readers avoid big financial missteps, discover financial solutions that they were not aware of, and to optimize their financial future.
Frequently Asked Questions About Backdoor Roth IRAs
-
1. What is a Backdoor Roth IRA?A Backdoor Roth IRA is a strategy commonly used by higher-income individuals who are not eligible to contribute directly to a Roth IRA. The strategy generally involves making a nondeductible contribution to a Traditional IRA and then converting those assets to a Roth IRA. It is not a separate type of retirement account; it is simply a series of transactions using existing IRA rules.
-
2. Is a Backdoor Roth IRA legal?Backdoor Roth IRA strategies use existing rules that allow nondeductible Traditional IRA contributions and Roth IRA conversions. There is no income limit on Roth conversions, even though income limits apply to direct Roth IRA contributions. However, the tax consequences can become complicated when an individual has other pre-tax IRA assets, so proper execution and reporting are important.
-
3. What is the Backdoor Roth IRA pro-rata rule?The Backdoor Roth IRA pro-rata rule determines how much of a Roth conversion is taxable when you have both pre-tax and after-tax money in your applicable IRAs. You generally cannot choose to convert only the after-tax dollars while leaving all of the pre-tax money untouched for tax purposes. Instead, the taxable and nontaxable portions are determined proportionately based on your overall IRA balances and basis.
-
4. Which IRA accounts are included in the Backdoor Roth IRA aggregation rule?Traditional IRAs, Rollover IRAs, Traditional SEP IRAs, and Traditional SIMPLE IRAs generally need to be considered when calculating the taxable portion of an IRA distribution or Roth conversion. Keeping these accounts at different financial institutions does not necessarily allow you to avoid the aggregation rule. This is why identifying all of your IRA balances before executing a Backdoor Roth IRA is so important.
-
5. Does a 401(k) count toward the Backdoor Roth IRA pro-rata rule?Generally, assets held inside a 401(k) are not included in the IRA aggregation calculation simply because they are pre-tax retirement assets. This can be an important distinction for individuals with large 401(k) balances but no pre-tax Traditional, Rollover, SEP, or SIMPLE IRA assets. In some situations, rolling eligible IRA assets into an employer 401(k) that accepts incoming rollovers may also help with future Backdoor Roth IRA planning.
-
6. How long should I wait between a Traditional IRA contribution and Roth conversion?There is no specific IRS rule establishing a required 30-day, 60-day, or 90-day waiting period between a nondeductible Traditional IRA contribution and a Roth conversion. Although the step-transaction doctrine has historically generated discussion around Backdoor Roth IRA timing, no specific waiting period creates an automatic safe harbor. Individuals concerned about how the doctrine may apply to their situation should consult a tax professional.
-
7. Can I do a Backdoor Roth IRA if I already contribute to a Roth 401(k)?Yes. Roth 401(k) contributions and IRA contributions are subject to separate annual contribution limits. An individual may potentially maximize Roth 401(k) salary deferrals and separately make a nondeductible Traditional IRA contribution followed by a Roth conversion, assuming the individual otherwise qualifies and the strategy is appropriate.
-
8. Do I need to file Form 8606 for a Backdoor Roth IRA?Form 8606 is generally an important part of reporting a Backdoor Roth IRA because it tracks nondeductible Traditional IRA contributions and after-tax IRA basis. It is also used in reporting Roth conversions. Properly tracking basis helps prevent after-tax IRA money from potentially being taxed again when it is converted or later distributed.
-
9. Do I owe taxes on a Backdoor Roth IRA conversion?You may owe taxes on a Backdoor Roth IRA conversion depending on your other IRA balances and whether the contribution generated earnings before the conversion. If you have no other pre-tax IRA assets and convert a nondeductible contribution before significant gains occur, the taxable amount may be small or potentially zero. If you have substantial pre-tax Traditional, Rollover, SEP, or SIMPLE IRA balances, however, the pro-rata rule can cause a large portion of the conversion to become taxable.
-
10. Can I do a Backdoor Roth IRA every year?Potentially, yes. Individuals who continue to meet the requirements for making an IRA contribution may be able to repeat the Backdoor Roth IRA strategy in multiple years. However, the pro-rata rule, IRA balances, contribution limits, tax laws, and reporting requirements should be reviewed each year because a strategy that worked cleanly one year may have different tax consequences in a later year.
Roth Conversions In Retirement
Roth conversions in retirement are becoming a very popular tax strategy. It can help you to realize income at a lower tax rate, reduce your RMD’s, accumulate assets tax free, and pass Roth money onto your beneficiaries. However, there are pros and cons that you need to be aware of, because processing a Roth conversion involves showing more taxable income in a given year. Without proper tax planning, it could lead to unintended financial consequences such as:
· Social Security taxed at a higher rate
· Higher Medicare premiums
· Assets lost to a long term care event
· Higher taxes on long term capital gains
· Losing tax deductions and credits
· Higher property taxes
· Unexpected big tax liability
In this video, Michael Ruger will walk you through some of the strategies that he uses with his clients when implementing Roth Conversions. This can be a very effective wealth building strategy when used correctly.

About Michael……...
Hi, I’m Michael Ruger. I’m the managing partner of Greenbush Financial Group and the creator of the nationally recognized Money Smart Board blog . I created the blog because there are a lot of events in life that require important financial decisions. The goal is to help our readers avoid big financial missteps, discover financial solutions that they were not aware of, and to optimize their financial future.