Common Backdoor Roth IRA Mistakes
A Backdoor Roth IRA can help high-income earners build tax-free retirement savings, but mistakes with the pro-rata rule, IRA balances, Form 8606, and conversion timing can create unexpected taxes. Learn the most common mistakes to avoid.
By Michael Ruger, CFP®
Partner and Chief Investment Officer at Greenbush Financial Group
The Backdoor Roth IRA strategy has become increasingly common among higher-income individuals who earn too much to make a direct contribution to a Roth IRA. The concept sounds relatively simple: make a nondeductible contribution to a Traditional IRA and then convert that money to a Roth IRA. Because there is no income limitation on Roth IRA conversions, this strategy can potentially allow higher-income taxpayers to continue building Roth assets even when their income prevents them from contributing directly to a Roth IRA.
However, simple does not always mean easy. We are seeing a growing number of mistakes in the execution of Backdoor Roth IRA strategies, and some of those mistakes can create unexpected taxable income, additional tax filings, and other complications.
In this article, we will cover some of the most common Backdoor Roth IRA mistakes, including:
How the Backdoor Roth IRA strategy works for high-income earners
How the Backdoor Roth IRA aggregation rule can create unexpected taxes
Why Traditional IRA, Rollover IRA, SEP IRA, and SIMPLE IRA balances can affect a Roth conversion
What investors should know about the Backdoor Roth IRA step-transaction rule
Why a Roth 401(k) does not prevent you from completing a Backdoor Roth IRA
Why IRS Form 8606 is critical when making nondeductible IRA contributions
How investment gains before a Roth conversion can create taxable income
How to avoid common Backdoor Roth IRA tax mistakes before executing the strategy
Understanding these rules before you move any money can make a significant difference. A Backdoor Roth IRA can be a powerful retirement planning strategy, but the tax treatment depends heavily on how the transaction is executed.
What Is a Backdoor Roth IRA?
A Backdoor Roth IRA is not a special type of retirement account. It is simply a strategy that generally involves making a nondeductible contribution to a Traditional IRA and then converting those assets to a Roth IRA. The strategy is primarily used by individuals whose income is too high to make a direct Roth IRA contribution.
For 2026, the Roth IRA contribution phaseout range is $153,000 to $168,000 for single filers and heads of household and $242,000 to $252,000 for married couples filing jointly. The 2026 IRA contribution limit is $7,500 for individuals under age 50 and $8,600 for individuals age 50 or older. While there are income limits that determine whether you can contribute directly to a Roth IRA, there is no similar income limitation that prevents an individual from converting Traditional IRA assets to a Roth IRA.
That difference is what makes the Backdoor Roth IRA strategy possible. Instead of contributing directly to a Roth IRA, the individual contributes after-tax money to a Traditional IRA and later converts that money to a Roth IRA. If the strategy is properly executed and the individual has no other pre-tax IRA money, the tax consequences of the conversion may be minimal or potentially zero.
Mistake #1: Ignoring the IRA Aggregation and Pro-Rata Rule
The IRA aggregation rule, also commonly called the pro-rata rule, is probably the most important Backdoor Roth IRA mistake to understand. Many investors assume that if they open a brand-new Traditional IRA, contribute after-tax money to that account, and convert only that account to a Roth IRA, the conversion will automatically be tax-free. Unfortunately, that is not always how the tax calculation works.
For purposes of determining how much of an IRA conversion is taxable versus nontaxable, the IRS generally does not allow you to isolate your nondeductible contribution from your other Traditional IRA money. Instead, applicable Traditional IRA balances are aggregated together when determining what percentage of the conversion represents pre-tax money and what percentage represents after-tax basis. This generally includes Traditional IRAs, Rollover IRAs, Traditional SEP IRAs, and Traditional SIMPLE IRAs.
A Simple $100,000 Backdoor Roth IRA Example
Assume John already has a Traditional IRA worth $95,000, and all $95,000 is pre-tax money. John then opens a separate Traditional IRA, contributes $5,000 to it, and does not take a tax deduction for that contribution. A few days later, he converts the entire $5,000 from the new Traditional IRA into his Roth IRA.
John may assume that because he contributed $5,000 of after-tax money and converted that same $5,000, the conversion should be tax-free. However, when the aggregation rule is applied, John effectively has $100,000 of total IRA money for purposes of this simplified example: $95,000 of pre-tax money and $5,000 of after-tax basis.
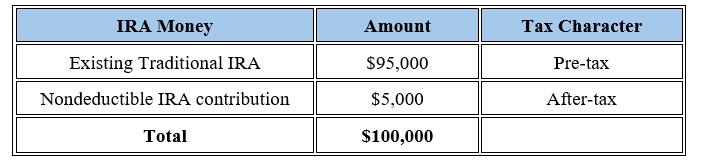
In this example, only 5% of John's IRA money represents after-tax basis, while 95% represents pre-tax money. Therefore, approximately 95% of the $5,000 Roth conversion would be taxable, or roughly $4,750. Only about $250 of the conversion would represent a nontaxable recovery of basis.
This is where many individuals get surprised. They believed they completed a tax-free $5,000 conversion, but because of the other pre-tax IRA assets, most of the conversion becomes taxable.
Opening a Separate IRA Does Not Avoid the Aggregation Rule
Another common misconception is that the aggregation rule can be avoided simply by opening a separate IRA at another financial institution. For example, someone may have a $500,000 Rollover IRA at one investment company and decide to open a brand-new Traditional IRA somewhere else specifically for the Backdoor Roth IRA strategy. Unfortunately, keeping the accounts physically separate does not necessarily separate them for tax purposes.
The same issue applies if one account is labeled a "Backdoor Roth IRA account." The IRS is generally looking at the applicable IRA balances collectively when determining the taxable portion of a distribution or conversion. Before executing a Backdoor Roth IRA, it is important to identify all existing Traditional, Rollover, SEP, and SIMPLE IRA balances that could potentially affect the calculation.
What About Money in a 401(k)?
A 401(k) is treated differently from an IRA for purposes of the Backdoor Roth aggregation calculation. Simply having a large balance in a current employer's 401(k) does not by itself create the same pro-rata problem. For example, an individual could have $800,000 in a pre-tax 401(k), no Traditional IRA balances, and still potentially execute a relatively clean Backdoor Roth IRA strategy.
This distinction can sometimes create planning opportunities. In certain situations, an employer's 401(k) may accept a rollover of pre-tax IRA assets, which could potentially move those assets out of the IRA aggregation calculation before year-end. However, that decision should not be made solely for tax convenience because investment choices, fees, creditor protections, withdrawal provisions, and other plan features should also be considered.
Mistake #2: Misunderstanding the Step-Transaction Concern
The second major issue surrounding Backdoor Roth IRAs involves what is commonly called the step-transaction doctrine. Very generally, this is a tax principle under which a series of formally separate transactions may, under certain circumstances, be viewed together based on their substance. Historically, this created concern that making a nondeductible Traditional IRA contribution and immediately converting it to a Roth IRA could potentially be viewed as an indirect way of making a Roth contribution that the individual was not otherwise eligible to make directly.
That concern has led to a lot of informal advice over the years suggesting that taxpayers should wait some period of time between making the nondeductible IRA contribution and completing the Roth conversion. You may hear recommendations to wait 30 days, 60 days, or 90 days. The important point is that there is no specific IRS safe harbor stating that waiting a particular number of days makes the strategy automatically protected from the step-transaction doctrine.
Current IRS guidance recognizes both nondeductible Traditional IRA contributions and Roth IRA conversions, and Roth conversions are not subject to the same income limits that apply to direct Roth IRA contributions. Therefore, we would be careful about presenting any specific waiting period as an IRS requirement. If you have concerns about how the step-transaction doctrine could apply to your specific situation, that is an issue to discuss with your CPA or tax attorney.
Waiting Can Create Another Backdoor Roth IRA Issue
There is another reason why blindly waiting 60 or 90 days is not necessarily the perfect solution. If the money inside the Traditional IRA is invested during that waiting period, the account could increase in value before the Roth conversion occurs. Those investment gains may create taxable income when the money is eventually converted.
For example, assume you make a $7,500 nondeductible contribution to a Traditional IRA and invest the money immediately. Over the next 90 days, the account grows to $7,900. If you then convert the entire $7,900 to the Roth IRA and you have no other IRA balances or basis, you generally have only $7,500 of after-tax basis, meaning the additional $400 of investment growth may be taxable.
This does not necessarily make the Backdoor Roth IRA strategy unsuccessful. Paying tax on a few hundred dollars of gains may be relatively minor. However, it is another reason why the timing of the contribution, investment, and conversion should be intentional rather than based on an assumed 60- or 90-day IRS requirement.
Mistake #3: Thinking a Roth 401(k) Prevents a Backdoor Roth IRA
Another common misconception is that someone who is already contributing to a Roth 401(k) cannot also execute a Backdoor Roth IRA strategy. That is not the case. Roth 401(k) contributions and IRA contributions are governed by separate annual contribution limits.
For example, assume a 45-year-old high-income employee is maxing out their Roth 401(k). For 2026, that individual could potentially contribute $24,500 to the Roth 401(k) and separately make a $7,500 nondeductible contribution to a Traditional IRA, followed by a Roth conversion, assuming the strategy is otherwise appropriate. The fact that both strategies involve Roth accounts does not cause the limits to overlap.
This can be especially valuable for higher-income households that are trying to accumulate more tax-free retirement assets. Someone who is already maximizing Roth 401(k) contributions may still have the opportunity to add additional money to a Roth IRA through the Backdoor Roth IRA strategy.
Mistake #4: Forgetting to File Form 8606
Form 8606 is one of the most important pieces of paperwork associated with a Backdoor Roth IRA. When you make a nondeductible contribution to a Traditional IRA, you need a tax record establishing that you did not take a deduction for that contribution and that the money represents after-tax basis. Without proper documentation, it may become much more difficult to prove years later how much of your IRA has already been taxed.
The IRS uses Form 8606 to report nondeductible Traditional IRA contributions, certain IRA distributions when basis exists, and conversions from Traditional IRAs to Roth IRAs. In practical terms, Form 8606 helps prevent you from potentially paying tax twice on the same money. If you contribute $7,500 to a Traditional IRA and do not claim a deduction, you do not want that same $7,500 to be treated as fully taxable when it is later converted or distributed.
This is why properly filing Form 8606 is not simply a minor administrative step. It is part of keeping an accurate tax record of your after-tax IRA basis. Individuals who execute Backdoor Roth IRA strategies year after year should pay close attention to making sure Form 8606 is prepared correctly each year.
Mistake #5: Forgetting About an Old SEP IRA or SIMPLE IRA
One of the easiest mistakes to make is forgetting about an old retirement account from years ago. Someone may currently be a W-2 employee with no obvious Traditional IRA or Rollover IRA and assume that their Backdoor Roth IRA will be straightforward. However, they may have opened a SEP IRA or SIMPLE IRA years earlier when they were self-employed or worked for a different company.
If that account still contains pre-tax money, it may affect the pro-rata calculation. For example, an old $80,000 SEP IRA sitting at another custodian may suddenly become very relevant when determining how much of a current Roth conversion is taxable.
This is why we recommend completing a retirement-account inventory before implementing the strategy. Do not simply ask whether you have a Traditional IRA. Ask whether you have any Traditional, Rollover, SEP, or SIMPLE IRA balances that could impact the calculation.
Mistake #6: Confusing the IRA Contribution Limit With the Roth Conversion Limit
Another common misunderstanding is assuming that if the annual IRA contribution limit is $7,500, then the maximum Roth conversion is also $7,500. Those are two completely different rules. The annual contribution limit determines how much new money can be contributed to an IRA, while a Roth conversion involves moving existing Traditional IRA assets into a Roth IRA.
For example, someone could make a $7,500 nondeductible Traditional IRA contribution and separately decide to convert $100,000 of existing pre-tax IRA assets to a Roth IRA. There is no general $7,500 annual limit on Roth conversions. However, converting pre-tax retirement assets to a Roth IRA generally creates taxable income, which means large conversions require careful tax planning.
This distinction is important because the Backdoor Roth IRA strategy involves both a contribution and a conversion. The contribution limit applies to the first step. The tax consequences of the conversion depend on the character of the money being converted and the individual's overall IRA situation.
A Backdoor Roth IRA Pre-Flight Checklist
Before executing a Backdoor Roth IRA, it can help to work through a short checklist. A few minutes spent reviewing your accounts before making the contribution or conversion can potentially prevent an unpleasant surprise when your tax return is prepared.
Am I above the income limit for making a direct Roth IRA contribution?
How much am I eligible to contribute to an IRA this year?
Do I have any Traditional IRAs or Rollover IRAs?
Do I have a SEP IRA or SIMPLE IRA?
Do I have existing nondeductible IRA basis from prior years?
Have I reviewed the Backdoor Roth IRA pro-rata calculation before converting?
Could investment gains occur before the Roth conversion?
Will IRS Form 8606 be properly prepared with my tax return?
Does my employer's 401(k) accept incoming IRA rollovers?
Should I review the strategy with my CPA before completing the transaction?
The more complicated your retirement-account history is, the more important this review becomes. A forgotten Rollover IRA or old SEP IRA can materially change the tax result of a Backdoor Roth IRA conversion.
The Backdoor Roth IRA Can Still Be a Powerful Strategy
None of these potential mistakes mean that investors should avoid Backdoor Roth IRAs. For the right individual, the strategy can be an excellent way to accumulate Roth assets when income prevents a direct Roth IRA contribution. Once assets are successfully inside a Roth IRA, they have the potential to grow tax-deferred, and qualified Roth IRA distributions can ultimately be tax-free.
The biggest issue is not necessarily choosing the wrong investment. It is assuming the transaction is simpler than it actually is. Before making the contribution, understand the aggregation rule; before making the conversion, understand what portion may be taxable; and after completing the transaction, make sure the tax reporting is handled properly.
The Backdoor Roth IRA strategy is often described as a simple two-step process: make a nondeductible Traditional IRA contribution and then convert it to a Roth IRA. In reality, several important tax rules sit underneath those two steps. The goal is not simply to get money into the Roth IRA—it is to get the money into the Roth IRA correctly.
About Michael……...
Hi, I’m Michael Ruger. I’m the managing partner of Greenbush Financial Group and the creator of the nationally recognized Money Smart Board blog . I created the blog because there are a lot of events in life that require important financial decisions. The goal is to help our readers avoid big financial missteps, discover financial solutions that they were not aware of, and to optimize their financial future.
Frequently Asked Questions About Backdoor Roth IRAs
-
1. What is a Backdoor Roth IRA?A Backdoor Roth IRA is a strategy commonly used by higher-income individuals who are not eligible to contribute directly to a Roth IRA. The strategy generally involves making a nondeductible contribution to a Traditional IRA and then converting those assets to a Roth IRA. It is not a separate type of retirement account; it is simply a series of transactions using existing IRA rules.
-
2. Is a Backdoor Roth IRA legal?Backdoor Roth IRA strategies use existing rules that allow nondeductible Traditional IRA contributions and Roth IRA conversions. There is no income limit on Roth conversions, even though income limits apply to direct Roth IRA contributions. However, the tax consequences can become complicated when an individual has other pre-tax IRA assets, so proper execution and reporting are important.
-
3. What is the Backdoor Roth IRA pro-rata rule?The Backdoor Roth IRA pro-rata rule determines how much of a Roth conversion is taxable when you have both pre-tax and after-tax money in your applicable IRAs. You generally cannot choose to convert only the after-tax dollars while leaving all of the pre-tax money untouched for tax purposes. Instead, the taxable and nontaxable portions are determined proportionately based on your overall IRA balances and basis.
-
4. Which IRA accounts are included in the Backdoor Roth IRA aggregation rule?Traditional IRAs, Rollover IRAs, Traditional SEP IRAs, and Traditional SIMPLE IRAs generally need to be considered when calculating the taxable portion of an IRA distribution or Roth conversion. Keeping these accounts at different financial institutions does not necessarily allow you to avoid the aggregation rule. This is why identifying all of your IRA balances before executing a Backdoor Roth IRA is so important.
-
5. Does a 401(k) count toward the Backdoor Roth IRA pro-rata rule?Generally, assets held inside a 401(k) are not included in the IRA aggregation calculation simply because they are pre-tax retirement assets. This can be an important distinction for individuals with large 401(k) balances but no pre-tax Traditional, Rollover, SEP, or SIMPLE IRA assets. In some situations, rolling eligible IRA assets into an employer 401(k) that accepts incoming rollovers may also help with future Backdoor Roth IRA planning.
-
6. How long should I wait between a Traditional IRA contribution and Roth conversion?There is no specific IRS rule establishing a required 30-day, 60-day, or 90-day waiting period between a nondeductible Traditional IRA contribution and a Roth conversion. Although the step-transaction doctrine has historically generated discussion around Backdoor Roth IRA timing, no specific waiting period creates an automatic safe harbor. Individuals concerned about how the doctrine may apply to their situation should consult a tax professional.
-
7. Can I do a Backdoor Roth IRA if I already contribute to a Roth 401(k)?Yes. Roth 401(k) contributions and IRA contributions are subject to separate annual contribution limits. An individual may potentially maximize Roth 401(k) salary deferrals and separately make a nondeductible Traditional IRA contribution followed by a Roth conversion, assuming the individual otherwise qualifies and the strategy is appropriate.
-
8. Do I need to file Form 8606 for a Backdoor Roth IRA?Form 8606 is generally an important part of reporting a Backdoor Roth IRA because it tracks nondeductible Traditional IRA contributions and after-tax IRA basis. It is also used in reporting Roth conversions. Properly tracking basis helps prevent after-tax IRA money from potentially being taxed again when it is converted or later distributed.
-
9. Do I owe taxes on a Backdoor Roth IRA conversion?You may owe taxes on a Backdoor Roth IRA conversion depending on your other IRA balances and whether the contribution generated earnings before the conversion. If you have no other pre-tax IRA assets and convert a nondeductible contribution before significant gains occur, the taxable amount may be small or potentially zero. If you have substantial pre-tax Traditional, Rollover, SEP, or SIMPLE IRA balances, however, the pro-rata rule can cause a large portion of the conversion to become taxable.
-
10. Can I do a Backdoor Roth IRA every year?Potentially, yes. Individuals who continue to meet the requirements for making an IRA contribution may be able to repeat the Backdoor Roth IRA strategy in multiple years. However, the pro-rata rule, IRA balances, contribution limits, tax laws, and reporting requirements should be reviewed each year because a strategy that worked cleanly one year may have different tax consequences in a later year.




Trump Accounts For Minor Children Explained: A New Wealth-Building Opportunity
Trump Accounts are a new retirement savings vehicle created under the 2025 tax reform that allow parents, grandparents, and even employers to contribute up to $5,000 per year for a minor child — even if the child has no earned income. In this article, we explain how Trump Accounts work, contribution limits, tax rules, planning opportunities, and the key considerations to understand before opening one.
By Michael Ruger, CFP®
Partner and Chief Investment Officer at Greenbush Financial Group
Over the past several months, we’ve received a lot of questions from parents and grandparents about the new Trump Accounts created under the 2025 tax reform. Most of those questions fall into a few clear categories:
How do Trump Accounts get set up?
Who can fund them, and how much can be contributed?
What makes them different from traditional or Roth IRAs?
And most importantly—are they really worth it?
What’s driving so much interest is that these accounts can be a tremendous long-term wealth-building opportunity for children and grandchildren. Unlike traditional or Roth IRAs, which require earned income to contribute, Trump Accounts allow up to $5,000 per year in contributions even if the child has no income at all. That creates decades of potential tax-deferred compounding.
That said, Trump Accounts also come with a unique set of rules, especially while the account owner is a minor. In this article, we’ll break down how Trump Accounts work, how they’re funded, how they interact with other retirement accounts, and where the real planning opportunities—and responsibilities—exist.
What Is a Trump Account?
A Trump Account is a new type of retirement account designed specifically for minors, created as part of the One Big Beautiful Bill Act of 2025. Conceptually, it is built on the framework of a traditional IRA, but with special rules that apply from birth through age 17.
The goal of these accounts is simple: to jump-start retirement savings as early as possible, even before a child has their first job.
Contribution Limits and Funding Rules
Annual Contribution Limits
Total annual contributions are limited to $5,000 per year
Of that amount, up to $2,500 may come from an employer
These limits apply beginning in 2026 and will be indexed for inflation in future years
Who Can Contribute?
Trump Accounts can receive contributions from several sources:
Parents, grandparents, or other individuals (after-tax)
Employers (pre-tax)
Government or charitable entities (pre-tax)
A one-time $1,000 federal government contribution for eligible children
Importantly, individual contributions are made with after-tax dollars, meaning they create “basis” in the account, while employer and government contributions are pre-tax.
The $1,000 Government Contribution
As part of a pilot program, the federal government will contribute $1,000 to a Trump Account for children born between 2025 and 2028, provided the parent or guardian opts in.
Key points:
The contribution is pre-tax
It does not count toward the $5,000 annual limit
Parents must actively elect the contribution—it is not automatic
This is essentially “free money,” and for many families, that alone may justify opening the account.
How Trump Accounts Can Be Invested
Trump Accounts have very strict investment rules:
Accounts must be established with initial trustees selected by the U.S. Treasury
Individuals may have only one Trump Account
Investments are limited to unleveraged mutual funds or ETFs
The investments must track a qualified index of primarily U.S. equities
Holding cash is virtually not allowed
Total investment fees cannot exceed 0.10%
At this time, the list of approved custodians has not yet been released, and is expected sometime in 2026.
How and When Trump Accounts Are Set Up
Trump Accounts cannot be opened with a traditional custodian yet.
Here’s what we know about the setup process:
Accounts become operational starting July 4, 2026
All accounts must initially be opened using U.S. Treasury–approved trustees
A new IRS Form 4547 and an online application at trumpaccounts.gov are expected to launch in mid-2026
To establish the accounts Form 4547 or the special application can be submitted prior to the July 4, 2026 program launch date
That same process will be used to request the $1,000 government contribution
Once established, families can begin making annual contributions.
Special Rule for Working Minors
One of the most powerful planning features applies to minors who do have earned income.
If a child earns income:
They can contribute to a Trump Account
They can also contribute to a traditional IRA or Roth IRA
The contribution limits do not reduce or affect one another
In other words, a working minor can fund both account types in the same year, creating even more long-term compounding potential.
Roth Conversion Opportunity After Age 18
Once the account owner turns 18, Trump Accounts largely revert to standard traditional IRA rules.
This is where advanced planning opportunities emerge:
It can then be converted to a Roth IRA
Once converted, future growth and qualified withdrawals may be tax-free
However, there’s an important catch.
Tracking Basis Is Critical
Individual contributions were made with after-tax dollars
Employer and government contributions are pre-tax
Investment growth is pre-tax
This creates a mixed-tax account, requiring careful basis tracking over time. If records aren’t maintained, the IRS may treat withdrawals as fully taxable.
Beware of Kiddie Tax: Roth conversions trigger a taxable event for any pre-tax contributions or earnings held within the Trump Account. Conversions and distributions from IRAs are considered unearned income of the minor child, which can trigger the Kiddie tax, making the taxable distribution amount subject to tax at the parent’s tax rate instead of the child’s.
Employer Contributions Are Allowed
Employers are permitted to contribute to Trump Accounts:
Contributions are pre-tax
They may be made for the employee or the employee’s dependent child
Employer contributions count toward the $5,000 annual limit (up to $2,500)
This opens the door for unique employer-based benefits and planning strategies.
How Trump Account Distributions Work After Age 18
Once a child reaches age 18, Trump Accounts undergo an important transition. While these accounts are designed for minors, the distribution rules after age 18 closely resemble those of a traditional IRA, which introduces both flexibility and responsibility.
Understanding how distributions work at this stage is critical, because mistakes can create unnecessary taxes or penalties.
No Distributions Before Age 18
First, it’s important to note that Trump Accounts do not allow distributions prior to age 18. Until then, the account is strictly a long-term retirement vehicle.
Once the account owner reaches the year they turn 18, distributions become available—but that does not mean they are penalty-free.
Traditional IRA Rules Apply After Age 18
Beginning in the year the child turns 18, the Trump Account is treated much like a traditional IRA for tax purposes. That means:
Distributions are generally taxable
Early withdrawals may be subject to a 10% penalty
The account follows pro-rata taxation rules if it contains both after-tax and pre-tax money
How Distributions Are Taxed
Trump Accounts typically hold two types of money:
After-tax contributions (from parents, grandparents, or others)
Pre-tax dollars, which include:
Employer contributions
Government contributions (including the $1,000 pilot contribution)
All investment growth
When a distribution is taken, the IRS does not allow the account owner to choose which dollars come out. Instead, each withdrawal is treated as a proportional mix of taxable and non-taxable funds.
Example (Simplified)
If 25% of the account consists of after-tax contributions, then:
25% of any distribution is tax-free
75% is taxable as ordinary income
This makes accurate recordkeeping essential, since the after-tax portion (known as “basis”) must be documented to avoid overpaying taxes.
Early Withdrawal Penalties Still Apply
Although distributions are allowed after age 18, they are not automatically penalty-free.
Withdrawals before age 59½ generally incur a 10% early withdrawal penalty
Certain exceptions may apply, such as:
Qualified higher education expenses
Limited first-time home purchase expenses
Certain structured payment arrangements
Absent one of these exceptions, both income taxes and penalties may apply.
Rollovers and Roth Conversions Instead of Distributions
Rather than taking cash distributions, many families will focus on rollovers and Roth conversions, which are allowed once the account owner turns 18.
At that point:
The Trump Account can be rolled into a traditional IRA
It may then be converted to a Roth IRA
A Roth conversion is taxable on the pre-tax portion of the account, but once completed, future growth and qualified withdrawals can be tax-free.
This strategy can be especially powerful if conversions are done during low-income years, though taxes still must be paid—ideally using funds outside the account to avoid penalties.
Final Thoughts
Trump Accounts represent a powerful but complex planning tool. For families focused on long-term retirement wealth for children or grandchildren, they offer an early start that was never possible before. However, the rules around taxation, investment limitations, and recordkeeping mean these accounts should be used strategically, not blindly.
As always, thoughtful planning—and understanding how these accounts fit into the bigger financial picture—makes all the difference.
About Michael……...
Hi, I’m Michael Ruger. I’m the managing partner of Greenbush Financial Group and the creator of the nationally recognized Money Smart Board blog . I created the blog because there are a lot of events in life that require important financial decisions. The goal is to help our readers avoid big financial missteps, discover financial solutions that they were not aware of, and to optimize their financial future.
Frequently Asked Questions (FAQ)
1. Do children need earned income to have a Trump Account?
No. Earned income is not required.
2. Are contributions tax-deductible?
Individual contributions are not deductible. Employer and government contributions are pre-tax.
3. Can grandparents contribute?
Yes, as long as total annual limits are respected.
4. Can a child have more than one Trump Account?
No. Only one account per individual is allowed.
5. When can withdrawals be taken?
Distributions follow traditional IRA rules and generally are penalty-free after age 59½.
6. Are Roth conversions allowed?
Yes, starting at age 18 once the account follows IRA rules.
7. Are these accounts required to invest in stocks?
Yes. Investments must track qualified U.S. equity indexes.
8. Is the $1,000 government contribution automatic?
No. Parents must opt in using the IRS process.

Retirement Tax Traps and Penalties: 5 Gotchas That Catch People Off Guard
Even the most disciplined retirees can be caught off guard by hidden tax traps and penalties. Our analysis highlights five of the biggest “retirement gotchas” — including Social Security taxes, Medicare IRMAA surcharges, RMD penalties, the widow’s penalty, and state-level tax surprises. Learn how to anticipate these costs and plan smarter to preserve more of your retirement income.
Even the most disciplined savers can be blindsided in retirement by unexpected taxes, penalties, and benefit reductions that derail a carefully built plan. These “retirement gotchas” often appear subtle during your working years but can cost tens of thousands once you stop earning a paycheck.
Here are five of the biggest surprises retirees face—and how to avoid them before it’s too late.
1. The Tax Torpedo from Social Security
Many retirees are surprised to learn that Social Security isn’t always tax-free. Depending on your income, up to 85% of your benefit can be taxed.
The IRS uses something called “provisional income,” which includes half your Social Security benefit plus all other taxable income and tax-free municipal bond interest.
For individuals, taxes begin when provisional income exceeds $25,000.
For married couples, it starts at $32,000.
A well-intentioned IRA withdrawal or capital gain can push you over these thresholds—causing a sudden jump in taxes. Strategic Roth conversions and careful withdrawal sequencing can help smooth this out over time.
2. Higher Medicare Premiums (IRMAA)
The Income-Related Monthly Adjustment Amount (IRMAA) is one of the most overlooked retirement costs. Once your modified adjusted gross income (MAGI) exceeds certain limits, your Medicare Part B and D premiums increase—often by thousands of dollars per year.
For 2025, IRMAA surcharges begin when MAGI exceeds roughly $103,000 for single filers or $206,000 for married couples. The catch? Medicare looks back two years at your income. A Roth conversion, property sale, or large one-time distribution can unexpectedly trigger higher premiums two years later.
Proactive tax planning can prevent crossing these thresholds unintentionally.
3. Required Minimum Distributions (RMDs)
Once you reach age 73, the IRS requires you to start withdrawing from pre-tax retirement accounts each year—whether you need the money or not. These RMDs are taxed as ordinary income and can increase your tax bracket, raise Medicare premiums, and reduce your eligibility for certain deductions.
The biggest mistake is waiting until your 70s to plan for them. Roth conversions in your 60s can reduce future RMDs, and charitable giving through Qualified Charitable Distributions (QCDs) can offset the tax impact once they begin.
4. The Widow’s Penalty
When one spouse passes away, the surviving spouse’s tax brackets and standard deduction are cut in half—but income sources often don’t decrease proportionally. Social Security may drop by one benefit, but RMDs, pensions, and investment income remain largely the same.
The result is a higher effective tax rate for the survivor. This “widow’s penalty” can last for years, especially when combined with RMDs and Medicare surcharges. Couples can reduce the long-term impact through lifetime Roth conversions, strategic asset titling, and beneficiary planning.
5. State Taxes and Hidden Relocation Costs
Many retirees move to lower-tax states hoping to stretch their income, but state-level taxes can be tricky. Some states tax pension and IRA withdrawals, others tax Social Security, and a few impose taxes on out-of-state income or estates.
Additionally, higher property taxes, insurance premiums, and healthcare costs can offset income tax savings. A comprehensive cost-of-living comparison is essential before relocating.
Our analysis at Greenbush Financial Group often reveals that the “best” retirement state depends more on quality of life, healthcare access and total cost of living than on income tax rates alone.
How to Avoid These Retirement Surprises
Most retirement gotchas come down to timing and coordination—especially between taxes, Social Security, and healthcare. A few key steps can make a major difference:
Run retirement income projections that include taxes and IRMAA thresholds.
Consider partial Roth conversions before RMD age.
Sequence withdrawals intentionally between taxable, tax-deferred, and Roth accounts.
Evaluate the long-term impact of home state taxes before moving.
Review beneficiary and trust structures regularly.
The earlier you identify potential traps, the easier they are to fix while you still control your income and withdrawals.
The Bottom Line
Retirement is more complex than simply replacing a paycheck. The interplay between taxes, healthcare, and income sources can turn small decisions into costly mistakes. By spotting these gotchas early, you can preserve more of your wealth and enjoy a smoother, more predictable retirement.
Our advisors at Greenbush Financial Group can help you identify your biggest risk areas and design a plan to minimize the tax and income surprises most retirees never see coming.
FAQs: Retirement Planning Surprises
Q: Are Social Security benefits always taxed?
A: No. But depending on your income, up to 85% of your benefits may be taxable.
Q: How can I avoid higher Medicare premiums?
A: Manage your income below IRMAA thresholds through strategic Roth conversions and tax-efficient withdrawals.
Q: What happens if I miss an RMD?
A: You could face a 25% penalty on the amount not withdrawn, reduced to 10% if corrected quickly.
Q: Why do widows and widowers pay more in taxes?
A: Filing status changes from joint to single, cutting brackets and deductions in half while much of the income remains.
Q: Are all retirement states tax-friendly?
A: No. Some states tax retirement income or have higher overall costs despite no income tax.
Rob Mangold
About Rob……...
Hi, I’m Rob Mangold. I’m the Chief Operating Officer at Greenbush Financial Group and a contributor to the Money Smart Board blog. We created the blog to provide strategies that will help our readers personally, professionally, and financially. Our blog is meant to be a resource. If there are questions that you need answered, please feel free to join in on the discussion or contact me directly.


How to Maximize Social Security Benefits with Smart Claiming and Income Planning
Social Security is a cornerstone of retirement income—but when and how you claim can have a major impact on lifetime benefits. This article from Greenbush Financial Group explains 2025 thresholds, how benefits are calculated, and smart strategies for delaying, coordinating with taxes, and managing Medicare costs. Learn how to maximize your Social Security benefits and plan your income efficiently in retirement.
By Michael Ruger, CFP®
Partner and Chief Investment Officer at Greenbush Financial Group
For many retirees, Social Security is a cornerstone of their retirement income. But when and how you claim your benefits—and how you plan your income around them—can have a major impact on the total amount you receive over your lifetime. With updated Social Security thresholds, limits, and rules, there are new opportunities to optimize your claiming strategy and coordinate Social Security with your broader financial plan.
In this article, we’ll cover:
How Social Security benefits are calculated and funded
Four ways to increase your Social Security benefit amount
How income and taxes affect your benefits
The impact of Medicare premiums and income planning
How delaying Social Security can create opportunities for Roth conversions
What to know about the earned income penalty if you claim early
Answers to common Social Security claiming questions
Maximizing Social Security During the Working Years
The foundation for a strong Social Security benefit starts during your working years. Understanding how the system works helps you make informed decisions about your career, income, and retirement planning.
How Social Security Is Funded and Calculated
Social Security is primarily funded through payroll taxes under the Federal Insurance Contributions Act (FICA). In 2025, workers and employers each pay 6.2% of wages (for a total of 12.4%) up to the taxable wage base, which is $176,000 in 2025. Any earnings above that amount are not subject to Social Security tax and do not increase your benefit.
Your benefit is based on your highest 35 years of indexed earnings—meaning each year’s income is adjusted for inflation to reflect its value in today’s dollars. If you worked fewer than 35 years, zeros are included in the calculation, which can significantly reduce your average and therefore your monthly benefit.
Key takeaway: Once your annual income exceeds the taxable wage base, additional earnings don’t raise your future Social Security benefit. However, working longer can still increase your benefit if you replace lower-earning years or zeros in your 35-year average.
Four Ways to Increase Your Social Security Benefits
1. Fill in or Replace Zero Years
If you have fewer than 35 years of work history, each missing year is counted as zero. Even one extra year of income can replace a zero and raise your benefit.
Example: If you worked 32 years and earned $80,000 annually in your final three years, adding those years could significantly boost your benefit calculation.
2. Delay Claiming to Earn Higher Benefits
You can claim Social Security as early as age 62, but doing so permanently reduces your benefit—up to 30% less than your full retirement age (FRA) amount. For those born in 1960 or later, FRA is 67.
If you wait past FRA, your benefit grows by 8% per year up to age 70, plus annual cost-of-living adjustments (COLAs).
Example:
Claiming at 62: $1,400/month
Claiming at 67: $2,000/month
Claiming at 70: $2,480/month
That’s a $1,080 per month difference for waiting between the ages of 62 and 70.
3. Maximize Spousal and Dependent Benefits
Spousal and dependent benefits can be valuable for married couples or retirees with young children.
Spousal Benefit: A spouse can claim up to 50% of the higher earner’s FRA benefit, provided the higher earner has already filed.
Divorced Spouse Benefit: You may qualify if the marriage lasted 10 years or longer, and you haven’t remarried prior to age 60.
Dependent Benefit: Retirees age 62+ with children under 18 may receive additional benefits for dependents.
Planning tip: For individuals who plan to utilize the 50% spousal benefit and/or the dependent benefit, the path to the optimal filing strategy is more complex because the spouse and dependents cannot receive these benefits until that individual has actually turned on their social security benefit, which, in some cases, can favor not waiting until age 70 to file.
4. Understand Survivor Benefits
If one spouse passes away, the surviving spouse receives the higher of the two benefits. This makes it especially beneficial for the higher-earning spouse to delay claiming to age 70, maximizing the survivor benefit and providing long-term income protection.
How Social Security Benefits Are Taxed
Up to 85% of your Social Security benefits may be taxable, depending on your combined income (adjusted gross income + nontaxable interest + half of your Social Security benefits).
Single filers: Taxes begin at $25,000 of combined income
Married filing jointly: Taxes begin at $32,000 of combined income
If you don’t need Social Security to cover living expenses right away, delaying benefits can not only increase your future income but may also help manage taxes by controlling your income levels in early retirement.
Medicare Premiums and Income Planning
Once you reach age 65, you’ll typically enroll in Medicare Part B and D, and your premiums are based on your Modified Adjusted Gross Income (MAGI). Higher income means higher premiums under the Income-Related Monthly Adjustment Amount (IRMAA) rules.
Because Social Security benefits count as income for these purposes, timing your claiming strategy can help you manage Medicare costs.
Roth Conversions: Turning Delay into an Opportunity
Delaying Social Security creates a window for Roth conversions—moving money from a traditional IRA to a Roth IRA at potentially lower tax rates before Required Minimum Distributions (RMDs) begin at age 73 or 75.
Benefits of Roth conversions include:
Paying tax now at potentially lower rates
Reducing future RMDs
Potentially reduce future Medicare premiums
Creating a tax-free income source in retirement
Leaving tax-free assets to heirs
Coordinating your claiming strategy with Roth conversions can improve long-term tax efficiency and enhance your retirement flexibility.
Claiming Early? Know the Earned Income Penalty
If you claim Social Security before full retirement age and continue to work, your benefits may be temporarily reduced.
In 2025, the earnings limit is $23,400. For every $2 earned over the limit, $1 in benefits is withheld.
In the year you reach FRA, a higher limit applies: $62,160, and only $1 is withheld for every $3 earned above that.
Once you reach full retirement age, the penalty disappears, and your benefit is recalculated to credit any withheld amounts.
About Michael……...
Hi, I’m Michael Ruger. I’m the managing partner of Greenbush Financial Group and the creator of the nationally recognized Money Smart Board blog . I created the blog because there are a lot of events in life that require important financial decisions. The goal is to help our readers avoid big financial missteps, discover financial solutions that they were not aware of, and to optimize their financial future.
Frequently Asked Questions (FAQ)
How are Social Security benefits calculated?
Social Security benefits are based on your highest 35 years of indexed earnings, adjusted for inflation. If you worked fewer than 35 years, zeros are included in your calculation, which can reduce your benefit.
What are the main ways to increase your Social Security benefits?
You can boost your benefit by replacing “zero” earning years, delaying your claim up to age 70 for an 8% annual increase past full retirement age, and coordinating spousal or survivor benefits strategically. Working longer and earning more during high-income years can also improve your benefit calculation.
How does delaying Social Security affect taxes and Medicare premiums?
Delaying benefits can help you manage taxable income in early retirement and avoid higher Medicare premiums triggered by the IRMAA income thresholds. This window can also allow for Roth conversions, which reduce future Required Minimum Distributions (RMDs) and create tax-free income in later years.
How are Social Security benefits taxed?
Up to 85% of your benefits may be taxable depending on your combined income (adjusted gross income + nontaxable interest + half of your benefits). Taxes begin at $25,000 for single filers and $32,000 for married couples filing jointly. Managing income sources can help minimize these taxes.
What is the earned income penalty for claiming Social Security early?
If you claim before full retirement age and continue working, benefits are reduced by $1 for every $2 earned above $23,400 in 2025. In the year you reach full retirement age, the limit increases to $62,160, and only $1 is withheld for every $3 earned over that amount. The penalty ends at full retirement age, when your benefit is recalculated.
What are spousal and survivor Social Security benefits?
A spouse can claim up to 50% of the higher earner’s full retirement benefit once that person has filed. If one spouse passes away, the survivor receives the higher of the two benefits. This makes it especially advantageous for the higher earner to delay claiming to age 70 to maximize long-term income protection.
How can Roth conversions complement Social Security planning?
Performing Roth conversions in the years before claiming Social Security or reaching RMD age allows retirees to shift pre-tax funds into tax-free accounts at potentially lower tax rates. This strategy can reduce future taxable income, manage Medicare premiums, and increase retirement flexibility.
Multi-Generational Roth Conversion Planning
With the new 10-Year Rule in effect, passing along a Traditional IRA could create a major tax burden for your beneficiaries. One strategy gaining traction among high-net-worth families and retirees is the “Next Gen Roth Conversion Strategy.” By paying tax now at lower rates, you may be able to pass on a fully tax-free Roth IRA—one that continues growing tax-free for years after the original account owner has passed away.
With the new 10-Year Rule in place for non-spouse beneficiaries of retirement accounts, one of the new tax strategies for passing tax-free wealth to the next generation is something called the “Next Gen Roth Conversion Strategy”. This tax strategy works extremely well when the beneficiaries of the retirement account are expected to be in the same or higher tax bracket than the current owner of the retirement account.
Here's how the strategy works. The current owner of the retirement account begins to initiate large Roth conversions over the course of a number of years to purposefully have those pre-tax retirement dollars taxed in a low to medium tax bracket. This way, when it comes time to pass assets to their beneficiaries, the beneficiaries inherit Roth IRA assets instead of pre-tax Traditional IRA and 401(k) assets that could be taxed at a much higher rate due to the requirement to fully liquidate and pay tax on those assets within a 10-year period.
In addition to lowering the total income tax paid on those pre-tax retirement assets, this strategy can also create multi-generational tax-free wealth, reduce the size of an estate to save on estate taxes, and reduce future RMDs for the current account owner.
10-Year Rule for Non-Spouse Beneficiaries
This tax strategy surfaced when the new 10-Year Rule went into place with the passing of the Secure Act. Non-spouse beneficiaries who inherit pre-tax retirement accounts are now required to fully deplete and pay tax on those account balances within a 10-year period following the passing of the original account owner. In many cases when children inherit pre-tax retirement accounts from their parents, they are still working, which means that they already have income on the table.
For example, if Josh, a non-spouse beneficiary, inherits a $600,000 Traditional IRA from his father when he is age 50, he would be required to pay tax on the full $600,000 within 10 years of his father passing. But what if Josh is married and he and his wife still work and are making $360,000 per year? If Josh and his wife do not plan to retire within the next 10 years, the $600,000 that is required to be distributed from that inherited IRA while they are still working could be subject to very high tax rates since the taxable distribution stacks on top of the $360,000 that they are already making. A large portion of those IRA distributions could be subject to the 32% federal tax bracket.
If Josh’s father had started making $100,000 Roth conversions each year while both he and Josh’s mother were still alive, they could have taken advantage of the 22% Federal Tax Bracket I in 2025 (which ranges from $96,951 to $206,000 in taxable income). If they had very little other income in retirement, they could have processed large Roth conversions, paid just 22% in federal taxes on the converted amount, and eventually passed a Roth IRA on to Josh. Utilizing this strategy, the full $600,000 pre-tax IRA would have been subject to the parent’s federal tax rate of 22% as opposed to Josh’s tax rate of 32%, saving approximately $60,000 in taxes paid to the IRS.
Tax Free Accumulations For 10 More Years
But it gets better. By Josh’s parents processing Roth conversions while they were still alive, not only is there multigenerational tax savings, but when John inherits a Roth IRA instead of a Traditional IRA from his parents, all of the accumulation within that Roth IRA since the parents completed the conversion, PLUS 10 years after Josh inherits the Roth IRA, are completely tax-free.
Multi-generational Tax-Free Wealth
If you are a non-spouse beneficiary, whether you inherited a pre-tax retirement account or a Roth IRA, you are subject to the 10-year distribution rule (unless you qualify for one of the exceptions). With a pre-tax IRA or 401(k), not only is the beneficiary required to deplete and pay tax on the account within 10 years, but they may also be required to process RMDs (required minimum distributions) from their inherited IRA each year, depending on the age of the decedent when they passed away.
With an Inherited Roth IRA, the account must be depleted in 10 years, but there is no annual RMD requirement, because RMDs do not apply to Roth IRAs subject to the 10-year rule. So, essentially, someone could inherit a $500,000 Roth IRA, take no money out for 9 years, and then at the end of the 10th year, distribute the full balance TAX-FREE. If the owner of the inherited Roth IRA invests the account wisely and obtains an 8% annualized rate of return, at the end of year 10 the account would be worth $1,079,462, which would be withdrawn completely tax-free.
Reduce The Size of an Estate
For individuals who are expected to have an estate large enough to trigger estate tax at the federal and/or state level, this “Next Gen Roth Conversion” strategy can also help to reduce the size of the estate subject to estate tax. When a Roth conversion is processed, it’s a taxable event, and any tax paid by the account owner essentially shrinks the size of the estate subject to taxation.
If someone has a $15 million estate, and included in that estate is a $5 million balance in a Traditional IRA and that person does nothing, it creates two problems. First, the balance in the Traditional IRA will continue to grow, increasing the estate tax liability that will be due when the individual passes assets to the next generation. Second, if there are only two beneficiaries of the estate, each beneficiary will have to move $2.5 million into their own inherited IRA and fully deplete and pay tax on that $2.5M PLUS earnings within a 10-year period. Not great.
If, instead, that individual begins processing Roth conversions of $500,000 per year, and over a course of 10 years can fully convert the Traditional IRA to a Roth IRA (ignoring earnings), two good things can happen. First, if that individual pays an effective tax rate of 30% on the conversions, it will decrease the size of the estate by $1.5 million ($5M x 30%), potentially lowering the estate tax liability when assets are passed to the beneficiaries of the estate. Second, even though the beneficiaries of the estate would inherit a $3.5M Roth IRA instead of a $5M Traditional IRA, no RMDs would be required each year, the beneficiaries could invest the Inherited Roth IRA which could potentially double the value of the Inherited Roth IRA during that 10-year period, and withdraw the full balance at the end of year 10, completely tax free, resulting in big multi-generational tax free wealth.
The Power of Tax-Free Compounding
Not only does the beneficiary of the Roth IRA benefit from tax-free growth for the 10 years following the account owner's death, but they also receive the benefit of tax-free growth and withdrawal within the Roth IRA, as long as the account owner is still alive. For example, if someone begins these Roth conversions at age 70 and they live until age 90, that’s 20 years of compounding, PLUS another 10 years after they pass away, so 30 years in total.
A quick example showing the power of this tax-free compounding effect: someone processes a $200,000 Roth conversion at age 70, lives until age 90, and achieves an 8% per year rate of return. When they pass away at age 90, the balance in their Roth IRA would be $932,191. The non-spouse beneficiary then inherits the Roth IRA and invests the account, also achieving an 8% annual rate of return. In year 10, the Inherited Roth IRA would have a balance of $2,012,531. So, the original owner of the Traditional IRA paid tax on $200,000 when the Roth conversion took place, but it created a potential $2M tax-free asset for the beneficiaries of that Roth IRA.
Reduce Future RMDs of Roth IRA Account Owner
Outside of creating the multi-generational tax-free wealth, by processing Roth conversions in retirement, it’s shifting money from pre-tax retirement accounts subject to annual RMDs into a Roth IRA that does not require RMDs. First, this lowers the amount of future taxable RMDs to the Roth IRA account owner because assets are being shifted from their Traditional IRA to Roth IRA, and second, since RMDs are not required from Roth IRAs, the assets in that IRA are allowed to continue to compound investment returns without disruption.
About Michael……...
Hi, I’m Michael Ruger. I’m the managing partner of Greenbush Financial Group and the creator of the nationally recognized Money Smart Board blog . I created the blog because there are a lot of events in life that require important financial decisions. The goal is to help our readers avoid big financial missteps, discover financial solutions that they were not aware of, and to optimize their financial future.
Frequently Asked Questions (FAQs):
What is the “Next Gen Roth Conversion Strategy”?
The Next Gen Roth Conversion Strategy involves gradually converting pre-tax retirement assets, such as Traditional IRAs or 401(k)s, into Roth IRAs while the account owner is in a lower tax bracket. This allows heirs to inherit Roth assets that grow and distribute tax-free rather than being forced to pay higher taxes under the 10-Year Rule for inherited pre-tax accounts.
How does the 10-Year Rule affect inherited retirement accounts?
Under the SECURE Act, non-spouse beneficiaries must fully deplete inherited pre-tax retirement accounts within 10 years of the original owner’s death. This often forces distributions during high-income years, which can push beneficiaries into higher tax brackets and increase total taxes owed.
Why is this strategy beneficial for high-earning heirs?
When heirs are in the same or higher tax bracket as the original account owner, converting to a Roth during the parent’s lifetime allows the taxes to be paid at a lower rate. The heirs then inherit a Roth IRA that continues to grow tax-free and can be withdrawn without triggering additional income tax.
How does the strategy create multi-generational tax-free wealth?
After the account owner passes, heirs can keep the inherited Roth IRA invested for up to 10 years without required minimum distributions (RMDs). All investment growth during that time is tax-free, and the full balance can be withdrawn at the end of year 10 with no taxes owed.
Can Roth conversions also reduce estate taxes?
Yes. The taxes paid during the conversion process reduce the overall size of the estate, which may lower exposure to federal or state estate taxes. Converting pre-tax assets to Roth IRAs can therefore benefit both the heirs and the estate itself.
How does this strategy help minimize future RMDs?
By converting pre-tax accounts to Roth IRAs, retirees reduce the balance of assets subject to required minimum distributions. Since Roth IRAs do not require RMDs during the owner’s lifetime, more assets can continue compounding tax-free for longer.
What makes the Next Gen Roth Conversion Strategy so powerful?
It combines proactive tax planning, estate reduction, and multi-generational wealth transfer. Taxes are paid strategically at lower rates, future RMDs are minimized, and beneficiaries receive assets that can grow for up to a decade after inheritance—completely tax-free.
Roth Conversions In Retirement
Roth conversions in retirement are becoming a very popular tax strategy. It can help you to realize income at a lower tax rate, reduce your RMD’s, accumulate assets tax free, and pass Roth money onto your beneficiaries. However, there are pros and cons that you need to be aware of, because processing a Roth conversion involves showing more taxable income in a given year. Without proper tax planning, it could lead to unintended financial consequences such as:
· Social Security taxed at a higher rate
· Higher Medicare premiums
· Assets lost to a long term care event
· Higher taxes on long term capital gains
· Losing tax deductions and credits
· Higher property taxes
· Unexpected big tax liability
In this video, Michael Ruger will walk you through some of the strategies that he uses with his clients when implementing Roth Conversions. This can be a very effective wealth building strategy when used correctly.

About Michael……...
Hi, I’m Michael Ruger. I’m the managing partner of Greenbush Financial Group and the creator of the nationally recognized Money Smart Board blog . I created the blog because there are a lot of events in life that require important financial decisions. The goal is to help our readers avoid big financial missteps, discover financial solutions that they were not aware of, and to optimize their financial future.